On September 17, 2026, the Commodity Futures Trading Commission issued what may become one of the year’s most important pieces of CFTC crypto guidance for developers building trading interfaces. The new position gives qualifying providers of “passive software” a path to facilitate users’ access to CFTC-regulated derivatives without registering as introducing brokers, provided they satisfy specific conditions.
That is the core of the new CFTC crypto guidance: software can remain software rather than automatically becoming a regulated intermediary merely because it gives users a front end for trading.
For U.S. traders, the implications are practical. A wallet or application could potentially connect users to regulated futures commission merchants, introducing brokers and designated contract markets without taking custody of customer assets or making trading decisions itself.
But the CFTC crypto guidance is not a blanket exemption for every crypto application. It is conditional staff relief, and the distinction between a passive interface and an active intermediary is critical.
The question for developers is therefore not simply, “Can my wallet offer derivatives?” It is: Can my software meet the CFTC’s definition and conditions for passive operation?
Caption: CFTC crypto guidance 2026 is giving qualifying passive-software providers a clearer route to connect users with regulated derivatives markets.
What the CFTC Actually Announced: The CFTC Crypto Guidance Explained
The September 17 action came from the CFTC’s Market Participants Division through Staff Letter 26-25. The agency said its staff would not recommend enforcement against qualifying passive-software providers or relevant personnel for failure to register as an introducing broker or associated person, subject to specified conditions.
The CFTC crypto guidance applies specifically to the provider’s provision and marketing of software that facilitates users’ trading with registered futures commission merchants, introducing brokers and designated contract markets.
That wording matters.
The CFTC did not announce that all crypto wallets are now outside broker rules. Instead, it created a conditional no-action position that can apply to software providers whose role remains sufficiently passive.
The CFTC’s description is important because the agency is drawing a functional line between technology that provides an interface and an intermediary that actively participates in a transaction.
A passive software provider can, subject to the letter’s conditions, provide functionality allowing users to:
- View market information.
- View available products.
- Review position information.
- Submit orders to registered counterparties.
- Access CFTC-regulated derivatives through an interface.
- Use self-custodial software without handing control of their assets to the software provider.
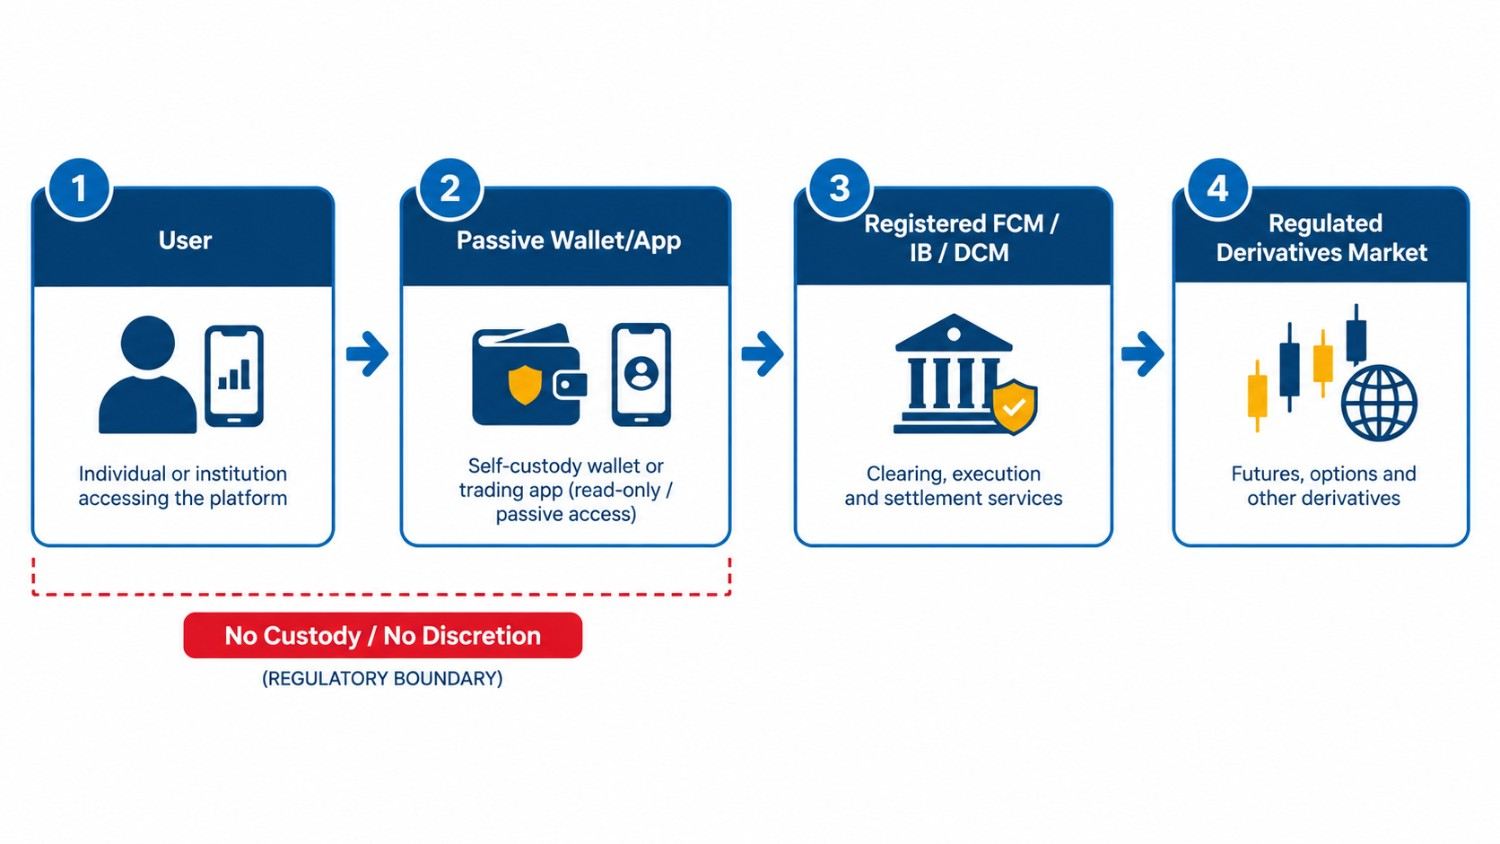
The provider’s role becomes problematic if it crosses into activities such as custody, trading discretion, order-routing discretion, investment recommendations, or other forms of active participation.
That is why the CFTC crypto guidance should be understood as a boundary-setting exercise rather than a general deregulation of crypto applications.
In simple terms:
The software can provide the road and dashboard; the regulated financial intermediary remains responsible for the regulated market activity.
The CFTC’s September announcement explicitly says the new position is similar to the relief granted in March and is now broadly available to qualifying passive-software providers.
The Conditions You Must Meet to Qualify
The phrase “passive software exemption” is useful shorthand, but technically the regulatory mechanism is a no-action position, not a statutory exemption.
The CFTC crypto guidance is conditional.
According to the CFTC’s letter and legal analysis of Staff Letter 26-25, qualifying providers must satisfy a series of requirements designed to keep the software provider from becoming an active intermediary.
The major conditions include:
- No custody of customer assets. The software provider must not take possession or control of users’ funds or digital assets.
- No trading discretion. The provider cannot decide whether a user should buy or sell.
- No discretionary order routing. The software cannot independently determine where or how an order should be executed in a way that makes the provider an active intermediary.
- Direct onboarding with regulated entities. Users must be onboarded with the registered intermediary rather than being transformed into customers solely of the software provider.
- Independent access. Users must be able to access the registered intermediary independently of the passive software provider.
- Risk and conflict disclosures. The provider must satisfy specified disclosure obligations.
- Compliant advertising. Marketing must comply with applicable requirements, including conditions concerning National Futures Association standards.
- Recordkeeping. The provider must maintain required records.
- CFTC jurisdiction. The provider must consent to CFTC jurisdiction under the conditions described in the letter.
- Responsibility arrangements with registered entities. The framework includes specified undertakings involving the registered firms the software connects to.
The practical lesson from the CFTC crypto guidance is that “non-custodial” alone is not enough.
A wallet could avoid holding customer assets and still perform activities that move it beyond the passive-software framework.
The legal question is therefore functional: What does the software actually do?
The CFTC’s original March relief involved Phantom Technologies and Staff Letter 26-09. The agency’s September letter expands the framework beyond that original provider. The CFTC’s staff-letter index identifies 26-09 as the March position covering a self-custodial crypto wallet and 26-25 as the September position covering passive software providers more broadly.
The Phantom-Kalshi precedent
The March Phantom action is particularly important because it demonstrated how a self-custodial crypto wallet could potentially connect users to regulated markets without becoming a traditional broker itself.
Phantom subsequently became associated with Kalshi prediction-market access, giving the industry a concrete example of the model.
Reports have described Phantom’s user base as exceeding 20 million, illustrating why the issue matters beyond a niche developer audience.
The September CFTC crypto guidance effectively takes the model from a company-specific precedent and makes similar relief available to other qualifying providers.
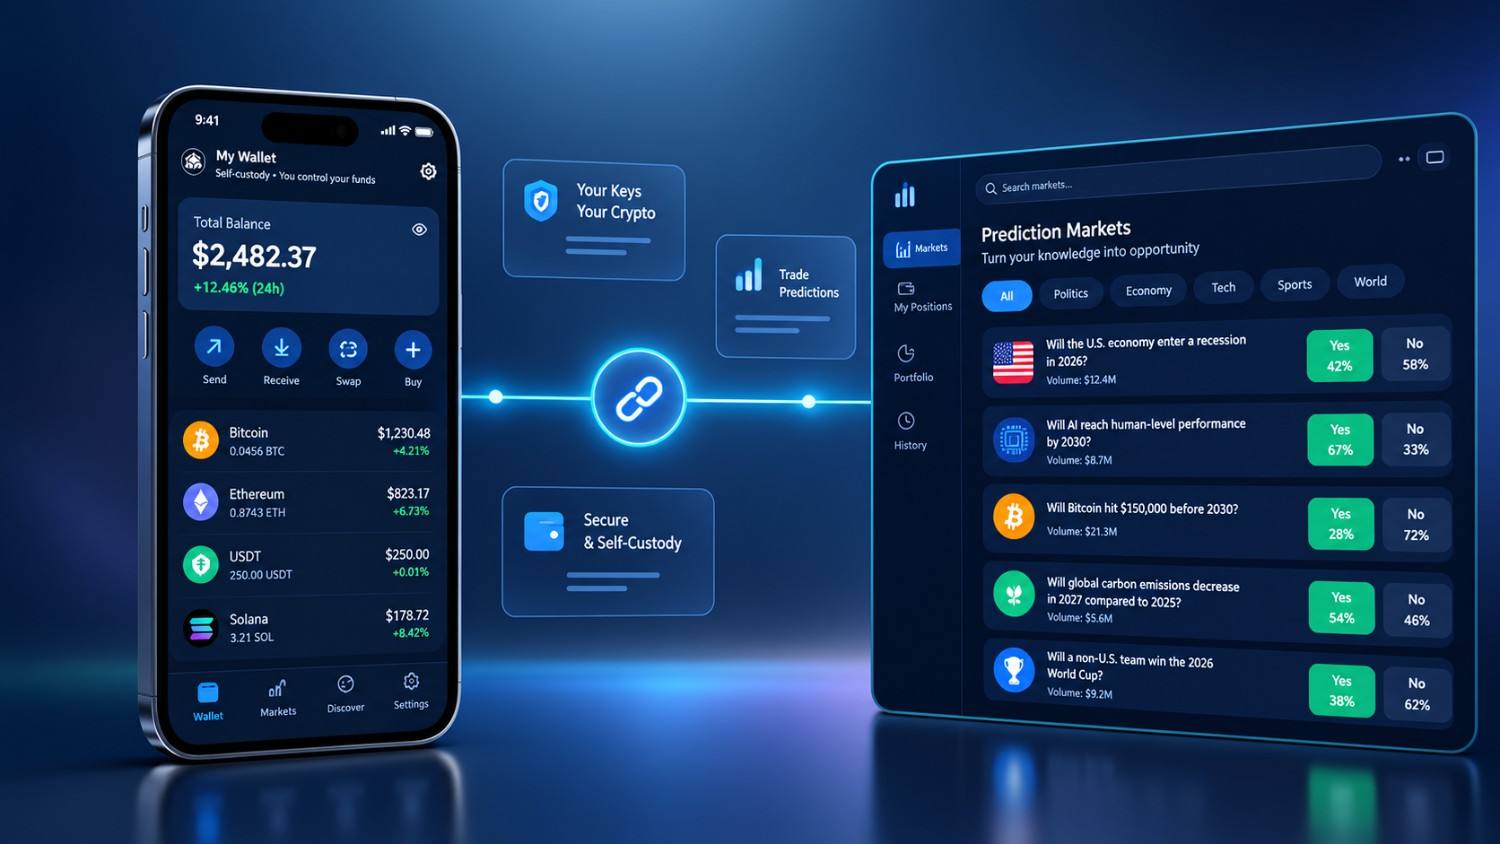
Caption: CFTC crypto guidance creates a conditional passive-software pathway between users, software interfaces and regulated derivatives venues.
Why the CFTC Crypto Guidance Matters for U.S. Traders and Developers
Before the September action, a company building a wallet or trading interface could face a difficult question: if the software lets a user submit an order to a regulated derivatives venue, does the interface itself become an introducing broker?
The CFTC crypto guidance provides staff-level relief when the provider fits the passive-software model and meets the specified conditions.
That can change how developers structure products.
A wallet could potentially become a gateway to:
- Regulated futures.
- Event contracts.
- Prediction-market contracts.
- Crypto perpetual contracts.
- Other CFTC-regulated derivatives.
The key is that the wallet does not become the entity actually providing the regulated market infrastructure.
For traders, the potential benefit is convenience. Instead of moving between multiple applications, a user could potentially access regulated products through software they already use.
But convenience does not eliminate trading risk.
A prediction market remains a derivative-style product. A perpetual contract can involve substantial leverage and liquidation risk. A self-custodial wallet also leaves users responsible for security, authentication and transaction decisions.
The CFTC crypto guidance changes the regulatory architecture around access. It does not turn speculative trading into low-risk investing.
Caption: CFTC crypto guidance could change how U.S. traders access regulated crypto derivatives and prediction markets through familiar software interfaces.
The CLARITY Act Setback and Why Agency Guidance Now Leads
The timing of the CFTC crypto guidance is difficult to ignore.
Two days before the CFTC action, the U.S. Senate failed to advance the CLARITY Act in a procedural vote.
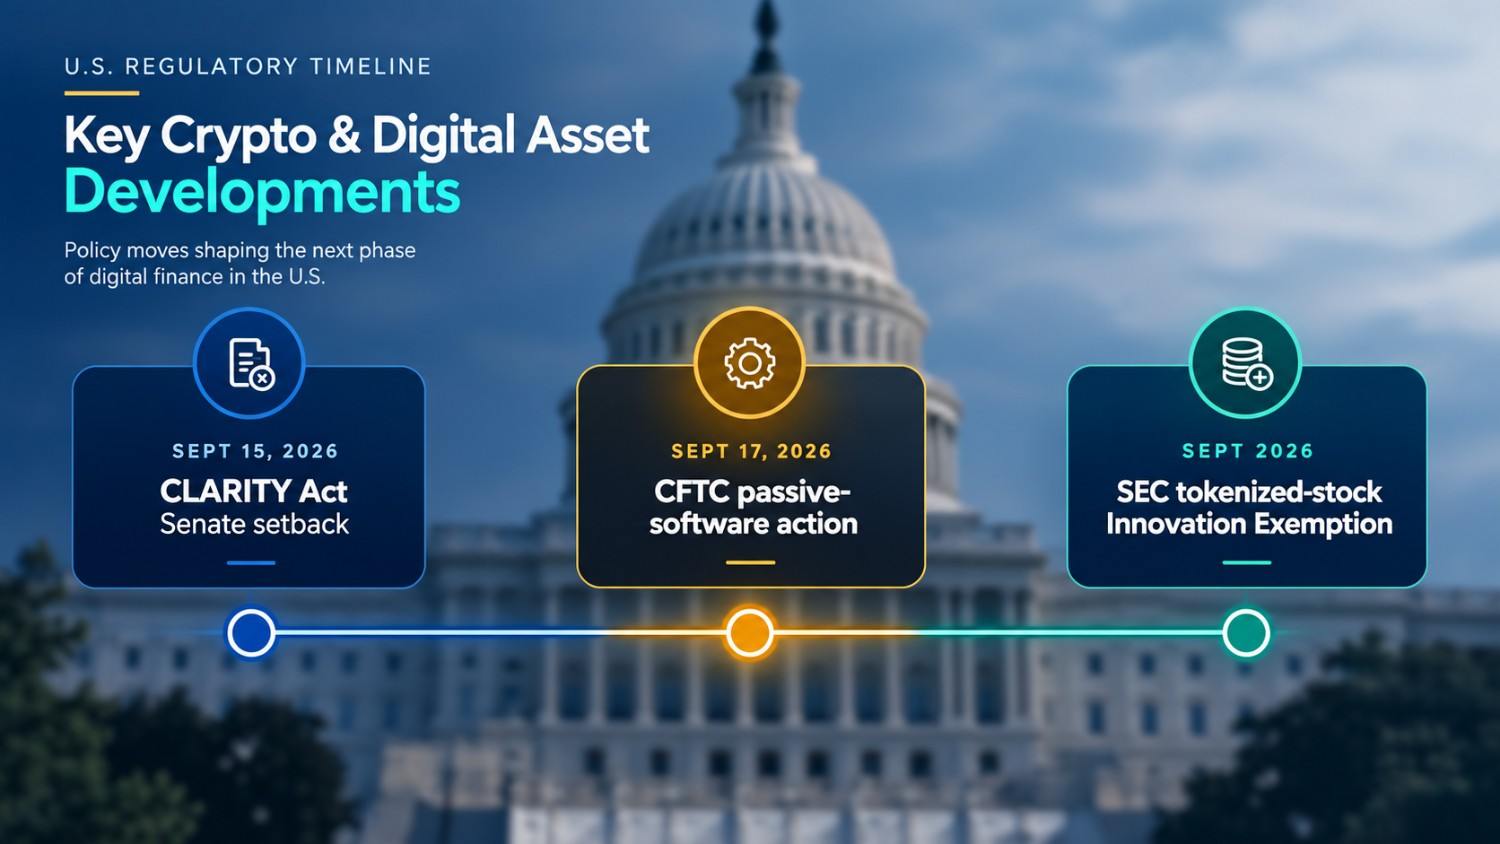
The September 15 vote fell short of the 60 votes needed to advance the legislation. Reuters reported that the measure received 50 votes in favor and 49 against, leaving the broader federal market-structure framework stalled.
The significance is not that the CLARITY Act has necessarily disappeared forever. The significance is that comprehensive legislation has not yet supplied the durable statutory framework that many market participants have been seeking.
That makes agency action more important in the near term.
The CFTC crypto guidance is therefore part of a broader regulatory story: federal agencies are using their existing authorities to address specific market structures while Congress continues to debate legislation.
CoinDesk reported that the failed Senate vote became a significant market event for crypto, while The Wall Street Journal reported that the legislative setback shifts attention back toward agencies such as the SEC and CFTC.
For developers, that creates both opportunity and uncertainty.
Agency relief can arrive much faster than a new federal statute. But staff no-action positions and temporary exemptions do not necessarily have the same durability as legislation enacted by Congress.
That distinction should remain central to any analysis of the CFTC crypto guidance.
The Bigger Picture — CFTC and SEC Move in Tandem
The CFTC did not act in isolation.
On September 17, the same day as the passive-software announcement, the Securities and Exchange Commission issued its own “Innovation Exemption” for certain tokenized National Market System stocks.
The SEC’s action provides temporary, conditional relief for Tokenized Securities Venues using permissioned automated market makers and liquidity pools to trade qualifying tokenized stocks.
The exemption is subject to conditions including limits on symbols and trading volume, investor-rights requirements, issuer notification and objection procedures, public smart contracts and trading-stoppage coordination.
The SEC said the exemption will expire five years after publication.
Taken together, the SEC and CFTC actions point toward a similar regulatory experiment.
The CFTC crypto guidance addresses the software layer connecting users with regulated derivatives markets.
The SEC’s Innovation Exemption addresses an infrastructure layer for tokenized securities markets.
Neither action creates a permanent comprehensive crypto market structure.
Instead, both demonstrate how agencies can use existing authority to accommodate specific technology models while gathering information for future regulation.
That is a crucial distinction for institutional investors and developers.
The current regulatory environment is becoming more specific, but it is not necessarily becoming final.
Expert Analysis and Market Implications
The immediate market implication of the CFTC crypto guidance is likely to be more important for infrastructure companies than for Bitcoin’s short-term price.
The clearest beneficiaries are potentially developers building wallets, interfaces, trading applications and financial platforms that want to connect users with regulated derivatives.
The September action could also increase competitive pressure among platforms offering prediction markets and derivatives.
Investor’s Business Daily reported that the announcement affected shares of companies exposed to prediction-market competition, with sports-betting companies declining while some financial platforms with prediction-market exposure gained.
That does not mean the CFTC action guarantees higher crypto prices or trading volumes.
A more measured interpretation is that the CFTC crypto guidance removes one layer of regulatory uncertainty for a defined category of software providers.
The longer-term effect will depend on adoption.
Developers still need to determine whether their architecture actually fits the conditions. Regulated counterparties must remain willing to work with them. Users must adopt the products. And regulators can modify the framework.
The Blockchain Association described the action as important clarity for developers while also emphasizing that the relief is an interim step and that durable regulatory clarity remains important.
That is probably the most useful way for sophisticated investors to view the announcement: meaningful regulatory clarification, but not the end of U.S. crypto-regulatory uncertainty.
What to Watch Next
The next phase of the CFTC crypto guidance story will be implementation.
1. More wallet and trading-app integrations
Watch for announcements from self-custodial wallets and trading applications seeking connections with registered futures commission merchants and designated contract markets.
The important question will be whether these integrations preserve the passive characteristics described by the CFTC.
2. More CFTC guidance
The September action may not be the final word on software interfaces.
Future CFTC statements could address other forms of automated trading, decentralized interfaces, data services and derivatives infrastructure.
3. Prediction-market expansion
Prediction markets are likely to remain a major test case.
The CFTC’s framework could make it easier for software providers to connect users with regulated event contracts, but the market will still face questions involving contract design, state-level disputes, compliance and market integrity.
4. Crypto derivatives open interest
Institutional traders should monitor derivatives open interest, funding rates, volume and liquidation activity rather than assuming that regulatory clarity automatically produces stronger prices.
If more applications add regulated derivatives access, the resulting competition could affect liquidity and user acquisition across platforms.
5. The CLARITY Act
Congressional action remains important.
The CFTC crypto guidance can provide administrative relief, but legislation would provide a different type of durability.
The September Senate setback therefore does not eliminate the importance of future congressional action.
6. SEC-CFTC coordination
The simultaneous SEC and CFTC actions are worth watching.
If both agencies continue creating technology-specific pathways under existing authority, U.S. digital-asset infrastructure could increasingly develop through agency action while Congress works toward broader legislation.
Frequently Asked Questions
What is the CFTC passive software exemption?
The term “passive software exemption” describes the conditional no-action relief in the CFTC crypto guidance for qualifying software providers that facilitate access to regulated derivatives without becoming active intermediaries.
Technically, it is a staff no-action position rather than a new statutory exemption.
Does the CFTC crypto guidance apply to my wallet?
Potentially, if the wallet qualifies as passive software and satisfies all applicable conditions in Staff Letter 26-25.
The CFTC crypto guidance does not automatically cover every wallet simply because it is self-custodial. The software’s actual functionality and relationship with regulated counterparties matter.
Can a crypto wallet now offer prediction-market trading?
The CFTC crypto guidance creates a pathway for qualifying passive software to facilitate users’ access to CFTC-regulated event contracts and other derivatives through registered entities.
The wallet still needs to satisfy the letter’s conditions.
How does the CFTC regulate prediction markets?
The CFTC crypto guidance is relevant when prediction-market products fall within the CFTC’s regulated derivatives framework. The agency regulates derivatives markets through its statutory authority and registered market infrastructure.
Prediction markets can also raise legal questions outside the CFTC’s direct jurisdiction, so the September action should not be interpreted as resolving every prediction-market dispute.
Does the CFTC no-action letter mean crypto developers no longer need registration?
No.
The CFTC crypto guidance provides conditional relief from specified introducing-broker and associated-person registration requirements for qualifying passive software providers.
A developer whose product performs activities outside the letter’s conditions cannot simply assume the relief applies.
Does the CLARITY Act change the CFTC crypto guidance?
Not directly.
The CFTC crypto guidance is based on the CFTC’s existing authority and Staff Letter 26-25. The failed September 15 Senate vote matters because the CLARITY Act would establish a broader statutory framework if enacted.
The legislative and agency tracks should therefore be viewed separately.
Conclusion: What the CFTC Crypto Guidance Really Changes
The most important takeaway from the CFTC crypto guidance is not that crypto wallets have suddenly become unregulated.
They have not.
The important development is narrower and more useful: qualifying passive software providers now have a clearer regulatory pathway for connecting users with regulated derivatives markets without automatically registering as introducing brokers.
The CFTC crypto guidance also expands the significance of the March Phantom precedent. What began as relief for a specific self-custodial wallet model has now become a broadly available framework for similarly situated software providers.
For developers, that could reduce compliance uncertainty and encourage new products.
For traders, it could mean easier access to prediction markets and regulated crypto derivatives.
For institutional investors, the more important signal is structural: U.S. regulators are increasingly addressing blockchain-based market infrastructure through targeted agency action.
But the CFTC crypto guidance remains conditional, and the failed CLARITY Act vote means the search for durable statutory certainty is not over.
The next stage will be implementation.
Watch which wallets integrate regulated derivatives, which registered firms partner with them, how prediction-market volumes evolve, and whether Congress eventually supplies a permanent framework.
For U.S. crypto markets, the distinction between software, intermediaries, and regulated venues is becoming one of the most important regulatory questions of 2026.