The Fed rate hike in the 2026 story has once again changed the financial landscape.
On September 16, 2026, the Federal Open Market Committee raised the federal funds target range by 25 basis points, from 3.50%-3.75% to 3.75%-4.00%.
The decision was unanimous, 12-0, and marked the Federal Reserve’s first rate increase since July 2023. The Fed said inflation remains elevated and that the move would support a timelier return toward its 2% inflation goal
For households, however, the important question isn’t what happened inside the Federal Reserve building.
It’s what happens to your mortgage, savings account, credit card, investment portfolio, retirement plan, and crypto holdings.
The answer isn’t as simple as “higher rates are bad.”
You may also be intrested in:
A rate increase can make borrowing more expensive while simultaneously improving the returns available on cash and short-term fixed-income investments. It can pressure risk assets while potentially benefiting savers. And for homeowners, the effect depends heavily on whether you already have a fixed-rate mortgage or are shopping for a new loan.
This guide breaks down the Fed’s rate-hike decision in 2026 from a personal-finance perspective and explains what the latest policy signals could mean through the rest of the year.
What the Fed Just Did and Why It Matters
The Federal Reserve raised its benchmark interest-rate target by 25 basis points, placing the federal funds rate range at 3.75%-4.00%.
One basis point equals one-hundredth of a percentage point, so 25 basis points equals 0.25 percentage points.
That might sound small.
For a household carrying hundreds of thousands of dollars of debt, however, even relatively small changes in borrowing costs can become meaningful.
Why did the Fed raise rates?
The Fed’s official statement pointed to elevated inflation.
Economic activity was described as expanding at a solid pace, domestic spending remained resilient, productivity growth was strong, and capital investment was robust. At the same time, inflation remained elevated.
Fed Chair Kevin Warsh was even more direct during his September 16 press conference.
He said:
“The plain fact is that inflation is too high and has been for too long.”
Warsh also said the summer inflation readings did not show enough evidence that underlying trends had meaningfully improved.
That tells you something important about the Fed rate hike in 2026.
This wasn’t simply a mechanical adjustment.
It was a policy signal that the Federal Reserve is willing to keep monetary conditions restrictive when inflation remains above its objective.
Is this another 2022-style rate-hiking cycle?
Not necessarily.
The current environment is different from the aggressive tightening campaign that began in 2022.
The Fed raised rates repeatedly in 2022 and 2023 as it attempted to bring inflation down from historically elevated levels. The September 2026 increase came after the federal funds rate had been held at lower levels and after the Fed had spent a period assessing inflation, economic growth, and labor-market conditions.
The latest move can therefore be seen as a renewed tightening step, rather than simply continuing the 2022-2023 sequence.
That distinction matters for consumers.
A single 25-basis-point increase doesn’t automatically mean that borrowing costs will surge everywhere.
But it does mean that households should take the possibility of higher-for-longer interest rates seriously.
What should you do with that information?
Start with the part of your financial life that responds most quickly to interest rates.
For many households, that means
- Credit card balances
- Variable-rate loans
- HELOCs
- New mortgages
- Savings accounts
- Money-market products
- Short-term bonds
- Cash reserves
If you’re tracking the next Federal Reserve meeting, don’t rely on headlines alone.
CME FedWatch translates 30-Day Fed Funds futures prices into market-implied probabilities for upcoming FOMC decisions. It is useful for understanding what interest-rate traders are pricing—not for predicting what the Fed must do.
Mortgage Rates Just Hit 7%
If you’re shopping for a house, the Fed rate hike in 2026 matters—but there is an important distinction.
The Federal Reserve does not directly set the 30-year mortgage rate.
Mortgage rates are influenced by Treasury yields, mortgage-backed securities, inflation expectations, economic growth, lender pricing, and other market factors.
Nevertheless, Federal Reserve policy can influence the broader interest-rate environment.
And right now, mortgage borrowers are dealing with rates above 7%.
Freddie Mac reported that the average 30-year fixed mortgage rate reached 7.03% on September 24, 2026, up from 6.95% one week earlier and 6.30% a year earlier. The average 15-year fixed rate was 6.42%.
What does a 7% mortgage mean for a new buyer?
Consider a simplified example.
Suppose you borrow $400,000 for 30 years.
At 7.00%, the principal-and-interest payment is approximately $2,661 per month, before taxes, insurance, mortgage insurance, and other costs.
At 6.00%, the equivalent payment would be approximately $2,398 per month.
That’s a difference of roughly $263 every month, or more than $3,100 per year.
The difference becomes much larger over the life of a mortgage.
This is why even seemingly modest changes in mortgage rates can materially affect affordability.
Existing homeowners have a different problem.
If you already have a fixed-rate mortgage, the September Fed decision doesn’t automatically change your mortgage payment.
A fixed-rate mortgage generally remains fixed according to the terms of the loan.
That’s an important distinction.
If you locked in a favorable rate several years ago, your biggest financial decision may not be whether to react to the Fed at all.
It may be whether you should leave your existing mortgage alone.
What about adjustable-rate mortgages and HELOCs?
This is where the Fed rate increase impact can be more immediate.
Variable-rate debt can respond to changes in benchmark rates.
HELOCs, for example, commonly use variable rates. When the underlying benchmark rises, the cost of carrying the balance can rise as well.
If you have a large HELOC balance, review:
- Current interest rate
- Margin above the benchmark
- Remaining draw period
- Repayment period
- Whether a fixed-rate conversion is available
- Early termination or conversion fees
Don’t automatically refinance simply because the Fed raised rates.
Calculate the break-even point.
Should you refinance after the Fed rate hike?
Not necessarily.
A refinance only makes sense when the expected savings justify:
- Closing costs
- Origination fees
- Appraisal costs
- Title expenses
- Potential points
- The amount of time you expect to remain in the home
For some borrowers, refinancing into a lower rate can make sense.
For others, waiting or keeping the existing mortgage may be financially preferable.
Your credit profile also matters.
Experian currently offers consumers access to a free FICO Score based on Experian data, and checking your own score does not lower your credit score. Experian also notes that lenders may use different scoring models.
That last point is important: your Experian score is not necessarily the exact score a mortgage lender will use.
Mortgage checklist for 2026
Before applying for a mortgage or refinance:
- Check your credit reports for errors.
- Check your credit score.
- Calculate your debt-to-income ratio.
- Compare multiple lenders.
- Compare APR, not just the headline interest rate.
- Ask about points and lender credits.
- Calculate your break-even period.
- Keep adequate cash reserves after closing.
- Don’t assume rates will automatically fall soon.
Freddie Mac’s mortgage-rate data should be treated as a national benchmark, not a personal rate quote. Actual offers vary according to borrower characteristics, property, loan type, lender, and market conditions.
Savings Accounts Are Finally Paying Again
There is another side to the Fed rate hike 2026 story.
Savers can benefit.
When short-term interest rates rise, banks and other financial institutions generally have more room to offer attractive yields on deposits and money-market products.
That doesn’t mean every bank immediately passes the increase to customers.
In fact, the difference between a competitive online savings account and a low-yield traditional bank account can be significant.
Why online savings accounts often pay more
Large traditional banks have enormous branch networks and established customer bases.
They don’t always need to compete aggressively for deposits.
Online banks have a different cost structure and frequently compete for customers through deposit rates.
That can create a significant gap.
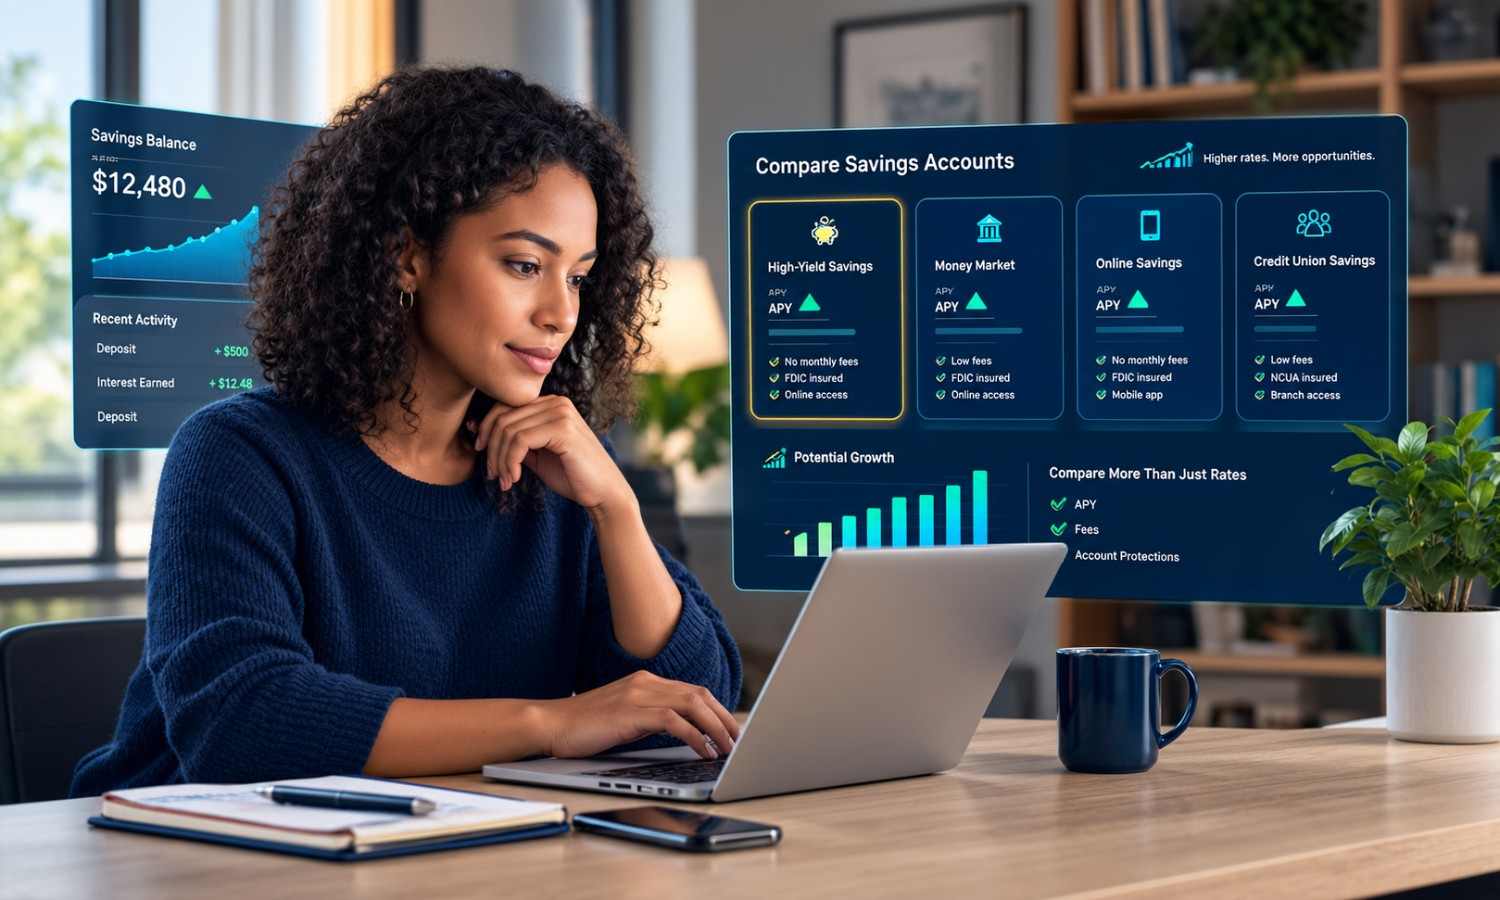
Bankrate’s September 2026 survey showed leading high-yield savings accounts offering rates as high as 4.20% APY, compared with a national average of around 0.64%.
Rates can change, however.
A 4.20% APY today isn’t necessarily a 4.20% APY six months from now.
How much difference does the rate make?
Imagine you keep $25,000 in cash.
At 0.64%, the annual interest would be approximately $160 before taxes.
At 4.20%, it would be approximately $1,050.
That’s a difference of roughly $890 per year.
The calculation is simplified and assumes the rates remain unchanged for a full year, but it illustrates why shopping for deposit rates matters.
Should you move your emergency fund?
Possibly—but safety and liquidity should come before yield.
An emergency fund is not the place to chase speculative returns.
For U.S. savers, check whether a bank is FDIC-insured or whether a credit union is federally insured by the NCUA, and understand applicable coverage limits.
Don’t assume every financial product marketed as a “cash alternative” has the same protection as a conventional insured deposit.
Compare high-yield savings rates.
Bankrate’s current comparison shows why shopping around can matter. Its September 24 data listed a top savings APY of 4.20%, while the national average was 0.64%.
When comparing accounts, don’t look only at APY.
Check:
- Minimum opening deposit
- Minimum balance
- Monthly fees
- Withdrawal restrictions
- Transfer limits
- FDIC/NCUA insurance
- Promotional-rate expiration
- Requirements for earning the advertised APY
What about the 10-year Treasury real yield?
Real yields are another important signal.
The U.S. Treasury publishes daily real-yield data based on Treasury Inflation-Protected Securities, or TIPS. These yields represent market pricing for inflation-protected government debt and can provide useful information about the real return investors demand.
The 2026 real-yield environment has been elevated compared with much of the post-financial-crisis period.
But be careful with headlines claiming that a specific real yield is “the highest since 2006” unless the exact date and Treasury series are specified.
The Treasury publishes multiple maturities and series, and a comparison must use the same maturity and methodology.
For FinWireStack readers, the broader takeaway is more useful:
Real yields are high enough to matter to savers and fixed-income investors again.
How This Rate Hike Affects Crypto and Forex Markets
Crypto investors often focus heavily on the Federal Reserve.
For good reason.
Interest rates influence the relative attractiveness of cash and bonds, financial conditions, liquidity expectations, and risk appetite.
But there is no simple rule saying:
Fed raises rates = Bitcoin falls.
Markets are more complicated than that.
What happened to stocks on Fed day?
That reaction illustrates the immediate market interpretation of the decision.
Investors weren’t simply reacting to the 25-basis-point move.
They were also reacting to what the Fed might do next.
Why crypto can become more volatile
Crypto assets generally trade as risk assets, although their behavior can vary significantly by market regime.
When investors expect higher rates for longer, some capital may become more attracted to relatively safer yield-producing assets.
At the same time:
- Liquidity expectations can change.
- The U.S. dollar can strengthen.
- Treasury yields can rise.
- Risk premiums can expand.
- Leverage can unwind.
- Speculative assets can experience larger price swings.
Bitcoin’s reaction after the September decision demonstrated why the relationship isn’t mechanical. Reuters and other market reports noted significant market volatility, while Bitcoin later showed resilience despite the rate increase.
That is why traders should avoid building a strategy around a single macroeconomic rule.
What does the Fed rate hike in 2026 mean for forex?
Forex traders watch interest-rate differentials closely.
Suppose U.S. rates remain relatively high while another central bank moves toward lower rates.
All else equal, that can influence capital flows and currency demand.
But “all else equal” is doing a lot of work.
Forex prices also respond to:
- Inflation
- Employment
- GDP growth
- Central-bank communication
- Government policy
- Geopolitical developments
- Commodity prices
- Risk sentiment
- Positioning
- Trade flows
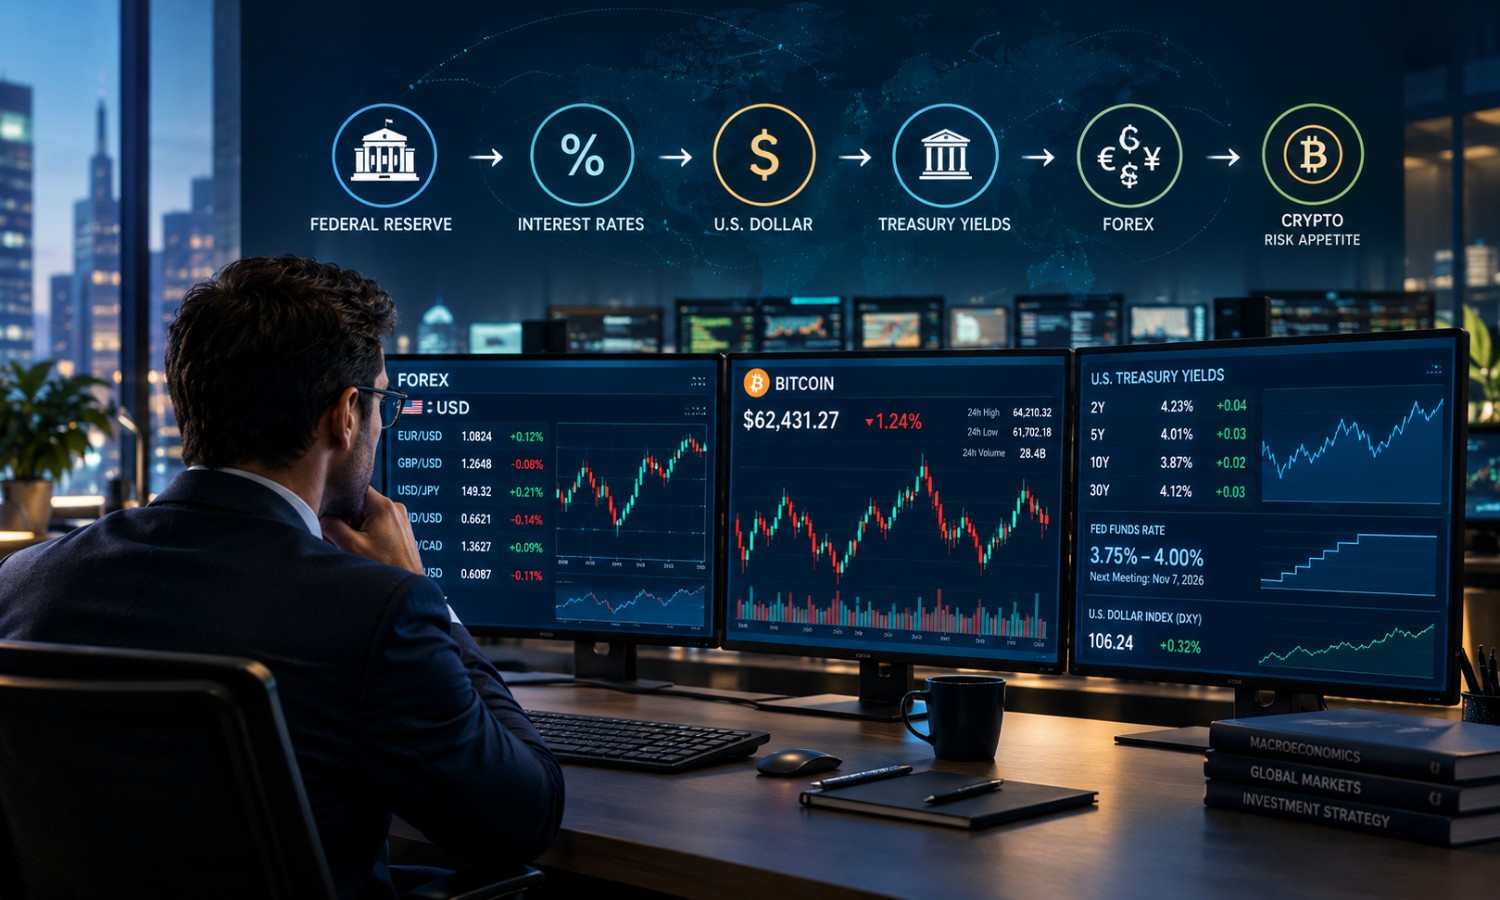
The dollar strengthened on September 16 following the Fed decision, while Treasury yields rose.
That doesn’t mean USD will rise indefinitely.
It means the Fed’s policy path became an important variable for currency markets.
Trading the Fed is not as simple as trading the headline.
Professional traders often distinguish between:
- What the market expected.
- What the Fed actually did.
- What the Fed communicated.
- How the decision changes future expectations.
A rate hike that was already fully priced into markets can produce very little movement.
A decision that changes expectations for future policy can produce much more.
That’s why the Fed rate hike in 2026 should be viewed as an information event rather than a simple buy-or-sell signal.
Broker affiliate note
Your original brief specified Exness here, but that needs a jurisdiction warning.
Exness states that it does not provide services to residents of the United States and several other jurisdictions, including the European Union and the United Kingdom. Its regulatory page also lists different regulated entities for different regions.
Therefore, do not publish a generic:
“Open a Trading Account with Exness.”
CTA to a U.S./UK/EU audience.
Instead, use a geo-targeted broker CTA.
For readers in jurisdictions where Exness is available, the CTA can lead to your tracked partner URL. For U.S., UK, and EU readers, direct them to a broker legally available in their jurisdiction.
That approach is more transparent and protects the credibility of the article.
The Retirement Impact No One Is Talking About
The Fed rate hike in 2026 isn’t only a story about mortgages and trading.
It also matters to people approaching retirement.
Why?
Because retirement planning involves a combination of:
- Income
- Cash reserves
- Bonds
- Equities
- Inflation
- Healthcare costs
- Longevity
- Taxes
- Withdrawal rates
- Interest rates
A change in interest rates can affect several of these variables simultaneously.
The retirement fluency problem
The 2026 TIAA Institute-GFLEC Personal Finance Index found that retirement knowledge remains limited.
That matters because higher interest rates don’t solve retirement planning automatically.
A retiree might earn more on cash and short-duration fixed income while simultaneously facing:
- Higher borrowing costs
- Inflation uncertainty
- Equity-market volatility
- Bond-price volatility
- Higher healthcare expenses
Understanding the interaction is more important than reacting to any single Fed announcement.
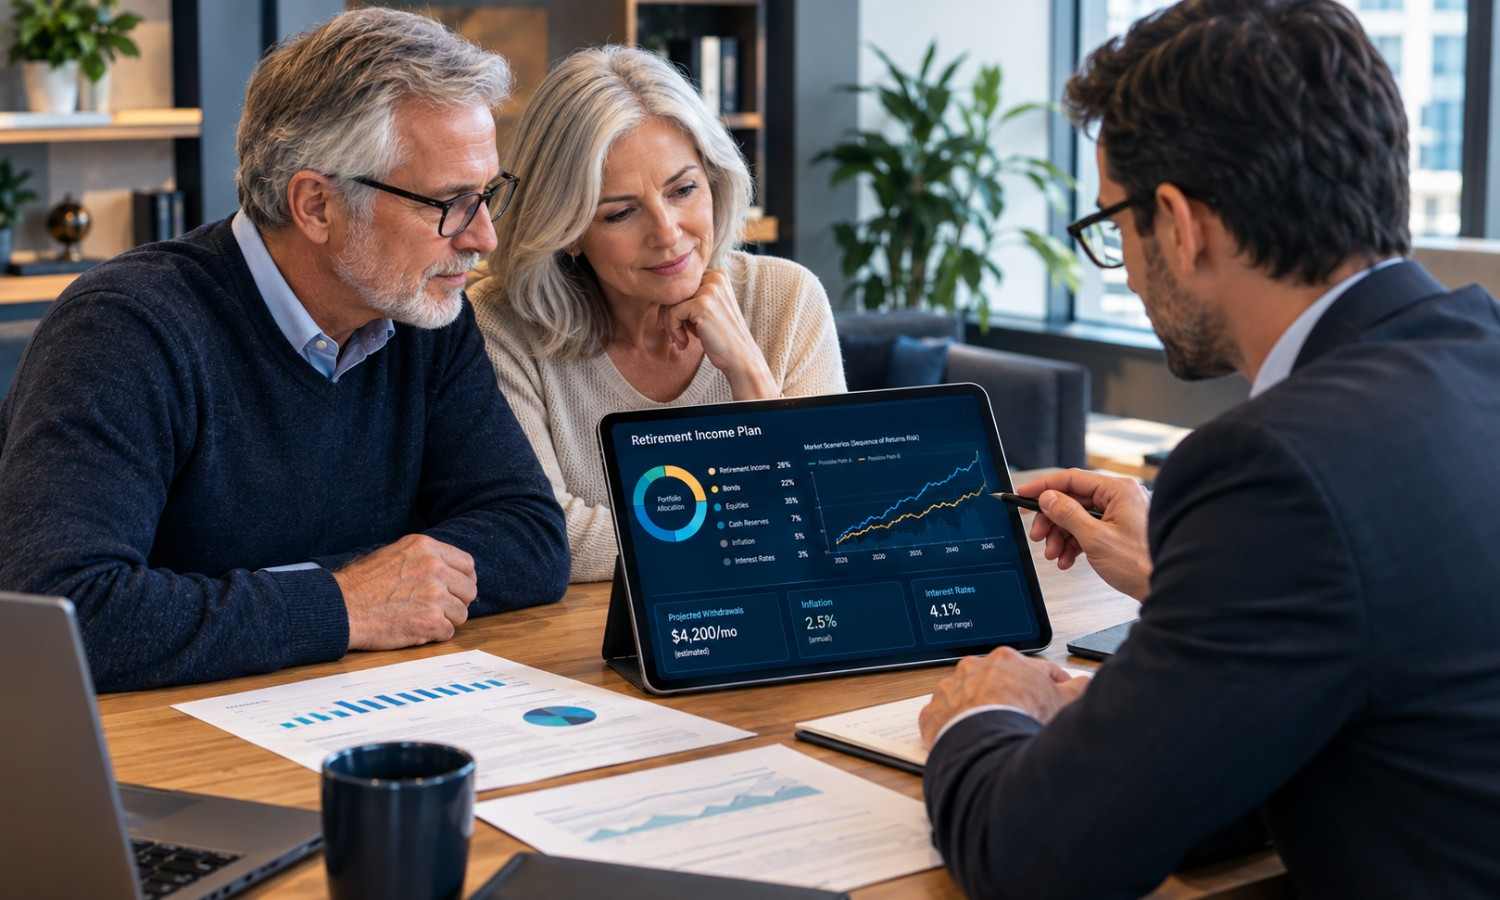
What is sequence-of-returns risk?
Sequence-of-returns risk describes the danger that poor investment returns occur early in retirement while withdrawals are being made.
Imagine two retirees who experience exactly the same long-term average investment return.
If one experiences large losses during the first few years of retirement and the other experiences those losses later, their financial outcomes can be very different because the first retiree is selling assets while the portfolio is depressed.
Higher interest rates can change the balance between growth assets and income-producing assets.
But that does not automatically mean retirees should move heavily into bonds or cash.
The right mix depends on:
- Age
- Portfolio size
- Spending needs
- Guaranteed income
- Social Security
- Pension income
- Tax situation
- Risk tolerance
- Expected longevity
Retirement within 10 years?
This is a good point to consider professional planning.
A matching service can help consumers identify financial professionals, but “fiduciary” status and compensation arrangements should still be verified directly with the advisor.
Ask:
- Are you a fiduciary?
- When does the fiduciary obligation apply?
- How are you compensated?
- Do you receive commissions?
- What services are included?
- What is the total annual cost?
- What conflicts of interest exist?
- Are you registered with the appropriate regulator?
The goal isn’t to outsource every decision.
It’s to understand the decisions that could affect decades of retirement income.
What the Fed Is Signaling for the Rest of 2026
This may be the most important part of the September decision.
The Fed didn’t simply raise rates.
Its projections showed that policymakers expect rates to remain relatively elevated.
The September Summary of Economic Projections put the median federal funds rate projection at 4.1% for the end of 2026 and 4.1% for the end of 2027, compared with June medians of 3.8% and 3.6%, respectively.
That represents a significant change in the rate outlook.
Does the dot plot guarantee another hike?
No.
The dot plot is not a promise.
It represents individual policymakers’ projections of appropriate monetary policy under their economic assumptions.
Those assumptions can change.
Inflation could fall faster than expected.
Economic growth could weaken.
Labor-market conditions could deteriorate.
Energy prices could change.
Geopolitical developments could alter the outlook.
That’s why readers should treat the dot plot as a policy signal rather than a guaranteed roadmap.
What do Fed officials expect?
The September projections indicate that another increase is part of many policymakers’ outlooks.
Reuters reported that policymakers’ median projection pointed to one more rate increase in 2026.
A separate count of the Fed’s projections showed that 16 of 18 participants expected at least one more increase during 2026.
That is important.
But it still doesn’t mean the Fed has committed to another hike.
What is CME FedWatch showing?
CME FedWatch uses federal-funds futures pricing to estimate market-implied probabilities for future FOMC decisions.
Around September 18, market pricing put the probability of another October increase above 50%, according to market reporting. A Wall Street Journal report later cited a 58% probability of an October increase.
Those probabilities can change every trading day.
The key distinction is
Fed projections ≠ market probabilities ≠ guaranteed future policy.
All three provide different pieces of information.
Why did the 2027 median jump to 4.1%?
The 2027 median is particularly important because it suggests policymakers now envision a higher rate environment than they did in June.
Reuters reported that the Fed’s projections showed a gradual path after the 2026 increase, with the median remaining at 4.1% through 2027.
For consumers, that could mean:
- Mortgage rates may remain elevated.
- Savings yields may remain attractive.
- Bond yields may remain relatively high.
- Variable-rate debt may remain expensive.
- Equity valuations may face a different discount-rate environment.
- Crypto may continue reacting strongly to liquidity expectations.
But again, these are potential transmission channels—not guaranteed outcomes.
5 Action Steps for Smart Americans Right Now
The Fed rate hike in 2026 creates different challenges for borrowers, savers, investors, and retirees.
Instead of trying to predict every move, focus on the parts of your finances you can control.
1. Check Your Credit Score
Your credit profile can materially affect the terms available to you when you apply for a mortgage, personal loan, or other credit product.
Check Your Free Credit Score →
Experian says its free service provides a FICO score based on Experian data and that checking your own score does not lower your score.
Also check your actual credit reports for errors.
For U.S. consumers, AnnualCreditReport.com is the official source for free reports from the three major credit bureaus.
Action: Review your reports before applying for major credit.
2. Compare High-Yield Savings Rates
Don’t leave a large emergency fund earning almost nothing simply because you’ve always used the same bank.
As of September 24, Bankrate listed leading savings APYs as high as 4.20%, while its national average was around 0.64%.
Action: Compare APY, fees, minimum balances, and deposit insurance before moving your money.
3. Review Your Mortgage or HELOC
If you already have a fixed-rate mortgage, don’t assume a Fed hike requires action.
If you have a variable-rate HELOC, however, calculate the effect of higher rates on your monthly payment.
If you’re buying a home, compare several lenders rather than assuming the advertised national mortgage rate is what you will receive.
Freddie Mac’s latest national average was 7.03% for a 30-year fixed mortgage as of September 24.
Action: Get multiple quotes and compare APR and total borrowing costs.
4. Review Your Portfolio for a Higher-for-Longer Environment
This does not mean selling stocks because the Fed raised rates.
It means understanding your exposure.
Ask:
- How much cash do I need?
- How much debt do I carry?
- What is my bond duration?
- How much volatility can I tolerate?
- Am I overly concentrated in speculative assets?
- Does my portfolio match my time horizon?
- What happens if rates stay elevated for another year?
If you’re investing for decades, short-term market movements shouldn’t automatically change your long-term plan.
But if your portfolio is heavily leveraged or concentrated, a higher-rate environment deserves attention.
5. Revisit Your Retirement Plan
If retirement is less than 10 years away, interest-rate changes can affect both your income strategy and your portfolio risk.
Consider reviewing:
- Emergency reserves
- Social Security timing
- Pension income
- Bond allocation
- Equity allocation
- Healthcare expenses
- Long-term-care assumptions
- Withdrawal strategy
- Tax planning
- Estate planning
The 2026 retirement-fluency data from TIAA/GFLEC shows why these decisions can be difficult: only 27% of adults answered the Medicare question correctly, and 28% answered the long-term-care question correctly.
Action: If your retirement plan is complex, consider obtaining advice from a qualified professional and verify their credentials and compensation structure.
Frequently Asked Questions
Will the Fed raise rates again in 2026?
The September 2026 projections point toward another increase for many policymakers, and market pricing around September 18 indicated more than a 50% probability of an October increase. However, neither the Fed’s projections nor CME FedWatch guarantees a future decision.
The next scheduled FOMC meeting is October 27-28, 2026.
Should I lock in a mortgage rate now?
There is no universal answer.
If you’re already under contract or need certainty for your housing budget, locking can reduce the risk of rates moving against you before closing.
If you’re simply shopping and have flexibility, compare lenders and understand their rate-lock policies before making a decision.
Remember that the Fed does not directly set the 30-year mortgage rate.
Freddie Mac’s 30-year average was 7.03% on September 24, 2026.
Are high-yield savings accounts safe?
A high-yield savings account can be a suitable place for emergency cash when the underlying institution is properly insured and the account falls within applicable insurance limits.
For U.S. bank deposits, verify FDIC insurance. For federally insured credit unions, verify NCUA coverage.
Don’t assume that every investment product marketed as a cash alternative has the same protections.
How do rate hikes affect crypto?
Higher rates can influence crypto through liquidity conditions, opportunity costs, dollar strength, Treasury yields, and investor risk appetite.
However, the relationship is not mechanical.
Bitcoin and other crypto assets can rise or fall after a Fed hike depending on what investors had already priced in and what the Fed communicates about future policy.
The September 2026 decision demonstrated this complexity: risk assets initially reacted negatively, but crypto subsequently showed resilience.
What should retirees do right now?
Retirees shouldn’t make major portfolio decisions solely because the Federal Reserve raised rates.
Instead, review:
- Cash flow needs
- Emergency reserves
- Fixed-income exposure
- Equity risk
- Inflation protection
- Healthcare costs
- Withdrawal rates
- Tax implications
Higher rates can improve income opportunities on cash and some fixed-income investments while creating other risks.
The appropriate response depends on the individual’s complete financial situation.
Will higher Fed rates make savings accounts pay more?
They can, but banks don’t have to pass the full increase through to depositors.
Online banks and competitive savings providers may adjust their APYs more aggressively than large traditional banks.
That is why comparing rates matters.
Bankrate’s September 2026 data showed a substantial gap between top high-yield savings rates and the national average.
Does a Fed rate hike automatically mean stocks and crypto will fall?
No.
Markets respond to expectations as well as actual decisions.
If a rate increase was already fully priced in, the announcement may produce little reaction.
Conversely, changes in the Fed’s outlook can produce larger moves because investors reprice future earnings, liquidity, and discount rates.
The September 16 market reaction showed how quickly equities can move when investors interpret the Fed’s message as more restrictive.
What the Fed Rate Hike 2026 Means for Your Money
The September 2026 decision is more than another headline about the Federal Reserve.
It changes the financial backdrop for households.
For borrowers, higher rates can increase the cost of new mortgages, HELOCs, credit cards, and variable-rate debt.
For savers, the environment creates an opportunity to earn more on cash—provided you shop around and understand account protections.
For investors, higher rates change the relative attractiveness of cash and bonds while potentially affecting equity valuations and risk appetite.
For crypto and forex traders, the most important variable may not be the 25-basis-point increase itself but what the Fed signals about the next several meetings.
And for retirees, the central issue is not simply whether rates rise or fall. It is whether the entire income and risk-management strategy can withstand changing market conditions.
The latest projections show a median federal funds rate of 4.1% at the end of both 2026 and 2027, higher than policymakers projected in June.
That makes one message especially important:
Don’t build your financial plan around a single forecast.
Build it around scenarios.
What happens if mortgage rates remain around 7%?
What happens if savings rates fall?
What happens if inflation remains elevated?
What happens if the Fed raises rates again?
What happens if economic growth weakens and rates eventually decline?
The households that are best positioned for an uncertain rate environment are not necessarily the ones that predict the next Fed decision correctly.
They’re the ones whose finances can withstand several possible outcomes.
Final Takeaway
The Fed rate hike in 2026 has pushed the federal funds target range to 3.75%-4.00%, and the September projections point to a higher rate path than policymakers anticipated in June.
That means Americans should pay attention—but not panic.
If you’re borrowing, focus on your credit profile and compare financing options.
If you’re saving, compare high-yield accounts rather than accepting a low rate by default.
If you’re investing, understand how higher rates affect your particular portfolio instead of reacting to headlines.
If you’re trading crypto or forex, treat Fed announcements as macroeconomic events rather than automatic trading signals.
And if you’re approaching retirement, focus on cash flow, diversification, sequence risk, and the sustainability of your withdrawal plan.
The Federal Reserve controls a benchmark rate.
You control how prepared your household is for the environment that follows.
Disclosure: This article is for educational and informational purposes only and is not financial, investment, tax, mortgage, or retirement advice. Some links may be affiliate links, meaning FinWireStack may receive compensation if you use them, at no additional cost to you.
Author Bio
Humphrey Nyaga—Finance & Technology Writer, FinWireStack
Humphrey N is a finance and technology writer and the founder of FinWireStack, where he covers investing, trading, personal finance, financial technology, and emerging digital trends. His work focuses on making complex financial and technology topics easier to understand through research-driven, practical explanations.
FinWireStack’s editorial approach emphasizes independent research, transparent disclosures, risk awareness, and actionable financial education.
Editorial note: Financial markets, interest rates, and financial products change frequently. Readers should verify current rates, terms, fees, eligibility, and regulatory status directly with the relevant provider before making financial decisions.