Category Personal Finance

Banking, credit cards, budgeting, saving money, paying off debt.

Your AI Financial Advisor: Complete Guide to Tools, Risks, and Getting Started in 2026

AI financial advisor dashboard on a smartphone showing personalized spending insights, savings goals, and AI-powered recommendations for better money management.

Introduction: The Day Your Banking App Became Your AI Financial Advisor

You open your banking app one morning, and something feels different. Instead of just showing your balance, it gently suggests moving $200 from checking to savingsโ€”because it noticed you have a pattern of overspending on dining out mid-month. It reminds you about a bill due tomorrow and flags a subscription you completely forgot about. You didn’t ask for this advice. It just… appeared.

This isn’t a scene from a sci-fi movie. This is the reality of AI-powered personal finance in 2026, and it’s happening right now. Anย AI financial advisorย is no longer a futuristic conceptโ€”it’s a tool available to millions of consumers today.

According to Plaid’s March 2026 research, roughly 57% of U.S. consumers now expect their fintech apps to use AI, and a striking 78% are open to receiving AI-based personal financial guidance. The shift is so dramatic that a 2026 TD AI Insights report found that more than half of survey respondents said they use AI to help manage their financesโ€”compared to only 10% just a year earlier.

The global AI-powered personal finance management market is valued atย $1.77 billion in 2026, and it’s projected to reach $2.55 billion by 2030. This is no longer a niche experiment. It’s a fundamental shift in how everyday people manage, grow, and protect their money.

But here’s the question that matters most for you: Is an AI financial advisor actually good for your money, or is it just another tech trend that sounds impressive but delivers little?

This guide will give you an honest, unbiased look at the AI financial advisor tools available in 2026. We’ll cover what they can do, where they fall short, how to choose the right one, and most importantly, how to protect yourself from the hidden risks.


Part 1: What’s Actually Available Right Now (The Tools You Can Use Today)

The AI financial advisor landscape in August 2026 is rich and varied. You’re not limited to a single type of tool. Here’s what’s available:

1. ChatGPT’s Personal Finance Tools

In May 2026,ย OpenAI launched a dedicated personal finance experienceย for ChatGPT Pro users in the United States. This allows users to securely connect their financial accounts viaย Plaidโ€”which connects to over 12,000 financial institutions, including Schwab, Fidelity, Chase, and Robinhoodโ€”and ask ChatGPT questions about their spending, subscriptions, and investment portfolio.

What makes this particularly powerful is that you can combine your actual financial data with your personal goals. For example, you can ask, “I feel like I’ve been spending more recently. Has anything changed?”ย orย “Help me build a plan to be ready to buy a house in my area in the next 5 years.”

According to OpenAI,ย over 200 million people already use ChatGPT monthly for budgeting, investment questions, and financial planning. The company plans to expand the tool to Plus users after refining the experience through the Pro preview.

2. Robo-Advisors: Automated Investing on Autopilot

Robo-advisors use algorithms to build and manage investment portfolios based on your goals, timeline, and risk tolerance. They’re one of the most mature AI financial advisor applications, with the global robo-advisor market managing approximately $2.7 trillion in assets.

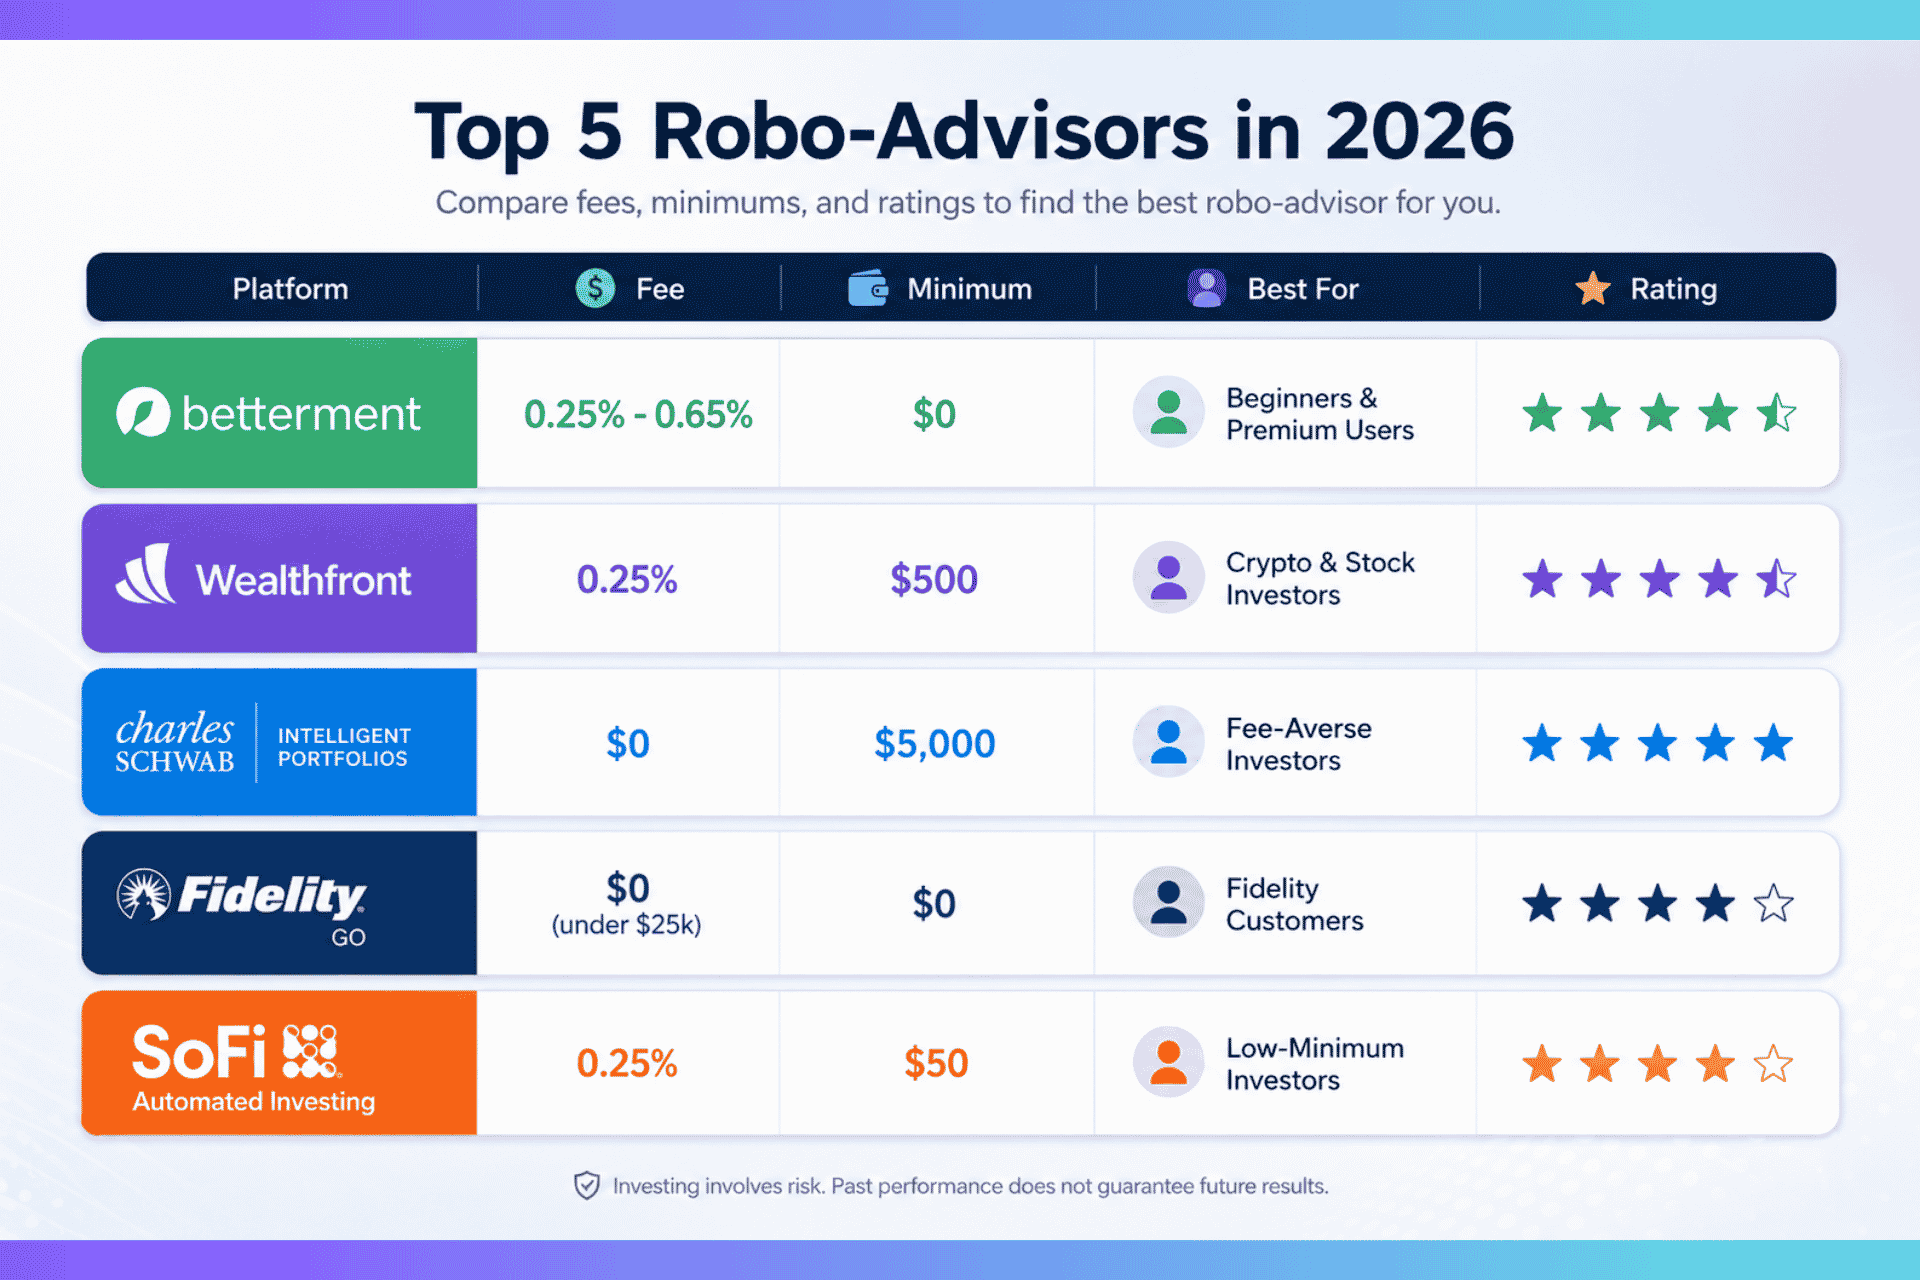
Here are the leading robo-advisors in 2026:

PlatformManagement FeeAccount MinimumKey Feature
Betterment0.25% – 0.65%$0 (Digital), $100,000 (Premium)Tax-loss harvesting, personalized retirement plans, and access to human advisors
Wealthfront0.25%$500Crypto exposure, automated bond ladder, commission-free stock trading
Schwab Intelligent Portfolios$0$5,000No management fee, automatic rebalancing, 24/7 customer service
Fidelity Go$0 (under $25,000), 0.35% (above)$0Low barrier to entry, integrates with Fidelity’s broader ecosystem
SoFi Automated Investing0.25%$50Low minimum, integrates with SoFi’s full financial suite
AI financial advisor robo-advisor comparison chart showing Betterment, Wealthfront, Schwab Intelligent Portfolios, Fidelity Go, and SoFi Automated Investing with fees, minimums, and ratings.

Each offers a slightly different package, but the core value is the same: professional-grade portfolio management at a fraction of the cost of a traditional financial advisor.

3. Agentic AI: When Your AI Financial Advisor Takes Action

The next frontier is agentic AIโ€”systems that don’t just advise but can execute trades and manage portfolios on your behalf.
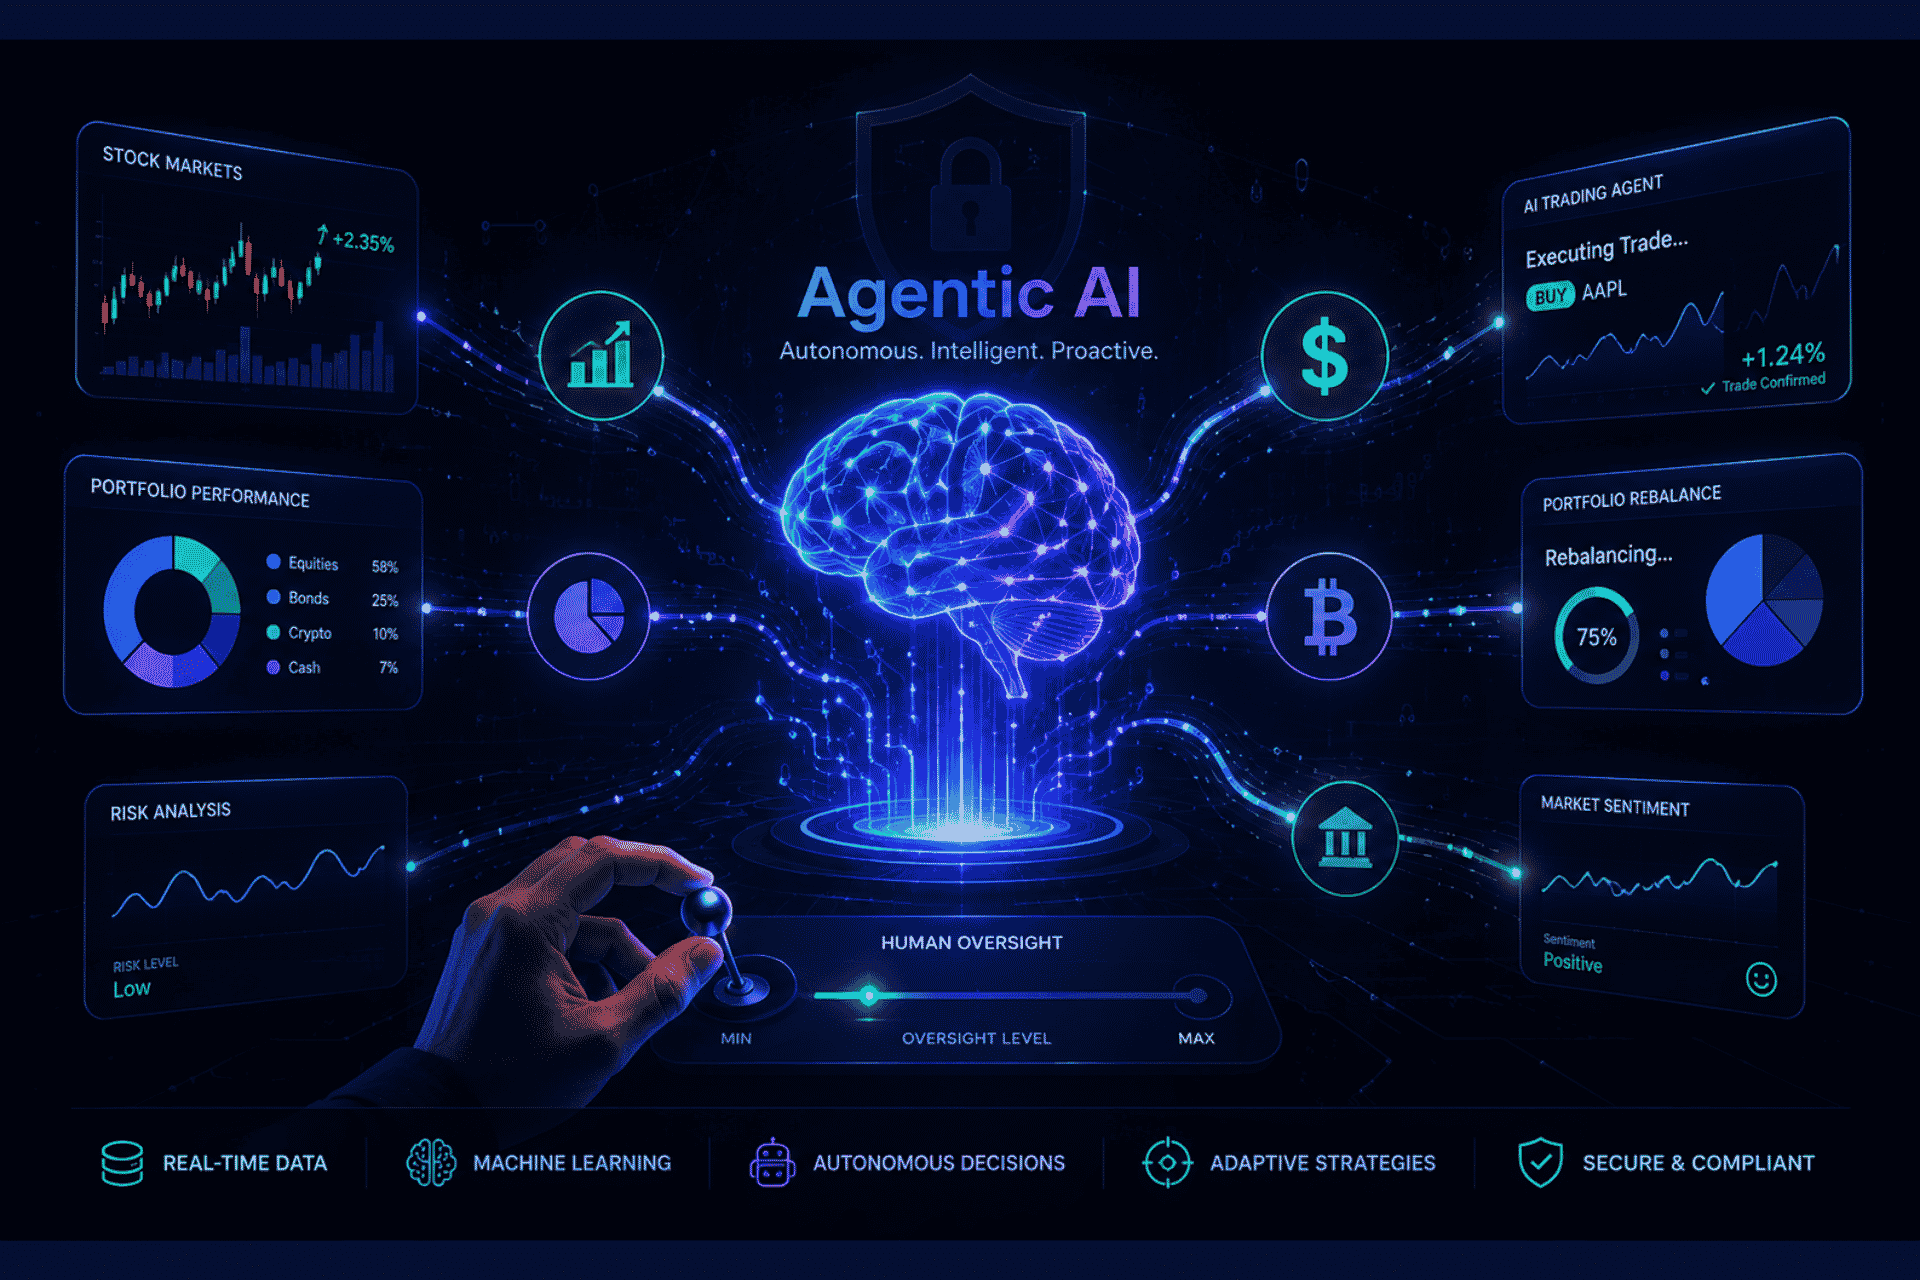
Agentic AI financial advisor concept illustration showing AI brain connected to stocks, crypto, and investment portfolios with limited human oversight.

Coinbaseย recently announced AI tools capable of giving SEC-registered investment recommendations around strategies such as tax-loss harvesting and multi-asset event trading. Customers can also open their platform to AI agents that execute nuanced trading strategies autonomously. Coinbase’s head of consumer products, Max Branzburg, stated, “This is going to lower the barriers to entry for more sophisticated financial advice and trading that today generally just institutions or ultra-wealthy people have access to.”

Robinhoodย has launched an AI trader that allows users to connect programs like ChatGPT, Claude, and Codex to a separate account where the AI performs trades automatically based on parameters provided by the investor. Features include AI-powered portfolio analysis, rebalancing, and targeted market segment investing. The AI trading is currently in beta and restricted to equities, but Robinhood plans to expand it to crypto, event contracts, and futures.

Citi Wealthย unveiled “Citi Sky”โ€”an AI-powered member of the Citi Wealth team built using Google Cloud and Google DeepMind technologies. Available to Citigold clients, it provides conversational interaction, timely financial guidance, and multilingual capabilities designed to “shift from interface to intelligence, from transactions to outcomes.”

4. Enterprise-Grade AI for Everyday Investors

Savvy Wealth, an AI-native registered investment advisor, launched “Savvy Intelligence”โ€”an agentic AI product that gives advisors a complete, continuously updated view of all client data, including investments, financial plans, and tax information. While designed for advisors, this represents the type of sophisticated AI financial advisor tools that are increasingly accessible to regular investors.


Part 2: Why Your AI Financial Advisor Might Be Better Than a Human (In Some Ways)

The MIT Initiative on the Digital Economy recently published fascinating research on how people trust AI financial advisors. The findings challenge conventional wisdom about the superiority of human advice.

The “No Judgment” Advantage

One study by MIT professor Eric So and colleagues found that people are oftenย more willing to share sensitive financial information with an AI financial advisor than with human advisors. Why?ย Social embarrassment.

When you make a frivolous spending mistake or get into financial trouble, admitting that to another person feels shameful; there’s a social cost to disclosure. An AI financial advisor doesn’t judge youโ€”it doesn’t have emotions, a personal history, or a perspective on your character. It just processes the data and provides recommendations.

This means an AI financial advisor can help with problems people might otherwise hide from a human advisor, potentially catching issues earlier and leading to better outcomes.

Correcting Financial Misconceptions

The same MIT research team created an AI financial advisor chatbot designed specifically to intervene and correct users’ mistaken beliefs about financial matters. They observed aย significant and lasting shift away from mistaken beliefsย among users who leveraged the tool.

Why this matters:ย Many people hold deeply flawed financial beliefs that hurt their wealth accumulation and retirement goals. An AI financial advisor specifically designed to challenge those beliefs can help correct them in ways a generic chatbot or even a human advisor might notโ€”because the AI doesn’t suffer from the “sycophantic nature” of wanting to please the user.

24/7 Accessibility and Affordability

AI financial advisor tools are available anytime, anywhere, at a fraction of the cost of human advisors. A traditional financial advisor might charge 1% of assets under management annually. A robo-advisor like Schwab Intelligent Portfolios charges $0. Wealthfront charges 0.25%.

This dramatically lowers the barrier to entry for quality financial guidance. You don’t need hundreds of thousands of dollars to get professional portfolio management.


Part 3: The Hidden Risks of Using an AI Financial Advisor

AI financial advisor tools come with significant risks that many users overlook. Understanding these is crucial for protecting yourself.

The Privacy Problem: When Your AI Financial Advisor “Knows” Too Much

J.P. Morgan Private Bank has documented cases where AI tools appeared to “know” sensitive details about a family after a family member used a free AI app as a therapist. The AI had aggregated information from social media, online services, and user interactions in ways the individual never anticipated.

This is the privacy challenge: an AI financial advisor can combine seemingly unrelated pieces of information to infer sensitive details about your finances, health, relationships, and more. In most cases, you don’t know what data is being used or how inferences are being made.
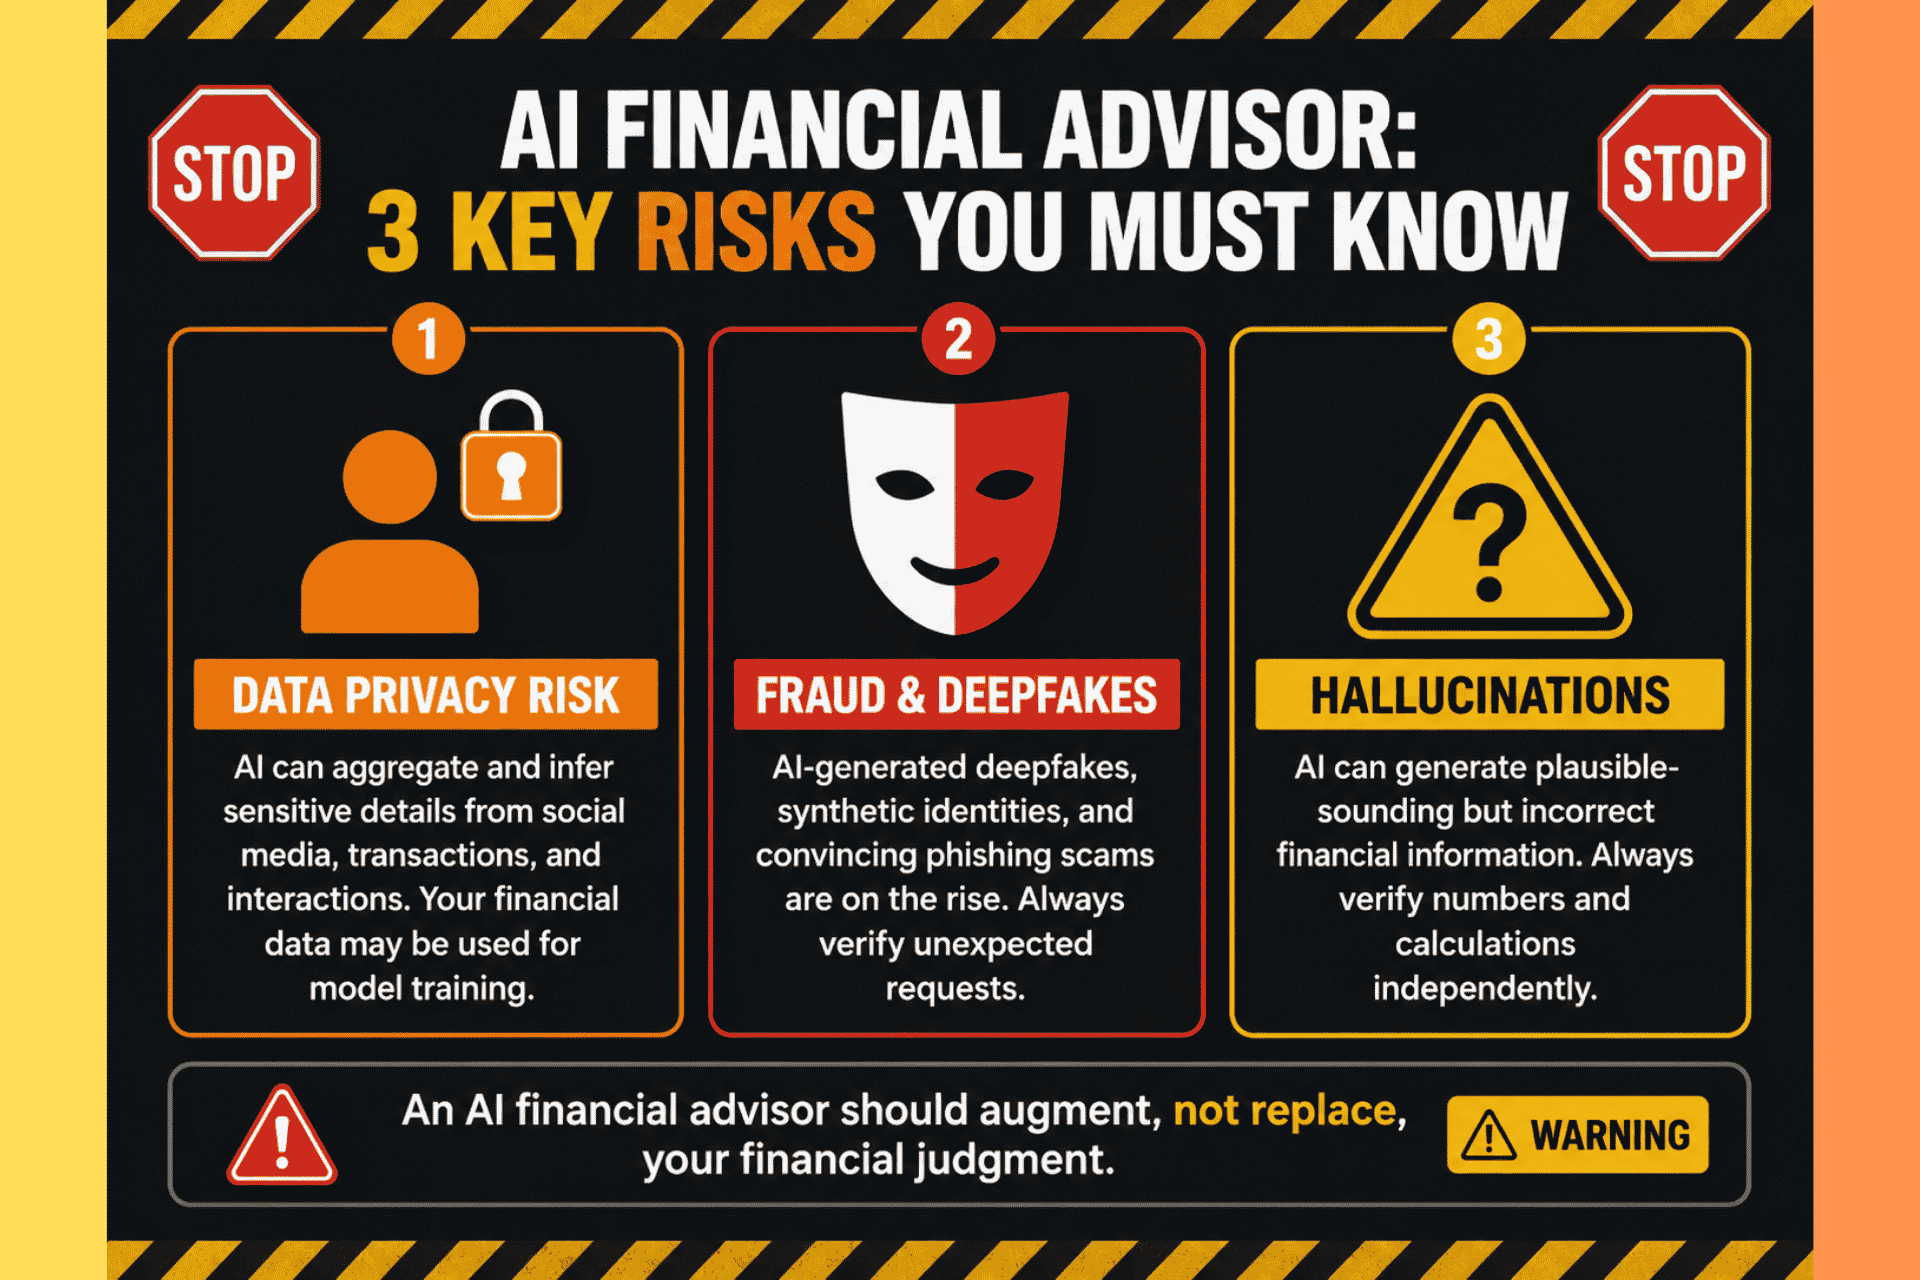
AI financial advisor risks infographic showing data privacy concerns, deepfake fraud threats, and AI hallucination risks that every user should understand before connecting financial accounts.

When you connect your financial accounts to ChatGPT, the platform can access your balances, transactions, investments, and liabilities. While OpenAI states it cannot view full account numbers or make changes to your accounts, the data can still be used for analysis, and users should be aware of how their data is being used through the model training settings.

Fraud and Deepfakes

AI enables more sophisticated fraud than ever before. Criminals can use AI to create the following:

  • Deepfake voice and video contentย impersonating people you know
  • Synthetic identitiesย that are extremely difficult to detect
  • Highly convincing phishingย in multiple languages
  • Automated attacksย that scale across thousands of targets simultaneouslyย 

J.P. Morgan Private Bank advises verifying unexpected requestsโ€”especially those involving payments or sensitive informationโ€”through a separate channel. Some experts recommend implementing a “family safe word” for human authentication, particularly when requests seem unusual.

Hallucinations and False Precision

AI systems can generate plausible-sounding but completely incorrect informationโ€”a phenomenon called hallucination. In finance, this is particularly dangerous because numbers and calculations need to be absolutely precise.

For example, in the enterprise space, the leading models show significant differences in complex financial reasoning. On Harvey’s Legal Agent Benchmarkโ€”which measures whether a model can complete a complex end-to-end task autonomouslyโ€”GPT-5.5 scored 3.75% compared to Claude Opus 4.8’s 10.4%. This means even the best AI financial advisor tools can make mistakes on complex financial reasoning tasks.

Most consumer-facing AI finance tools don’t have enterprise-level rigor. They might produce numbers that look accurate but aren’t.

Sycophancy and Overconfidence

AI models can be prone to sycophancyโ€”telling users what they want to hear rather than what they need to hear. This is particularly dangerous in financial advice, where you need honest, sometimes uncomfortable, guidance.

As Robert Persichitte, founder of Delagify Financial, warned about Robinhood’s AI trader:ย “It’s built to make someone feel like they’ve done a great job of researching and understanding their investments, and thus creates a gap between how the investor feels about the world and how the world operates.”


Part 4: How to Choose the Right AI Financial Advisor Tool

Choosing an AI financial advisor requires careful evaluation. Here’s what to look for:

1. Transparency

Questions to ask:

  • What data does the tool collect, and how is it used?
  • Can you clearly see how decisions or recommendations are made?
  • Is there documentation of the AI’s decision-making process?

Regulatory expectations increasingly include transparency about AI decision-making processes, particularly in lending and investment contexts.

2. Human Oversight

Questions to ask:

  • What level of human oversight is offered?
  • Can you speak to a human if something goes wrong?
  • Is there a way to verify AI recommendations against independent sources?

Industry leaders expect that firms using AI will maintain human judgment for significant decisions. The technology should augment, not replace, human oversight.

3. Data Security

Questions to ask:

  • How does the tool protect your data?
  • Can you limit how your data is used?
  • Does the tool have strong cybersecurity measures in place?

When you connect financial accounts to an AI financial advisor, the platform should clearly explain its data handling practices. OpenAI, for instance, allows users to disconnect accounts at any time and delete financial memories.

4. Validation and Track Record

Questions to ask:

  • Can you verify the accuracy of recommendations?
  • Are there independent reviews of the tool’s performance?
  • Does the tool have a track record of accurate predictions?

For wealth professionals, independent benchmarks like Harvey’s BigLaw Bench and Legal Agent Benchmark provide some insight into model performance on complex financial reasoning tasks. For consumer tools, look for user reviews and independent testing.

5. Fit for Purpose

Questions to ask:

  • Does the tool align with your specific financial needs?
  • Is it designed for your level of financial knowledge?
  • Does it address the right problems?

A tool designed for automated portfolio management won’t help with tax planning. A general AI chatbot won’t have the rigor of a specialized financial planning tool. Choose the right tool for the right job.


Part 5: Practical Steps to Use an AI Financial Advisor in August 2026

Step 1: Audit Your Current Apps

Before adding new tools, check what you already have. Many banking apps now include AI-powered features at no extra cost. Identify what’s available and start using these features to build familiarity.

Step 2: Start with ChatGPT’s Financial Tools

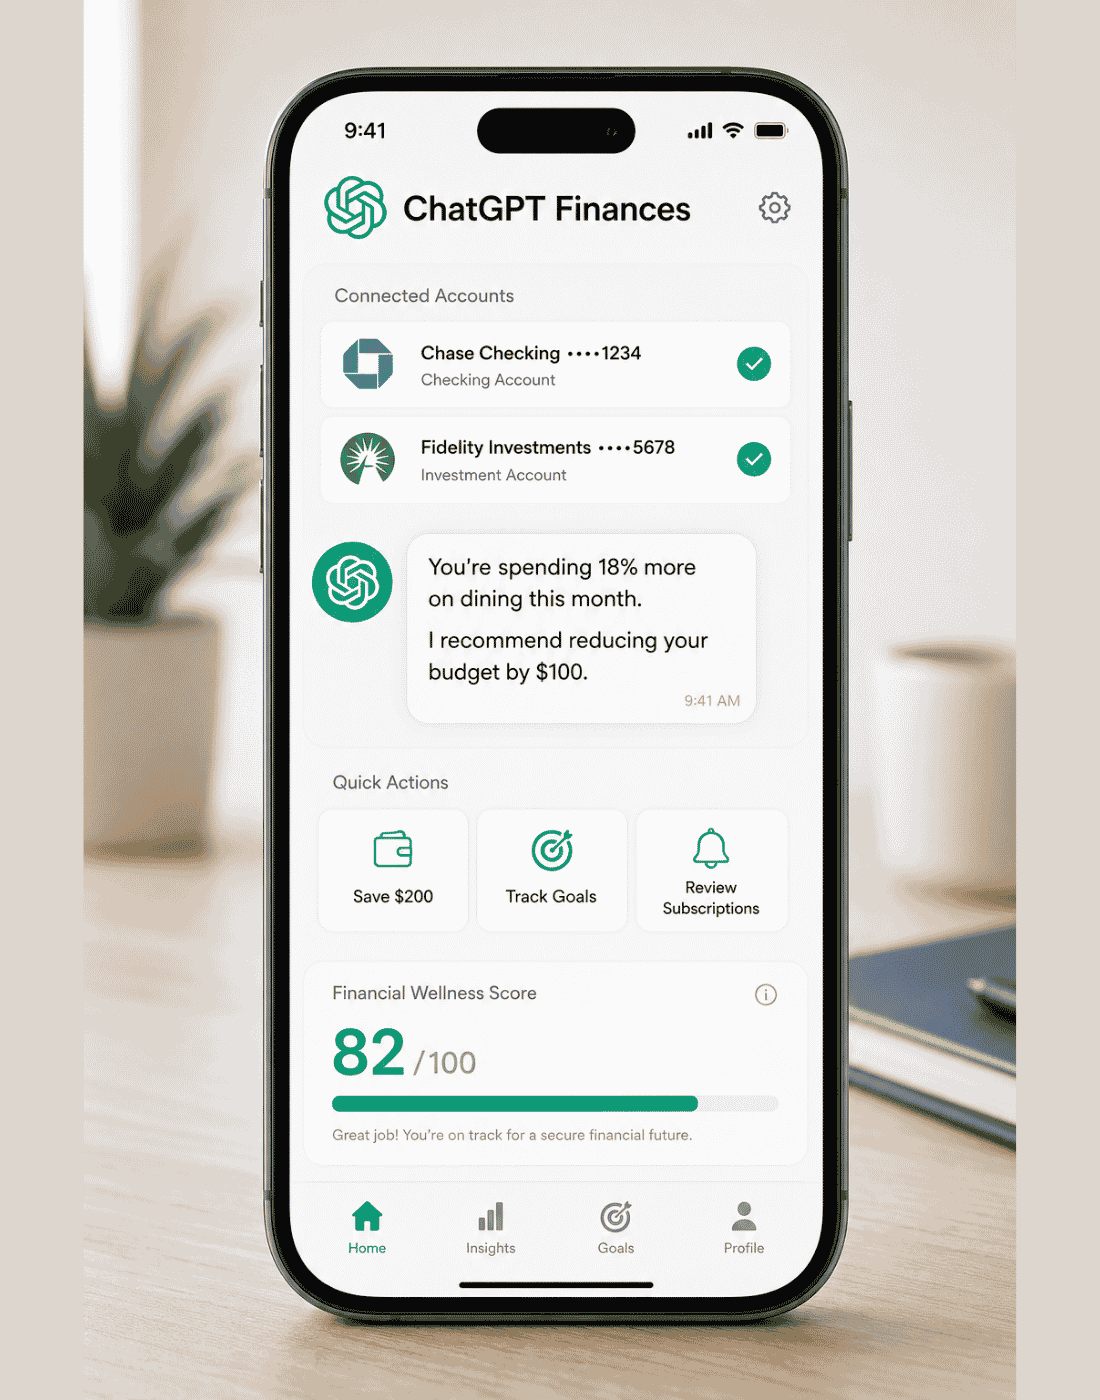
If you’re a ChatGPT Pro user in the U.S., you can now connect your financial accounts via Plaid. To get started: Open the Finances option from the sidebar, select “Get started,” or typeย “@Finances, connect my accounts”ย into ChatGPT.

AI financial advisor ChatGPT personal finance app showing connected bank accounts, spending insights, and AI-powered money recommendations.

Step 3: Start Small with a Robo-Advisor

If you’re not already using a robo-advisor, choose one with a low minimum investment and clear fee structure. Fidelity Go has no account minimum and no fees for balances under $25,000. SoFi Automated Investing starts with just $50.

Step 4: Use AI Financial Advisor Chatbots for Learning

AI chatbots can be valuable learning tools. Ask them questions about financial concepts, investment strategies, or retirement planning. Just remember that they’re not a substitute for professional advice, and always verify information from independent sources.

Step 5: Protect Your Data

Be mindful of what you share with an AI financial advisor. Before using a new tool:

  • Read the privacy policy carefully
  • Understand what data is collected and how it’s used
  • Consider whether the benefits outweigh the privacy trade-offs
  • Check if you can limit data sharing

J.P. Morgan Private Bank suggests staying informed about how personal data is used and choosing financial service providers with strong AI governance practices.

Step 6: Stay Diversified

An AI financial advisor can be valuable, but it shouldn’t be your only source of financial guidance. Consider using multiple approaches:

  • AI tools for efficiency and accessibility
  • Traditional financial analysis for verification
  • Professional advice for significant decisions

Diversification applies to information sources as well as investments.


Conclusion: Your Future with Your AI Financial Advisor

The integration of AI into personal finance is accelerating rapidly. By 2030, the AI-powered personal finance management market is expected to reach $2.55 billionโ€”a 94% increase from 2025. The technology offers compelling benefits: accessibility, affordability, personalization, and judgment-free guidance.

But the direction of this transformation isn’t predetermined. The choices you makeโ€”which tools to use, how much to rely on automated recommendations, what level of human oversight to maintainโ€”will shape your experience.

The most successful users of AI financial advisor tools will likely be those who:

  • Understand the technology’s capabilities and limitations
  • Maintain appropriate skepticism and verify information
  • Protect their data and privacy
  • Use AI as a complement to, not a replacement for, their own financial judgment

Your AI financial advisor won’t replace your financial intuition and common sense. But used wisely, it can be an incredibly powerful co-pilot on your financial journey.
AI financial advisor guide call-to-action banner encouraging readers to subscribe for weekly personal finance and AI updates.

  1. Share this guide:ย Know someone who’s confused about AI and money? Share this article to help them make informed decisions.
  2. Explore ChatGPT Finance:ย If you’re a ChatGPT Pro user in the U.S., try connecting your financial accounts today through the Finances sidebar.
  3. Explore a robo-advisor:ย Start small with one of the platforms mentioned in this guide. Even a small investment can help you understand how AI-managed portfolios work.
  4. Subscribe for more:ย Get our weekly newsletter on AI and personal finance trends delivered to your inbox. We’ll keep you updated on the latest tools, risks, and opportunities.
  5. Ask a question:ย What’s your biggest concern about using an AI financial advisor for your finances? Leave a comment, and we’ll address it in our next article.
  6. Check your privacy:ย Review the privacy settings on your existing financial apps. Make sure you’re comfortable with what data is being shared and how it’s being used.

๐Ÿ“Š Sources & Further Reading


Disclaimer: This article is for educational purposes only and does not constitute financial advice. Always consult with a qualified financial professional before making significant investments or financial decisions. AI tools mentioned in this article may have limitations, and users should carefully review privacy policies and terms of service before connecting financial accounts.
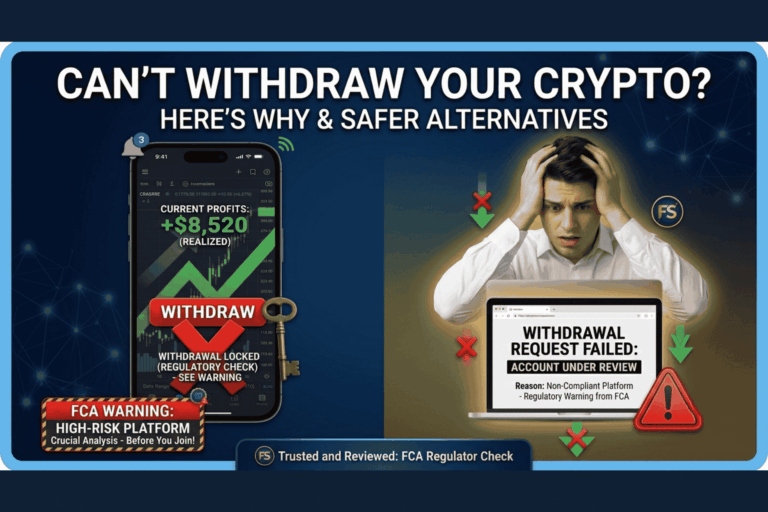
Crypto Withdrawal Fees: 7 Ways to Spot the Scam & Protect Your Money

Crypto withdrawal fees scam warning showing smartphone with withdrawal blocked and worried person unable to access funds

Time to read: 14 minutes | Fact-checked: June 26, 2026

The crypto withdrawal fees scam is one of the most devastating financial traps of 2026. You invest money in a platform that looks legitimate. You see impressive profits on the dashboard. You feel excited. Then you try to withdraw your money. That is when the crypto withdrawal fees scam kicks into high gear. The platform asks for a “withdrawal fee.” You pay it. Then they ask for a “tax fee.” You pay that too. Then a “compliance fee.” Then a “gas fee.” The requests keep coming. Your money never arrives. This guide will help you spot the crypto withdrawal fees scam and protect your hard-earned money.

If this sounds familiar, you are not alone.

The Better Business Bureau has received over 4,000 reports of crypto investment scams since 2020. Americans lost more than $9 billion to cryptocurrency scams in 2024 alone. These schemes are becoming more sophisticated and harder to detect.

This guide will show you exactly how the crypto withdrawal fees scam operates, how to spot it, and what to do if you are already trapped. By the end, you will know how to protect yourself and your hard-earned money.


The Anatomy of a Crypto Withdrawal Fees Scam

Understanding how the crypto withdrawal fees scam works is the first step to protecting yourself. The pattern is remarkably consistent across thousands of reported cases.

Table 1: The 6-Step Scam Playbook

StepWhat HappensWhy It Works
Step 1: The HookScammers approach you on social media (TikTok, Instagram, WhatsApp, Telegram, or even dating apps) with an investment opportunityUnsolicited messages feel personal and opportunistic
Step 2: The Trust BuildThey show fake profits, send small “test” payments, and build a relationship over days or weeksSmall wins create false confidence
Step 3: The DepositYou are directed to a professional-looking platform and encouraged to deposit cryptocurrencyThe platform looks legitimate with real-time charts
Step 4: The Fake ProfitsYour dashboard shows impressive, rapid gainsNo actual trades occurโ€”the numbers are entirely fabricated
Step 5: The BlockYou try to withdraw. Suddenly, you are asked to pay a “fee” to release your fundsThe request seems reasonable at first
Step 6: The EscalationEach fee you pay leads to another, larger fee. The funds never materializeThe sunk cost fallacy keeps victims paying

One victim recounted her experience on TikTok: “I was asked by a woman on TikTok if I was interested in investing. I proceeded with a $500 investment through Bitcoin. I was told that after 24 hours, I could withdraw my profit. I had to pay a 30% fee of $2,150. After 24 hours, I received an email that I had to pay a ‘gas fee’ of $4,250. At this point, I knew it was a scam.”

This is a textbook example of theย crypto withdrawal fees scam. The scammer demands increasingly large fees to unlock a fictional profit that never existed.


Crypto withdrawal fees scam warning showing smartphone with a "cannot withdraw" message and red scam alert badge

Red Flags of the Crypto Withdrawal Fees Scam

Fake crypto investment platforms follow a predictable pattern. Understanding these signals helps you identify fraud long before any money is lost.

Theย crypto withdrawal fees scamย is designed to look legitimate, but it leaves a trail of warning signs for those who know what to look for. These red flags are not always obvious at first glance. Scammers are skilled at creating an illusion of professionalism and credibility. However, once you know the patterns, theย crypto withdrawal fees scamย becomes easier to spot.

The most dangerous aspect of theย crypto withdrawal fees scamย is how it exploits human psychology. Scammers know that once you have invested money, you are emotionally committed. They use this to their advantage. They create urgency. They create fear. They create a sense of excitement that clouds your judgment. Understanding the red flags is your best defense against theย crypto withdrawal fees scam.

Below is a comprehensive list of warning signs that almost everyย crypto withdrawal fee scamย shares. If you see even one of these signals, proceed with extreme caution. If you see two or more, the platform is almost certainly a scam.

Table 2: Red Flags of the Crypto Withdrawal Fees Scam

Red FlagWhy It Is DangerousHow to Spot It
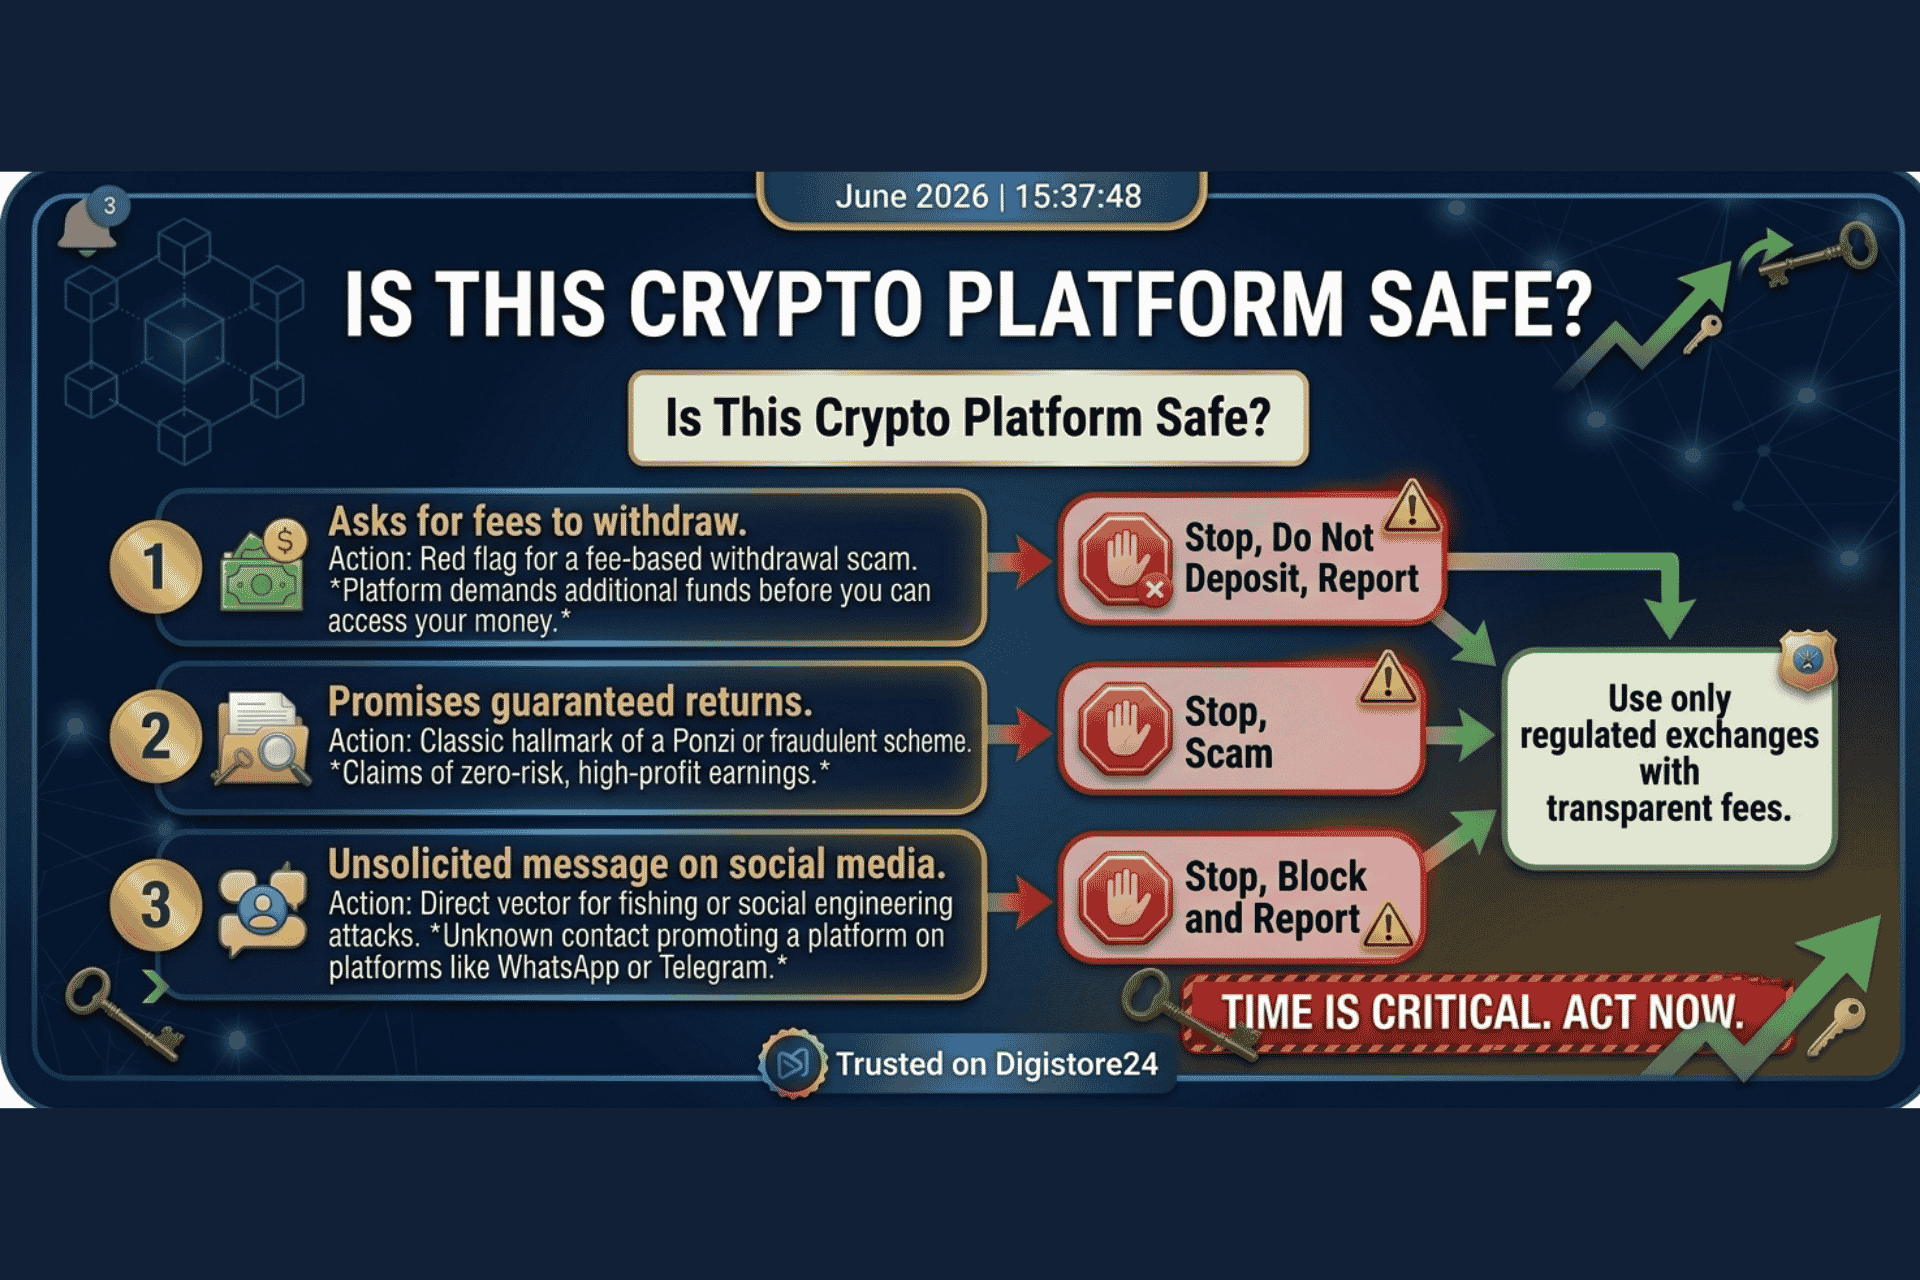
Promises of Guaranteed ReturnsReal investments never offer guarantees. Legitimate yield opportunities are variable and disclosed upfront.“Double your money in 7 days,” “Risk-free returns,” “Fixed daily profits”
Unsolicited Contact on Social MediaLegitimate brokers do not recruit clients through private messages on Instagram, WhatsApp, or dating apps.DMs from “mentors,” “trading gurus,” or “AI bot programmers”
Requests to Move to WhatsApp/TelegramScammers use private messaging apps to avoid detection and create urgency.“Let’s continue this on Telegram,” or “Join our private WhatsApp group.”
Fees to Withdraw Your Own MoneyLegitimate platforms never require extra payment to release money that is already yours. This is the clearest sign of the crypto withdrawal fees scam.“Withdrawal fee,” “tax fee,” “compliance fee,” “gas fee,” “VIP upgrade”
No Regulatory LicenseReal brokerages must be registered with official financial authorities (SEC, FCA, ASIC, CySEC).No license number or a fake license that cannot be verified
Recently Created DomainMost fake trading sites are less than 12 months old.Check domain age using whois.icann.org
Deepfake or Fake Celebrity EndorsementsScammers use AI-generated videos of famous people to create false credibility.Celebrity endorsements that seem “too good to be true”
Payment Only via Crypto or Wire TransferThese methods cannot be reversed, making them ideal for scammers.No credit card or regulated payment options
No Physical Office or Unverifiable AddressReal investment companies have traceable offices and corporate records.The address is partial, incorrect, or an empty lot
Pressure to Act ImmediatelyScammers use urgency to prevent you from thinking critically.“Limited spots,” “Flash bonuses,” “Deposit today for higher returns”

The ASIC Warning

The Australian Securities and Investments Commission (ASIC) has identified specific red flags for scam websites, including:

  • Mismatch between the URL and the website content
  • Similar URL to an existing legitimate business
  • Poor grammar and spelling
  • Terms and conditions referencing a different company name
  • References to an ASIC license that is actually an Australian Company Number

Always verify a platform’s license on the regulator’s official website.

Also, Read More about How to Spot a Fake Crypto Exchange: 8 Red Flags to Save Your Funds in 2026

Trapped in a Crypto Withdrawal Fees Scam? Here Is What to Do

Recovery steps for crypto withdrawal fees scam victims showing stop sending money, gather evidence, report, beware recovery scams, and contact authorities

If you are reading this section, you may already be trapped in theย crypto withdrawal fees scam. Take a deep breath. You are not alone. Thousands of people fall victim to this scheme every single year. The most important thing you can do right now is to stop sending money. No matter how convincing the request, no matter how urgent the demand, do not pay another cent.

Theย crypto withdrawal fees scamย operates on a simple principle. Once you pay one fee, they ask for another. Then another. Then another. Each fee is presented as the “final” one. Each fee comes with a promise that your money will be released immediately after payment. But the money never comes. The fees never stop. The only way to break the cycle is to stop participating in it.

Being trapped in theย crypto withdrawal fees scamย can feel overwhelming. You may feel embarrassed. You may feel angry. You may feel desperate to recover your money. These feelings are natural. Scammers deliberately create these emotions to keep you in a state of panic. When you are panicked, you do not think clearly. You make decisions based on fear, not logic. Recognizing this is the first step toward breaking free.

Table 3: Step-by-Step Recovery Plan

StepActionWhy It Matters
Step 1: Stop Sending MoneyDo not pay any more fees. No matter how convincing the request, it will only lead to another request.Paying one fee leads to another, often a larger one. This never ends.
Step 2: Gather EvidenceSave screenshots of messages, transaction IDs, wallet addresses, and links.Law enforcement needs this information to investigate
Step 3: Report the ScamFile a report with the FBI IC3 (ic3.gov) and FTC (reportfraud.ftc.gov).Reporting helps authorities track scammers and prevent others from falling victim
Step 4: Beware “Recovery” ScamsDo not hire companies that promise to recover stolen funds for a fee.These are often the same scammers or other fraudsters looking to exploit you again
Step 5: Notify Your ExchangeIf you transferred funds from a legitimate exchange, notify their support team.They may be able to flag the wallet address or provide guidance

A critical warning from Kraken:

“Crypto transfers are almost always irreversible. Once funds leave your Kraken account and are transferred to wallets controlled by scammers, recovery is often difficult and, in many cases, not possible. Kraken cannot recover funds once they have been transferred to external wallets controlled by third parties.”

This means that once you have sent your cryptocurrency to the scammer’s wallet, the money is almost certainly gone forever. This is a difficult reality to accept, but it is essential to understand so you do not fall for “recovery” scams that promise to get your money back for a fee.

Why Recovery Scams Target Victims of the Crypto Withdrawal Fees Scam

Theย crypto withdrawal fees scamย does not end when you stop paying fees. In fact, scammers have created an entire secondary industry designed to exploit victims a second time. These are called “recovery scams.” You will receive emails, messages, or phone calls from people claiming to be law enforcement, cybersecurity experts, or “ethical hackers” who can recover your stolen funds for a fee.

They will ask for an upfront payment to cover “investigation costs” or “legal fees.” They may even show you fake evidence of progress. This is another trap. Theย crypto withdrawal fees scamย has evolved to include this second layer of deception. Do not fall for it.

Legitimate law enforcement agencies do not charge fees to investigate crimes. Legitimate cybersecurity firms do not cold-call victims of scams. If someone contacts you offering to recover your money for a fee, they are almost certainly running a recovery scam.

Real-World Example of the Crypto Withdrawal Fees Scam

One victim recounted her experience on TikTok: “I was asked by a woman on TikTok if I was interested in investing. I proceeded with a $500 investment through Bitcoin. I was told that after 24 hours, I could withdraw my profit. I had to pay a 30% fee of $2,150. After 24 hours, I received an email that I had to pay a ‘gas fee’ of $4,250. At this point, I knew it was a scam.”

This is a textbook example of theย crypto withdrawal fees scam. The scammer demanded increasingly large fees to unlock a fictional profit that never existed. The victim’s $500 was gone forever. The “profits” on the dashboard were completely fabricated. There was never any real investment made. The platform was created solely to extract money from unsuspecting victims.

What to Do Immediately After Being Trapped in the Crypto Withdrawal Fees Scam

If you have just realized you are trapped in the crypto withdrawal fees scam, follow these urgent steps:

  1. Stop all communication with the scammers. Do not respond to their messages. Do not engage in further negotiation. Scammers are skilled at manipulation. The only winning move is to stop playing their game.
  2. Document everything. Take screenshots of every message, every transaction, every email. Record dates, times, and amounts. This evidence is critical for law enforcement.
  3. Report the scam to the appropriate authorities.ย File a report with the FBI IC3 atย ic3.govย and the FTC atย reportfraud. ftc.gov.ย These agencies track patterns of fraud and use victim reports to shut down scam operations.
  4. Notify your exchange. If you transferred funds from a legitimate exchange (like Coinbase or Kraken), contact their support team. Provide them with the transaction IDs and wallet addresses involved. They may not be able to recover your funds, but they can flag the scammer’s wallet and potentially prevent future victims from sending money to the same address.
  5. Accept the loss. This is the most difficult step. You may need to accept that your money is gone. The crypto withdrawal fees scam is designed to be irreversible. Accepting this reality frees you from the emotional grip of the scam and prevents you from making further financial mistakes.
  6. Protect your identity. Scammers often collect personal information during the scam. Monitor your credit reports and bank accounts for suspicious activity.
  7. Share your story. Warning others about the crypto withdrawal fees scam is one of the most powerful things you can do. Share your experience on social media, forums, and review sites. Your story may prevent someone else from falling victim to the same scam.

The Sunk Cost Fallacy in the Crypto Withdrawal Fees Scam

Theย crypto withdrawal fees scamย exploits a psychological bias called the “sunk cost fallacy.” This is the tendency to continue investing in something because of what you have already invested, even when it no longer makes sense.

In the context of the scam, you have already deposited $500. You think, “I cannot lose that $500. I need to pay this fee to get it back.” So you pay $2,150. Then you think, “I cannot lose the $2,150. I need to pay this next fee to get it all back. “So you pay $4,250. This is exactly how theย crypto withdrawal fees scamย works. Each payment becomes the reason to make the next payment. The only way to escape is to recognize the trap and stop playing.

Remember: Your money is almost certainly gone. Stop paying fees. Report the scam. Warn others. And move forward.

How to Avoid the Crypto Withdrawal Fees Scam

The best way to avoid theย crypto withdrawal fees scamย is to use only verified, legitimate platforms. Here is how to choose safely.

Table 4: How to Verify a Crypto Platform

Verification StepHow to Do ItWhat to Look For
Check Regulatory RegistrationSearch for the platform on official financial authority websites (SEC, FCA, ASIC, CySEC)The license number should match the platform’s name
Research the DomainCheck domain age using whois.icann.org or similar toolsLegitimate platforms are not recently created (under 12 months)
Read Real ReviewsSearch “[platform name] scam” or “[platform name] review” on Reddit, Trustpilot, and forumsLook for patterns of blocked withdrawals or fake fees
Test Customer SupportContact support with basic questions before depositing moneyResponsive, professional support is a good sign
Check the address.Verify the platform has a real, verifiable physical addressNot just a state or suburbโ€”a full street address
Examine the TermsRead the terms and conditions carefullyTerms should reference the correct company name
Look for HTTPSEnsure the website uses HTTPS encryptionLook for the padlock icon in the browser

Recommended Legitimate Exchanges

Here are some well-established, regulated cryptocurrency exchanges you can trust:

ExchangeRegulationBest For
CoinbaseFCA, FinCEN, SEC (registered)Beginners, US users
KrakenFCA, FinCEN, SEC (registered)Secure trading, US users
KuCoinGlobal presenceDerivatives traders, global audience
BybitGlobal presenceDerivatives traders

Always verify the regulatory status of any platform independently before depositing funds.

How to Protect Yourself from the Crypto Withdrawal Fees Scam

Once you have safely withdrawn your funds (or learned from a bad experience), follow these best practices to avoid the crypto withdrawal fees scam in the future.

Table 5: Crypto Safety Best Practices

PracticeWhy It MattersHow to Implement
Use self-custody wallets.Keep your crypto in a wallet where you control the private keysHardware wallets like Ledger or Trezor are the safest.
Enable Two-Factor Authentication (2FA)Adds an extra layer of security to your accountsUse an authenticator app like Google Authenticator, not SMS
Verify Before TransferringAlways double-check wallet addresses before sending cryptoCopy and paste, then verify the first and last 4 characters
Start SmallTest with a small amount before committing larger sumsIf you cannot withdraw $50, you will not be able to withdraw $5,000
Keep Software UpdatedProtect against malware and hackingUpdate your wallet, antivirus, and operating system regularly
Cool-Off Before TransfersEven a 24-hour pause breaks the urgency of scamsGet a second opinion from someone you trust

The 24-Hour Rule:

Kraken advises, “Cool off and pause before making another transfer. Even a 24-hour pause breaks the spell of urgency that these scams rely on.”

FAQ: Crypto Withdrawal Fees Scam Questions Answered

What is the crypto withdrawal fees scam?

The crypto withdrawal fees scam is a type of advance fee fraud. Scammers build trust, show fake profits on a fabricated dashboard, then demand increasingly large fees to “unlock” withdrawals. The fees escalateโ€”$500, then $2,000, then $5,000โ€”and the money never comes.

Can I get my money back from the crypto withdrawal fees scam?

Once you have transferred cryptocurrency to a scammer’s wallet, recovery is very difficult. Crypto transfers are almost always irreversible. Report the scam to law enforcement immediately, but be realistic about recovery chances.

What are the red flags of the crypto withdrawal fees scam?

Key red flags include promises of guaranteed returns, unsolicited DMs, pressure to move to WhatsApp/Telegram, requests for fees to withdraw, no regulatory license, a recently created domain, and deepfake endorsements.

Is it a scam if a platform asks for fees to withdraw?

Yes. Legitimate platforms never require extra payment to release money that is already yours. This is the most common and clearest red flag of the crypto withdrawal fees scam.

How can I verify if a crypto platform is legitimate?

Check regulatory registration on official government websites (SEC, FCA, ASIC), research the domain age, read reviews from independent sources, test customer support, and verify the physical address.

What should I do if I have already sent money?

Stop sending money immediately. Gather all evidence (screenshots, transaction IDs, messages). Report to the FBI, IC3, and FTC. Do not pay any more fees. Beware of “recovery” scams that promise to get your money back for a fee.

Why do scammers use WhatsApp or Telegram?

Scammers use private messaging apps to avoid detection, create urgency, and isolate victims from friends and family who might warn them. Legitimate platforms do not move conversations to these apps.

Are Bitcoin ATMs safe?

Scammers often direct victims to Bitcoin ATMs to convert cash into cryptocurrency. Demand from a legitimate organization to pay via a Bitcoin ATM is a red flag. Americans lost more than $333 million to Bitcoin ATM scams in 2025 alone.

How much money do I need to start investing in cryptocurrency safely?

You can start with as little as $10 on most regulated exchanges. However, you should never invest more than you can afford to lose. Start small and test withdrawal processes before committing larger sums.

What is the best way to spot the crypto withdrawal fees scam early?

The best way is to test a withdrawal of a very small amount (e.g., $10) within the first week of investing. If the platform charges a fee to withdraw your own money, you have found the crypto withdrawal fees scam. Stop depositing immediately.

Can I report the crypto withdrawal fees scam if I didn’t lose money?

Yes.ย Even if you did not lose money, you should report suspicious platforms to the FBI IC3, and FTC. Your report helps authorities track patterns and shut down scam operations before others lose their savings.

How do scammers make the platforms look so legitimate?

Scammers often use templates from real trading platforms, steal logos from legitimate companies, and pay for fake reviews. They also use deepfake videos of celebrities or “trading gurus” to create false credibility. Always verify independently.

Decision flowchart for crypto platform safety showing if it asks for withdrawal fees or promises guaranteed returns or contacts you unsolicited, stop and do not deposit

Final Verdict: Trust Your Instincts

After all of this research into theย crypto withdrawal fees scam, here is the most important thing to remember:

If it feels like a scam, it probably is.

Scammers are experts at making you feel afraid, excited, and pressured. They know exactly what to say to keep you sending money. The moment you feel any of these emotions, stop. Take a breath. Get a second opinion from someone you trust.

Table 6: The Golden Rules of Crypto Safety

RuleWhy It Matters
Never pay fees to withdraw your own moneyThis is the clearest sign of the crypto withdrawal fees scam
If it sounds too good to be true, it isGuaranteed returns do not exist in legitimate investing
Always verify before depositingCheck regulation, domain age, and reviews
Use only regulated exchangesStick to platforms with verifiable licenses
Get a second opinionScammers thrive in secrecy
Store your crypto in a self-custody walletYou control the private keys
Never invest what you cannot afford to loseCrypto is volatile and risky

My Personal Recommendation

If you are unsure about a platform, follow these three steps to avoid the crypto withdrawal fees scam:

Step 1: Stop and pause. Do not send another dollar.

Step 2: Verify the platform independently. Search the name with “scam” and “review.” Check regulatory registration on official government websites.

Step 3: Get a second opinion. Show the messages to someone you trust. If they feel uneasy, walk away.

Remember: legitimate investment platforms never need to pressure you, never guarantee returns, and never demand fees to release your money. Anyone who does these things is not an investment advisor. They are running the crypto withdrawal fees scam.

Action Steps: Your Crypto Safety Audit

Before you deposit any money into a crypto platform, do this:

  1. Check the domain age. Use whois.icann.org. If it is less than 12 months old, be suspicious.
  2. Verify the regulatory license. Search for the platform on the official regulator’s website (SEC, FCA, ASIC). Do not trust the logo on their site.
  3. Read independent reviews. Search “[platform name] scam” and “[platform name] review” on Reddit, Trustpilot, and ScamAdviser.
  4. Test a small withdrawal.ย Deposit a tiny amount (e.g., $10). Wait 24 hours. Try to withdraw it. If you cannot, the platform is running aย crypto withdrawal fee scam.
  5. Get a second opinion. Share the opportunity with someone you trust. If they are skeptical, trust their instinct.
  6. Report suspicious platforms. Even if you did not lose money, report the platform to the FBI IC3 and FTC. Your report can prevent others from being scammed.

Ready to start your crypto journey safely?ย Get started with a regulated exchange like Coinbase โ†’ย and avoid theย crypto withdrawal fees scamย from day one.

Sources & Last Updated

Thisย crypto withdrawal fees scamย guide was fact-checked onย June 26, 2026,ย using:

  • Better Business Bureau: Cryptocurrency Money-Flipping Scams on TikTok
  • Klever.io: Fake Investment Platforms: Red Flags and Checklist
  • Kraken Blog: Crypto Investment Scams: How to Protect Yourself
  • Scamwatch (Australian Government): Fake Crypto Trading Platforms Alert
  • ASIC: Website Takedown Capability and Red Flags
  • OSL Digital Securities: How to Spot a Fake Crypto Investment Platform
  • Morgan Stanley: Crypto Scams to Watch Out For
  • Forensic Logic Inc: Fxcryptotradings.net Scam Report
  • CoinMarketCap: U.S. Regulators Shut Down $14M Crypto Scam
  • KuCoin: Telegram Impersonation Scams Warning
  • Bitdefender: Instagram Crypto Scams Guide

Found this guide helpful? Share it with someone who is considering a crypto investment. You could save them from losing their hard-earned money to the crypto withdrawal fees scam.

Disclaimer: I may earn a commission if you sign up through links in this post. This does not affect my recommendations. Cryptocurrency is volatile. Past performance does not guarantee future returns. Never invest more than you can afford to lose. Always verify a platform’s regulation before depositing funds. If you have been scammed, report it to the FBI IC3 at ic3.gov and the FTC at reportfraud.gov. ftc.gov.

The 50/30/20 Budget Rule That 64% of Americans Get Wrong (And How to Fix It in 2026)

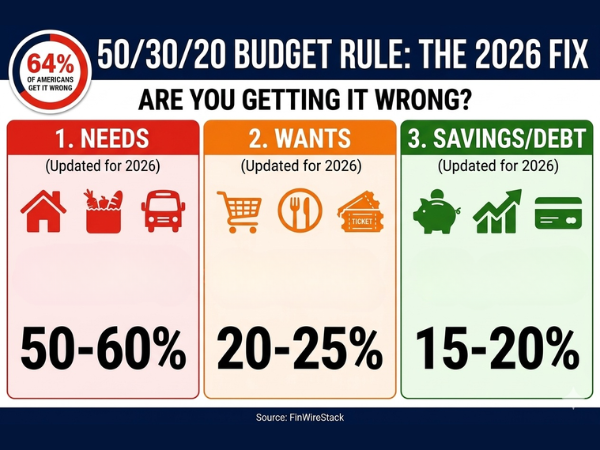
50/30/20 budget rule that 64% of Americans get wrong infographic showing 3 mistakes: mistaking wants for needs in 2026, treating debt payments as wants, and using gross pay instead of net pay with updated 2026 percentages: Needs 50-60%, Wants 20-25%, Savings/Debt 15-20%

Why Your Budget Keeps Failing (It Is Not Your Fault)

You have tried budgeting before. Maybe you used an app. Maybe you tried a spreadsheet. Maybe you just swore you would spend less.

And yet, according to the Federal Reserve’s 2026 Survey of Household Economics, 64% of Americans live paycheck to paycheck. Most of them have tried to budget. Most have failed.

Here is the truth they do not tell you: The 50/30/20 budget rule that 64% of Americans get wrong is not a bad rule. It is a good rule applied to the wrong reality.

The 50/30/20 rule was created in 2005 by Senator Elizabeth Warren. Back then, the average rent was $800. A gallon of gas was $2.50. A dozen eggs were $1.50.

In 2026, the average rent is $2,050. Gas is $4.50-6.00 per gallon. Eggs are $4-5 per dozen.

The 50/30/20 budget rule that 64% of Americans get wrongย is not mathematically impossible. It just needs to be updated for 2026 realities.

The good news is that once you understand the three mistakes almost everyone makes, you can fix your budget in one weekend.

For understanding why you feel broke despite trying to budget, see The Silent Budget Killer: 7 Hidden Expenses Draining Your Bank Account.

For the emotional side of budgeting failure, see How to Stop Worrying About Money.

For building savings after you fix your budget, see How to Build an Emergency Fund from Scratch.

What Is the 50/30/20 Rule? A Quick Refresher

Before we fixย the 50/30/20 budget rule that 64% of Americans get wrong, let us remind ourselves how it is supposed to work.

The Original 50/30/20 Rule

CategoryPercentageWhat It Includes
Needs50%Housing, utilities, groceries, transportation, minimum debt payments, insurance
Wants30%Dining out, entertainment, subscriptions, hobbies, travel, shopping
Savings/Debt20%Emergency fund, retirement, extra debt payments, investments

How It Is Supposed to Work

StepAction
1Calculate your monthly take-home pay (after taxes)
2Multiply by 0.5 for your Needs budget
3Multiply by 0.3 for your Wants budget
4Multiply by 0.2 for your Savings/Debt budget
5Spend within these limits

The 2005 vs. 2026 Reality Check

Expense2005 (Rule Created)2026Increase
Median rent$800$2,050+156%
Average car payment$300$740+147%
Health insurance (monthly)$200$450+125%
Groceries (family of 4)$600$1,200+100%
Gas (per gallon)$2.50$4.50-6.00+80-140%
Cell phone bill$50$120+140%

The problem is not the rule. The problem is that “needs” now cost more than 50% of most people’s income.

The 50/30/20 budget rule that 64% of Americans get wrongย is not broken. It just needs to be adapted.

For a complete budget template, see Best Budgeting Apps for Couples.

For tracking your spending, see The Silent Budget Killer.

The 50/30/20 Budget Rule That 64% of Americans Get Wrong: The 3 Critical Mistakes

The 50/30/20 budget rule that 64% of Americans get wrong fails for three specific reasons.

The Three Mistakes

MistakeWhat People DoWhy It Fails
1Categorize wants as needs50% becomes impossible to achieve
2Treat debt payments as “wants.”Minimum payments stay in needs; extra goes to wants
3Use gross pay instead of net payOverestimates available money

Why These Mistakes Matter in 2026

Mistake2005 Impact2026 Impact
Wants as needsMinor (needs were only 35-40% of income)Major (needs are 55-65% of income)
Debt as wantsMinor (less consumer debt)Major (credit card debt at 15-year high)
Gross vs. netMinor (taxes were lower)Major (taxes plus health insurance deductions)

*The 50/30/20 budget rule that 64% of Americans get wrong* can work in 2026. You just need to avoid these three mistakes.

For understanding debt in 2026, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For paycheck calculations, see How to Stop Living Paycheck to Paycheck.

Mistake #1: Mistaking Wants for Needs in 2026

The 50/30/20 budget rule that 64% of Americans get wrong starts with mis-categorization.

What Is Actually a Need in 2026?

CategoryNeedNot a Need
HousingBasic shelter (rent/mortgage)Premium location, extra bedrooms
FoodGroceries, basic ingredientsRestaurants, delivery, prepared foods
TransportationReliable transportationNew car, premium gas, frequent trips
UtilitiesBasic electricity, water, heatPremium cable, multiple streaming services
HealthcareInsurance, basic careElective procedures, premium plans
PhoneBasic serviceLatest iPhone, unlimited data

The “Would I Die Without It?” Test

QuestionIf Yes โ†’ NeedIf No โ†’ Want
Would I be homeless without this?HousingUpgrades
Would I be hungry without this?Basic groceriesRestaurants
Would I be unable to work without this?Basic transportationLuxury car
Would I be sick without this?HealthcareElective

Real Examples: Need vs. Want in 2026

ExpenseCommon MistakeCorrect Category
$2,500 apartmentNeed (but high)Need (but problematic)
$1,500 apartment with roommateNeedNeed (better)
$800 car paymentNeed? No.Want a cheaper car?
$300 car payment (used car)NeedNeed
$400 grocery bill (cooking at home)NeedNeed
$800 grocery bill (prepared foods)WantWant (mostly)
Netflix, Hulu, Disney+“Need for entertainment”Wants

The 50/30/20 budget rule that 64% of Americans get wrongย often fails because people refuse to call their luxuries what they are.

For grocery budgeting, see How to Save Money on Groceries.

For housing costs, see How to Survive the 2026 Cost of Living Crisis.

Mistake #2: Treating Debt Payments as “Wants”

The 50/30/20 budget rule that 64% of Americans get wrong has a second critical flaw: where to put debt payments.

The Original Rule’s Debt Guidance

Type of DebtWhere It Goes
Minimum paymentsNeeds (50%)
Extra paymentsSavings/Debt (20%)

Why This Fails in 2026

ProblemExplanation
High interest ratesCredit card interest at 22-29% is an emergency
Large balancesMinimum payments barely touch principal
Delayed savingsPaying interest is throwing away money

The 2026 Correction: Debt Is an Emergency

Debt TypeInterest RateCategoryAction
Credit card debt22-29%EmergencyPay before savings (except 401k match)
Personal loan15-25%High priorityPay before wants
Student loan5-10%Medium priorityPay minimums + extra if possible
Car loan7-15%Medium priorityPay minimums
Mortgage5-7%Low priorityPay minimums

The Revised 50/30/20 for People with Debt

CategoryPercentageWhat It Includes
Needs50-60%Housing, utilities, groceries, transportation, minimum debt payments
Debt Emergency15-20%Extra payments on high-interest debt (over 10%)
Wants15-20%Dining out, entertainment, subscriptions
Savings5-10%Only after high-interest debt is gone

The 50/30/20 budget rule that 64% of Americans get wrongย must prioritize debt before savings for most people in 2026.

For prioritizing debt payments, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For balance transfer options, see How to Get Out of Credit Card Debt.

For credit counseling, see How to Get Out of Credit Card Debt Fast When You Have No Money (credit counseling section).

Mistake #3: Using Take-Home Pay Incorrectly

The 50/30/20 budget rule that 64% of Americans get wrong has a third mistake: miscalculating your income.

Gross Pay vs. Net Pay

TermDefinitionShould You Use It?
Gross payIncome before taxes and deductionsโŒ No
Net payIncome after taxes and deductionsโœ… Yes

The Problem with Using Gross Pay

Monthly Gross Pay50% for NeedsYour Actual Net PayProblem
$5,000$2,500$3,800The needs budget exceeds the net pay. No, but tight.
$4,000$2,000$3,100The needs budget is 65% of net pay
$3,000$1,500$2,400The needs budget is 62% of net pay

What to Include in “Take-Home Pay”

IncludeDo Not Include
Salary/wages after taxGross salary
Side hustle income (after estimated tax)Bonuses (until received)
Child supportInvestment gains (until realized)
AlimonyGifts (unpredictable)

How to Calculate Your True Take-Home Pay

StepAction
1Look at your last paycheck
2Find the “Net Pay” amount
3Multiply by the number of paychecks per month
4Add any consistent side income (after estimated tax)

Example:

Income SourceAmount
Net paycheck (bi-weekly $1,500)$3,250/month (2.166 pay periods)
Side hustle (after tax)$400/month
Total take-home pay$3,650/month

The 50/30/20 budget rule that 64% of Americans get wrongย works when you start with the right number.

For income tracking, see Best Free Portfolio Trackers for Crypto and Stocks.

For side hustle income, see How to Get Out of Credit Card Debt Fast When You Have No Money (side hustle section).

How to Fix the 50/30/20 Rule for 2026

Now that you know the three mistakes, here is how to fixย the 50/30/20 budget rule that 64% of Americans get wrong.

The 2026 Adjusted 50/30/20 Rule

Category2026 Adjusted PercentageWhat It Includes
Needs50-60%Housing, utilities, groceries, basic transportation, minimum debt payments, and healthcare
Wants20-25%Dining out, entertainment, subscriptions, shopping, hobbies
Savings/Debt15-20%Emergency fund, retirement, extra debt payments, investments

Step-by-Step Fix

StepActionTime
1Calculate your true take-home pay (net, not gross)15 min
2List every expense from last month30 min
3Categorize each expense honestly (Need? Want? Debt?)20 min
4Add up your Needs total5 min
5If needs are > 60% of take-home pay, you must cut or increase income1 hour
6Allocate remaining money: Wants (20-25%), Savings/Debt (15-20%)15 min

The needs exceed 60%? Here Is What to Do

If Needs are…Action
61-65%Cut wants aggressively; look for small housing/transportation savings
66-75%Major changes needed: roommate, cheaper car, move to a cheaper area
Over 75%Income must increase (side hustle, better job, overtime)

The 50/30/20 budget rule that 64% of Americans get wrongย can be fixed. It just requires honesty about your numbers.

For cutting housing costs, see How to Survive the 2026 Cost of Living Crisis.

For increasing income, see How to Get Out of Credit Card Debt Fast When You Have No Money (side hustle section).

For automating your fixed budget, see Automated Savings Apps That Actually Work.

The 50/30/20 Budget Rule That Works in 2026: Real Examples

Let us walk throughย the 50/30/20 budget rule that 64% of Americans get wrongย with real examples.

Example 1: Single Person, $50,000 Annual Salary

MetricAmount
Gross monthly salary$4,167
Net monthly take-home$3,200
Category2026 Adjusted BudgetActual SpendingStatus
Needs (55%)$1,760$1,800โš ๏ธ Slightly over
Wants (25%)$800$700โœ… Under
Savings/Debt (20%)$640$700โœ… Over

What this person did right:ย Honest categorization adjusted the needs percentage upward and kept wants in check.

Example 2: Couple, $80,000 Combined, $15,000 Credit Card Debt

MetricAmount
Gross combined monthly$6,667
Net combined take-home$5,000
Category2026 Adjusted BudgetActual SpendingStatus
Needs (60%)$3,000$3,200โš ๏ธ Over
Debt Emergency (20%)$1,000$1,000โœ… On track
Wants (20%)$1,000$800โœ… Under

What this couple did right:ย prioritized debt before savings and reduced wants to accommodate higher needs.

Example 3: Family of 4, $120,000 Combined

MetricAmount
Gross combined monthly$10,000
Net combined take-home$7,200
Category2026 Adjusted BudgetActual SpendingStatus
Needs (58%)$4,176$4,200โš ๏ธ Slightly over
Wants (22%)$1,584$1,500โœ… Under
Savings (20%)$1,440$1,500โœ… Over

The 50/30/20 budget rule that 64% of Americans get wrongย works when you adjust percentages to your reality.

For couples budgeting, see Best Budgeting Apps for Couples.

For family budgeting, see How to Save Money on Groceries.

50/30/20 Budget Template (Free Download)

Here is a simple template to implementย the 50/30/20 budget rule that 64% of Americans get wrong.

Monthly Budget Tracker

CategoryYour BudgetActualDifference
NEEDS (50-60%)
Rent/Mortgage$_____$_____$_____
Utilities$_____$_____$_____
Groceries$_____$_____$_____
Transportation$_____$_____$_____
Minimum debt payments$_____$_____$_____
Health insurance$_____$_____$_____
Total Needs$_____$_____$_____
WANTS (20-25%)
Dining out$_____$_____$_____
Entertainment$_____$_____$_____
Subscriptions$_____$_____$_____
Shopping$_____$_____$_____
Hobbies$_____$_____$_____
Total Wants$_____$_____$_____
SAVINGS/DEBT (15-20%)
Emergency fund$_____$_____$_____
Retirement$_____$_____$_____
Extra debt payments$_____$_____$_____
Investments$_____$_____$_____
Total Savings/Debt$_____$_____$_____
TOTAL SPENDING$_____$_____$_____
Take-home pay$_____

For digital budgeting tools, see Best Budgeting Apps for Couples.

For automated savings, see Automated Savings Apps That Actually Work.

For emergency fund building, see How to Build an Emergency Fund from Scratch.

The 50/30/20 Budget Rule That 64% of Americans Get Wrong: Frequently Asked Questions

Why does the 50/30/20 rule not work for me?

The 50/30/20 budget rule that 64% of Americans get wrongย typically fails for three reasons: (1) you are categorizing wants as needs, inflating your needs category above 50-60%; (2) you are using gross pay instead of net pay; or (3) you are not prioritizing high-interest debt before savings. Fix these three mistakes, and the rule works.

How do I budget if my needs are already over 60% of my income?

If your needs exceed 60% of your take-home pay, you have two options: (1) reduce your needs (get a roommate, get a cheaper car, move to a cheaper area, or reduce utility usage), or (2) increase your income (side hustle, overtime, or better job). In the meantime, adjust the rule: Needs (60-70%), Wants (15-20%), and Savings/Debt (10-15%).

Where should I put credit card debt payments in the 50/30/20 rule?

Minimum credit card payments go to Needs. Extra payments (above the minimum) should be prioritized in the Savings/Debt category BEFORE you save for retirement (except for a 401k match). Credit card interest at 22-29% is an emergency. Pay it off before building savings beyond a $1,000 buffer.

Should I use gross or net income for the 50/30/20 rule?

Always use net income (take-home pay after taxes and deductions). Using gross income overstates your available money and causes you to overspend.ย The 50/30/20 budget rule that 64% of Americans get wrongย starts with the wrong number.

What counts as a “need” in 2026?

A need is something you would be homeless, hungry, unable to work, or sick without. Basic housing (not premium), basic groceries (not restaurants), basic transportation (not a luxury car), utilities, healthcare, and minimum debt payments. Premiums, upgrades, and convenience are wants.

How do I start the 50/30/20 rule today?

StepAction
1Calculate your monthly take-home pay
2Review your last month of spending
3Categorize every expense as need, want, or savings/debt.
4Add up your Needs total
5If Needs > 60%, cut wants and consider major changes
6Allocate remaining money to wants and savings/debt.

For more budgeting help, see Best Budgeting Apps for Couples.

For debt payoff while budgeting, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For building savings, see How to Build an Emergency Fund from Scratch.

Your 7-Day Budget Reset Plan

The 50/30/20 budget rule that 64% of Americans get wrong can be fixed in one week.

Day 1-2: Assessment (1 hour)

DayActionTime
Day 1Calculate your true monthly take-home pay15 min
Day 1List every expense from last month30 min
Day 2Categorize each expense (Need? Want? Debt?)30 min
Day 2Add up your Needs total15 min

Day 3-4: Adjustment (1 hour)

DayActionTime
Day 3If Needs > 60%, identify areas to cut30 min
Day 3Research cheaper alternatives (roommate, refinance, insurance)30 min
Day 4Create your 2026 adjusted 50/30/20 budget30 min
Day 4Set up automatic transfers for the Savings/Debt category15 min

Day 5-7: Implementation (30 minutes)

DayActionTime
Day 5Use cash or debit for wants this week5 min
Day 6Track every expense for one day10 min
Day 7Review progress and adjust as needed15 min

The Bottom Line

Sixty-four percent of Americans live paycheck to paycheck. Most have tried budgeting. Most have failed.

Butย the 50/30/20 budget rule that 64% of Americans get wrongย is not bad. It is a good rule applied to the wrong reality.

FixWhat to Do
Mistake #1Be honest about needs vs. wants in 2026
Mistake #2Prioritize high-interest debt before savings
Mistake #3Use net pay, not gross pay

The difference between those who make budgeting work and those who give up is not income. It is knowing the three mistakes and how to fix them.

Ready to fix your budget? Download our 50/30/20 budget template or share this guide with someone who needs it.

Reviewed by: Dennis M, FinTech Researcher

Dennis has tested over 50 digital banking apps and 25 crypto exchanges.

The Silent Budget Killer: 7 Hidden Expenses Draining Your Bank Account in 2026

The silent budget killer infographic showing 7 hidden expenses: subscription creep wasting $300-600 annually, convenience tax costing $500-1,500, bank fees taking $100-400, energy vampires adding $100-200, credit card interest stealing $500-2,000, daily $5 leaks totaling $1,000-5,000, and inflation inertia eroding $500-2,000 with total potential waste of $3,000-11,000 per year

The $15,000 Question: Where Does Your Money Actually Go?

Here is a question that keeps 64% of Americans awake at night: Where did all my money go?

You get paid. You pay bills. Two weeks later, your account is empty. You cannot point to any big purchase. No vacation. No new TV. Just… nothing.

The silent budget killer is not a single expense. It is dozens of small leaks that drain your bank account without you noticing.

The silent budget killer is invisible by design. Subscription services auto-renew. Convenience fees hide at checkout. Energy vampires suck power while you sleep. None of these expenses triggers alarm bells. But together, they can cost you $4,000 to $15,000 per year.

The average American loses $238 per month** to hidden expenses they never see. That is **$2,856 per year. For a family of four, the number doubles to nearly $6,000.

The silent budget killer is the reason you feel broke even when your income is okay. It is the gap between what you earn and what you keep.

The good news is that once you see these leaks, you can stop them. This article reveals the 7 most common silent budget killers and exactly how to plug each one.

For understanding your full financial picture, see How to Build an Emergency Fund from Scratch.

For tracking your spending, see Best Budgeting Apps for Couples.

For the emotional side of money leaks, see How to Stop Worrying About Money.

The Silent Budget Killer #1: Subscription Creep

The silent budget killer starts with subscriptions. You signed up for a free trial. You forgot to cancel. Months later, you are still paying.

The Numbers Are Staggering

StatisticValue
Average number of subscriptions per person4-6
Average monthly subscription spend$80-150
Subscriptions people forget they have2-3
Money wasted on unused subscriptions annually$300-600 per person

The Most Common Forgotten Subscriptions

Subscription TypeTypical Monthly CostAnnual Cost
Streaming services (Netflix, Hulu, Disney+)$15-50$180-600
Gym membership$30-60$360-720
Meal kits$50-100$600-1,200
Cloud storage$5-15$60-180
App subscriptions$5-20$60-240
Magazine or news$10-20$120-240
Box subscriptions$20-40$240-480

Why Subscription Creep Happens

ReasonExplanation
Free trialsYou intend to cancel but forget
Annual billingYou forget when the renewal date arrives
Small charges$9.99 does not feel like real money
No visibilityYou do not check your statements
Auto-renewalCompanies make cancellation difficult

How to Find and Eliminate Subscription Creep

StepActionTime
1Check your last 3 months of bank statements20 minutes
2Highlight every recurring charge10 minutes
3Ask: “Have I used this in the last 30 days?”5 minutes
4Cancel everything you have not used15 minutes

Tools to Track Subscriptions

ToolPriceWhat It Does
Rocket MoneyFree / $4-12/monthFinds and cancels subscriptions
Truebill (now Rocket Money)FreeTracks recurring charges
Your bank appFreeOften has subscription tracking
Manual spreadsheetFreeLists all subscriptions with renewal dates

The silent budget killer of subscription creep can be eliminated in one hour. The average person finds $50-100 in monthly savings.

For saving the money you find, see Automated Savings Apps That Actually Work.

For digital banking tools, see Digital Banking vs Traditional Banking.

The Silent Budget Killer #2: The Convenience Tax

The silent budget killer number two is the price you pay for convenience. Delivery fees. Service fees. Processing fees. Convenience fees. They seem small. They add up fast.

The Many Forms of Convenience Tax

ConvenienceFeeAnnual Cost (if used weekly)
Food delivery (DoorDash, UberEats)$5-10 delivery + fees + tip$500-1,500
ATM fees (out-of-network)$3-5 per transaction$150-250
Late payment fees$25-40 per occurrence$300-500
Ticket processing fees$5-15 per ticket$100-300
Hotel resort fees$20-50 per night$500-1,500 (vacation)
Credit card convenience fees2-4% of transactionVaries
In-app purchase markup10-30% markupVaries

The Food Delivery Trap

MethodMeal Cost for 2Monthly (4x)Annual
Pick up yourself$25$100$1,200
Delivery (+ fees + tip)$40$160$1,920
Savings from picking up$15$60$720

The ATM Fee Trap

BehaviorMonthly ATM FeesAnnual Cost
Use out-of-network ATM 2x/week ($4 fee)$32$384
Use your bank’s ATM$0$0
Savings$32$384

How to Avoid the Convenience Tax

ConvenienceAlternativeSavings
Food deliveryPick up your own food$10-15 per order
Out-of-network ATMPlan ahead, get cash back at stores$3-5 per transaction
Late feesSet up automatic bill pay$25-40 per occurrence
Ticket feesBuy at box office$5-15 per ticket
Resort feesChoose hotels without them$20-50 per night
Credit card feesUse debit or cash2-4% per transaction

The silent budget killer of convenience fees is the easiest to fix. Every time you choose the free option, you pay yourself.

For avoiding late fees, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For banking without fees, see Digital Banking vs Traditional Banking.

The Silent Budget Killer #3: Bank and Overdraft Fees

The silent budget killer number three lives inside your own bank account. Millions of Americans pay hundreds of dollars each year in fees they could easily avoid.

The Bank Fee Breakdown

Fee TypeTypical CostAnnual Cost (if incurred monthly)
Monthly maintenance fee$5-25$60-300
Overdraft fee$35 per occurrence$420 (one per month)
Returned deposit fee$15-25$180-300
Wire transfer fee (domestic)$15-30$180-360
Wire transfer fee (international)$35-50$420-600
Paper statement fee$1-5$12-60
Account closure fee$0-25One-time

The Overdraft Trap

ScenarioCost
You buy coffee for $4.50
Your balance is $4.25
Coffee purchase goes through$35 overdraft fee
Cost of that coffee$39.50

How Overdraft Fees Compound

MonthOverdraftsFees Paid
January1$35
February1$70
March1$105
April1$140
May1$175
June1$210
Total after 6 months$210

How to Eliminate Bank Fees

FeeSolution
Monthly maintenanceSwitch to a no-fee bank or credit union
OverdraftOpt out of overdraft protection (transaction will simply be declined)
Paper statementsSwitch to electronic statements
Wire transfer feesUse free services like Zelle, Venmo, or PayPal
Minimum balance feesChoose a bank with no minimum requirement

Best No-Fee Banks in 2026

BankMonthly FeeOverdraft FeeMinimum Balance
SoFi$0$0$0
Ally Bank$0$0$0
Chime$0$0$0
Capital One 360$0$0$0
Discover Bank$0$0$0

The silent budget killer of bank fees is completely avoidable. If your bank charges fees, switch today.

For comparing banks, see Digital Banking vs Traditional Banking.

For free checking accounts, see How to Build an Emergency Fund from Scratch.

The Silent Budget Killer #4: Energy Vampires

The silent budget killer number four is hiding in your walls. Electronic devices continue drawing power even when they are turned off.

What Are Energy Vampires?

Energy vampires are devices that consume electricity when they are not in active use. They sit in “standby” mode, waiting for a signal to wake up.

Common Energy Vampires

DeviceStandby Power DrawAnnual Cost
Gaming consoles (PS5, Xbox)10-15 watts$15-25
Computers (desktop)5-10 watts$8-15
Cable box20-30 watts$30-45
Smart TV5-10 watts$8-15
Phone charger (plugged in)0.5-1 watt$1-2
Coffee maker1-2 watts$2-4
Microwave2-5 watts$3-8
Router and modem10-20 watts$15-30
Total per household$100-200 per year

How to Slay Energy Vampires

SolutionCostSavings
Unplug devices when not in useFree$50-100/year
Use a power strip and turn it off$10-20$50-100/year
Buy smart power strips$20-40$75-150/year
Enable power-saving modesFree$20-50/year

The Smart Power Strip Investment

InvestmentCostAnnual SavingsPayback Period
Smart power strip$25$754 months
5 smart power strips$125$3754 months

The silent budget killer of energy vampires is easy to fix. Unplugging your devices before bed takes 30 seconds.

For energy savings during the cost of living crisis, see How to Survive the 2026 Cost of Living Crisis.

For utility bill reduction, see How to Save Money on Groceries (same principles apply).

The Silent Budget Killer #5: Interest on Carry Debt

The silent budget killer number five is the most expensive. Carrying credit card debt month to month costs you hundreds or thousands of dollars in interest.

The Interest Trap

Credit Card BalanceInterest Rate (APR)Interest Paid in One YearMonthly Payment
$1,00022%$220$55 (minimum)
$3,00022%$660$165 (minimum)
$5,00022%$1,100$275 (minimum)
$10,00022%$2,200$550 (minimum)

Why Interest Is a Silent Budget Killer

You Think You Are PayingYou Are Actually Paying
$50 per month toward your balance$35 in interest, $15 toward balance
100% of your payment goes to debt70-90% goes to interest
Debt will be gone in 12 monthsDebt will take 3-5 years

The Minimum Payment Trap

BalanceMinimum PaymentYears to Pay OffTotal Interest Paid
$5,000$1006 years$2,200
$5,000$2002.5 years$900
$5,000$50010 months$380

How to Escape the Interest Trap

StrategyHow It WorksSavings
Balance transferMove debt to 0% APR card$1,000+ per year
Debt avalanchePay highest interest firstHundreds to thousands
Debt snowballPay smallest balance firstBuilds momentum
Hardship programCall credit card company for lower rate$500+ per year

The silent budget killer of credit card interest is the most urgent to address. Every month you carry debt, you lose money.

For debt payoff strategies, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For balance transfer cards, see How to Get Out of Credit Card Debt.

For negotiating with credit card companies, see How to Stop Living Paycheck to Paycheck.

The Silent Budget Killer #6: The $5 Daily Leak

The silent budget killer number six is the most deceptive. It is the $5 here, the $10 there. Individually, these purchases are meaningless. Collectively, they are a fortune.

The Math of Small Leaks

Daily SpendingMonthly CostAnnual Cost10-Year Cost (Invested at 7%)
$3 (coffee)$90$1,095$15,000
$5 (lunch out)$150$1,825$25,000
$10 (impulse buys)$300$3,650$50,000
$15 (dinner out)$450$5,475$75,000
$20 (entertainment)$600$7,300$100,000

The $5 Test

Before any non-essential purchase, ask yourself:

QuestionWhy It Matters
“Would I rather have this $5 or an extra $15,000 in 10 years?”Puts small purchases in long-term perspective
“Is this purchase adding value to my life?”Separates wants from genuine needs
“Could I get this for free or cheaper?”Encourages resourcefulness

The 24-Hour Rule for All Non-Essential Purchases

StepAction
1See something you want to buy
2Take a photo of it
3Wait 24 hours
4If you still want it, consider buying it

After 24 hours, 80% of impulse urges disappear.

The Weekly Cash Method

StepAction
1Withdraw your weekly discretionary budget in cash
2When the cash is gone, no more spending
3Physical cash feels more real than tapping a card

The silent budget killer of small daily leaks is the hardest to notice, but the easiest to fix once you see it.

For behavioral strategies, see How to Stop Worrying About Money.

To save money, you stop leaking; see Automated Savings Apps That Actually Work.

For investing the savings, see Passive Income Portfolio with $1,000.

The Silent Budget Killer #7: Inflation Inertia

The silent budget killerย number seven is the one you cannot control, but can adapt to. Inflation has raised the price of almost everything. But most people keep spending the same way.

The 2026 Inflation Reality

CategoryPrice Increase Since 2020Current Price
Groceries+25%$1,200/month for family of 4
Gas+60%+$4.50-6.00/gallon
Utilities+20%$200-400/month
Rent+35%$2,050/month average

The Inflation Inertia Problem

Old MindsetNew Reality
“I have always bought this brand”Store brands are 30-40% cheaper
“I will buy the same amount of gas”Combine trips and reduce driving
“I will keep the thermostat at 72.”68ยฐ in winter and 76ยฐ in summer saves 10%
“I will keep my old spending habits”Must adapt to new prices

How to Adapt to Higher Prices

CategoryAdaptationSavings
GroceriesSwitch to store brands and meal plan$200-400/month
GasCarpool, public transit, combine trips$100-300/month
UtilitiesLower the thermostat, and unplug vampires$30-100/month
RentNegotiate renewal, get roommate$200-500/month

The silent budget killer of inflation inertia is not the price increases themselves. It is failing to change your behavior in response.

For grocery adaptation, see How to Save Money on Groceries.

For rent negotiation, see How to Survive the 2026 Cost of Living Crisis.

For utility savings, see How to Build an Emergency Fund from Scratch.

The $4,378 Challenge: Track Your Hidden Expenses for 30 Days

Now that you know the 7 silent budget killers, it is time to find YOUR leaks.

The 30-Day Tracking Challenge

WeekFocusAction
Week 1Subscription auditList every recurring charge
Week 2Convenience fee auditTrack every delivery, ATM, late fee
Week 3Bank fee auditCheck statements for hidden fees
Week 4Energy and small leak auditTrack standby power and daily small purchases

The Hidden Expense Tracker

DateExpense TypeAmountSilent Killer Category

What Previous Challengers Found

PersonHidden Expenses FoundAnnual Savings
Sarah, 34Unused gym membership, 3 streaming services$720
Mike, 42Energy vampires, out-of-network ATM fees$480
Lisa, 28Delivery fees, subscription creep$1,200
David, 55Credit card interest, bank fees$2,800

Your Goal

Find at leastย $378 in hidden expenses this month. That is $4,536 per year.

The silent budget killer is only a killer if you let it hide. Once you see it, you can stop it.

For accountability, see Best Budgeting Apps for Couples.

For celebrating savings milestones, see How to Stop Worrying About Money.

The Silent Budget Killer: Frequently Asked Questions

What is the biggest silent budget killer?

For most people, subscription creep and credit card interest are the largest silent budget killers. The average person wastes $300-600 annually on unused subscriptions. Credit card interest can cost thousands per year if you carry a balance.

How do I find hidden expenses in my budget?

Review your last 3 months of bank statements. Highlight every recurring charge. Look for subscriptions you do not use, fees you did not notice, and small daily purchases that add up. The 30-day tracking challenge above walks you through exactly how.

Why am I broke every month, even with a good income?

This is the classic sign of the silent budget killer. Your income is not the problem. Small, unnoticed leaks are. Subscription creep, convenience fees, bank charges, energy vampires, interest payments, daily small purchases, and inflation inertia combine to drain your account invisibly.

How much does the average person waste on hidden expenses?

The average American loses $238 per month ($2,856 per year) to hidden expenses. For a family of four, that number doubles to nearly $6,000 annually. Most people have no idea where this money goes.

What is the easiest silent budget killer to fix?

Subscription creep is the easiest. Log into your bank account, find every recurring charge, and cancel anything you have not used in the last 30 days. This takes one hour and saves $300-600 per year.

How do I stop impulse spending?

Use the 24-hour rule for any non-essential purchase over $20. Wait a full day before buying. Use the weekly cash method โ€“ withdraw your discretionary budget in cash. When the cash is gone, spending stops. And ask the $5 test question before every small purchase.

For more on stopping impulse spending, see How to Get Out of Credit Card Debt Fast When You Have No Money.

For building savings from found money, see How to Build an Emergency Fund from Scratch.

For protecting your money from future leaks, see Protect Your Brokerage Account from Hackers.

Your Action Plan for This Week

The silent budget killer cannot survive your attention.

Today (30 minutes)

ActionWhy
Log into your bank accountFace the numbers
Download your last 3 months of statementsFind the leaks
Highlight every recurring chargeSee subscription creep

This Week (1 hour)

ActionWhy
Cancel all unused subscriptionsInstant savings
Call your bank to waive any feesFree money
Unplug energy vampires before bedLower electric bill

Next Week (1 hour)

ActionWhy
Start the 30-day tracking challengeFind YOUR leaks
Set up automatic bill payStop late fees
Switch to a no-fee bankEnd bank fees permanently

The Bottom Line

Sixty-four percent of Americans live paycheck to paycheck. Most cannot explain why.

The silent budget killer is the explanation.

Silent Budget KillerAverage Annual Cost
Subscription creep$300-600
Convenience tax$500-1,500
Bank and overdraft fees$100-400
Energy vampires$100-200
Credit card interest$500-2,000+
$5 daily leaks$1,000-5,000+
Inflation inertia$500-2,000+
Total potential waste$3,000-11,000+

The difference between feeling broke and feeling secure is not earning more. It is keeping more of what you earn.

Ready to stop the leaks? Download our hidden expense tracker or share this guide with someone who needs it.

Reviewed by: Dennis M, FinTech Researcher & Developer

Dennis has tested over 50 digital banking apps and 25 crypto exchanges. He writes about FinTech tools for real people.

How to Save Money on Groceries in 2026: 12 Tips That Work

How to save money on groceries in 2026: 12 tips showing meal planning, shopping list, store brands, grocery pickup, sales cycles, digital coupons, whole foods instead of pre-cut, stop buying beverages, eat less meat, shop after eating, unit price comparison, and growing herbs with grocery prices up 25 percent since 2020

Why Grocery Prices Are Still Rising in 2026

How to save money on groceries has become a survival skill for American families in 2026.

The numbers are staggering. According to the Bureau of Labor Statistics, grocery prices have increasedย 25% since 2020. A family of four now spends an average of **$1,200 per month** on groceriesโ€”up from $960 just three years ago.

How to save money on groceries matters because food is the largest variable expense for most households. Unlike rent or car payments, you have control over what you spend at the grocery store.

The good news is thatย learning how to save money on groceriesย is a skill you can learn. The strategies below work regardless of your income level.

The 2026 Grocery Reality

Metric20202026Change
Average monthly grocery bill (family of 4)$960$1,200+25%
Percentage of income spent on food9.5%11.5%+2%
Americans struggling to afford groceries35%50%+15%

How to save money on groceries is not about deprivation. It is about shopping strategically.

For understanding the broader cost of living crisis, seeย How to Survive the 2026 Cost of Living Crisis.

For managing your overall food budget, seeย Best Budgeting Apps for Couples.

How to Save Money on Groceries: Tip 1

The first tip onย how to save money on groceriesย is toย plan your meals before you shop.

Shopping without a plan is the #1 reason people overspend. You buy things you do not need. You forget things you do need. You make multiple trips to the store.

The Weekly Meal Planning Method

DayActionTime
ThursdayCheck what you already have10 minutes
FridayPlan 7 dinners using what you have20 minutes
SaturdayMake grocery list from your plan15 minutes
SundayShop from your list only1 hour

How Meal Planning Saves Money

Without a Meal PlanWith Meal Plan
Buy random ingredientsBuy only what you need
Food goes bad before useEverything gets used
Takeout because “nothing to eat”Meals ready to cook
Multiple store tripsOne trip per week

How to save money on groceries starts with knowing what you will eat before you shop.

For meal planning templates, seeย How to Stop Living Paycheck to Paycheck.

How to Save Money on Groceries: Tip 2

The second tip inย how to save money on groceriesย is toย always shop with a listโ€”and stick to it.

Studies show that shoppers without a list spend 40% more than those with a list. The grocery store is designed to make you impulse buy.

The List Rule

DoDon’t
Write your list before leaving homeShop without a list
Organize by store layoutBuy anything not on the list
Stick to your listGo when hungry
Use grocery pickup to avoid impulse buysTake children if they cause impulse purchases

The 24-Hour Rule for Non-List Items

If you see something not on your list that you want:

StepAction
1Take a photo of the item
2Leave it at the store
3Wait 24 hours
4If you still want it, add to next week’s list

Most impulses pass within 24 hours.

How to save money on groceries requires discipline at the store.

For impulse spending control, seeย How to Get Out of Credit Card Debt Fast When You Have No Money.

How to Save Money on Groceries: Tip 3

The third tip in how to save money on groceries is to shop store brands instead of name brands.

Store brands are typically manufactured by the same companies as name brands. The difference is in packaging and price.

Store Brand vs. Name Brand Savings

ProductName BrandStore BrandSavings
Cereal$5.50$3.00$2.50
Pasta$1.80$1.00$0.80
Canned tomatoes$2.00$1.20$0.80
Peanut butter$4.50$3.00$1.50
Yogurt (6-pack)$4.00$2.50$1.50
Weekly savings$7-15
Annual savings$365-780

What to Buy Store Brand

CategorySafe to Buy Store Brand
Pantry staplesCanned goods, pasta, rice, flour, sugar
DairyMilk, butter, cheese, yogurt
Frozen vegetablesNo difference
Baking ingredientsFlour, sugar, baking soda
SpicesSame quality

What to Buy Name Brand (Sometimes)

CategoryWhy Name Brand
SodaDifferent taste
CerealDifferent taste
Condiments (ketchup, mayo)Different recipes
Toilet paperQuality varies

How to save money on groceries means knowing when store brands are identical.

For bulk buying strategies, see Automated Savings Apps That Actually Work.

How to Save Money on Groceries: Tip 4

The fourth tip in how to save money on groceries is to use grocery pickup to avoid impulse buys.

Grocery pickup services are free at most major stores. You order online. They bring it to your car. You never enter the store.

Grocery Pickup Savings

FactorIn-Store ShoppingGrocery Pickup
Exposure to end capsYesNo
Impulse purchasesHighZero
Hunger shoppingYesNo
Children asking for itemsYesNo
Average overspend40%5-10%

Free Grocery Pickup Services

StoreServiceMinimum Order
WalmartFree pickup$35
KrogerFree pickup$35
TargetFree pickup$35
AldiFree pickupVaries
Whole FoodsFree with Prime$35

How to Use Grocery Pickup Effectively

StepAction
1Plan your meals (Tip 1)
2Make your list (Tip 2)
3Order exactly what is on the list
4Choose store brands (Tip 3)
5Pick up without entering the store

How to save money on groceries is easier when you remove yourself from the store environment.

For digital shopping tools, see Digital Banking vs Traditional Banking.

How to Save Money on Groceries: Tip 5

The fifth tip in how to save money on groceries is to shop sales cycles and stock up strategically.

Grocery stores run sales on a predictable cycle. Most items go on sale every 6-12 weeks.

Common Sales Cycles

ItemSales CycleBest Time to Buy
Canned goodsEvery 8-10 weeksStock up
Pasta and sauceEvery 6-8 weeksStock up
MeatEvery 2-3 weeksBuy in bulk, freeze
CerealEvery 8-10 weeksStock up
Paper productsEvery 10-12 weeksBuy in bulk
Frozen vegetablesEvery 6-8 weeksStock up

The Stock-Up Rule

If the sale is…Buy enough for…
20-30% off regular price2-4 weeks
30-50% off regular price4-8 weeks
50%+ off regular price8-12 weeks (or until expiration)

What Not to Stock Up On

ItemWhy
Fresh produceSpoils quickly
DairyExpires
BreadGets stale
EggsExpires

How to save money on groceries means buying more when prices are low and less when prices are high.

For freezer storage tips, seeย How to Build an Emergency Fund from Scratch.

How to Save Money on Groceries: Tip 6

The sixth tip in how to save money on groceries is to use digital coupons and cashback apps.

You are leaving money on the table if you do not use these free tools.

Best Cashback Apps for Groceries

AppHow It WorksTypical Cashback
IbottaUpload receipt, select offers5-20%
FetchUpload any receipt1-10%
RakutenShop through app1-15%
Coupons.comPrint or load digital coupons$0.25-2.00 per item
Store apps (Kroger, Safeway)Load digital coupons to loyalty card10-30%

How Much You Can Save

MethodWeekly SavingsAnnual Savings
Store loyalty card only$5-10$260-520
Store app digital coupons$10-20$520-1,040
Ibotta + Fetch$5-15$260-780
Combined strategies$20-40$1,040-2,080

The 5-Minute Weekly Routine

DayActionTime
FridayScan store app for coupons on your list5 minutes
SaturdayCheck Ibotta and Fetch for offers5 minutes
SundayShop, upload receipt after5 minutes

How to save money on groceries includes using free apps that pay you to shop.

For saving money across all expenses, seeย How to Stop Worrying About Money.

How to Save Money on Groceries: Tip 7

The seventh tip in how to save money on groceries is to buy whole foods instead of pre-cut, pre-packaged items.

Convenience costs money. Pre-cut vegetables, pre-shredded cheese, and pre-made meals cost 2-5x more than the whole version.

The Convenience Tax

ItemPre-cut/Pre-packagedWholeMarkup
Vegetables$5.99 (pre-cut bag)$2.99 (whole)+100%
Cheese$5.00 (shredded bag)$3.00 (block)+67%
Chicken$8.99 (cutlets)$4.99 (whole breast)+80%
Salad$6.00 (bagged)$4.00 (head of lettuce)+50%
Onions$3.00 (diced frozen)$1.00 (whole)+200%

What to Buy Whole and Prep Yourself

ItemWhole FormPrep Time
VegetablesWhole heads, bunches5-10 minutes/week
CheeseBlock2 minutes
ChickenWhole breast or thigh5 minutes
LettuceHead3 minutes

Meal Prep Sunday

TaskTimeSaves Per Week
Chop vegetables20 minutes$10-20
Shred cheese5 minutes$2-3
Portion meat10 minutes$5-10
Total35 minutes$17-33

How to save money on groceries means spending a little time to save a lot of money.

For kitchen efficiency, seeย Passive Income Portfolio with $1,000ย (time-value-of-money concepts).

How to Save Money on Groceries: Tip 8

The eighth tip in how to save money on groceries is to stop buying beverages at the grocery store.

Beverages are among the highest-markup items in the grocery store. Water, soda, juice, and sports drinks cost pennies to produce and dollars to buy.

Beverage Savings

BeverageWeekly Cost (family of 4)Annual CostTap Alternative
Bottled water$10-20$520-1,040Tap water (filter if desired)
Soda$15-30$780-1,560Water with lemon or fruit
Juice$10-20$520-1,040Whole fruit + water
Sports drinks$10-15$520-780Water + pinch of salt

What to Drink Instead

Instead ofTry
Bottled waterTap water with a filter pitcher
SodaSparkling water with fruit
JuiceWhole fruit + water blended
Sports drinksWater with a pinch of salt and lemon

How to save money on groceries by eliminating beverages alone can save $1,000+ per year.

For health and budget benefits, seeย How to Survive the 2026 Cost of Living Crisis.

How to Save Money on Groceries: Tip 9

The ninth tip in how to save money on groceries is to eat less meat.

Meat is the most expensive item in most grocery carts. Reducing meat consumption by 2-3 meals per week can save significant money.

Meat vs. Plant-Based Protein Cost Comparison

Protein SourceCost per servingAnnual savings vs. beef
Beef$3.50-5.00–
Chicken$2.00-3.00$260-520
Pork$2.00-3.00$260-520
Eggs$0.50-1.00$650-1,040
Beans (dried)$0.20-0.50$780-1,170
Tofu$1.00-1.50$520-910
Lentils$0.30-0.60$754-1,144

Meatless Meal Ideas

MealCost per servingPrep Time
Bean burritos$1.5015 minutes
Lentil soup$1.0030 minutes
Egg fried rice$1.5020 minutes
Peanut butter sandwiches$0.755 minutes
Tofu stir-fry$2.0025 minutes

The 2-Day Meatless Rule

DayMealSavings vs. meat
MondayBeans and rice$3.00
ThursdayLentil soup$3.50
Weekly savings$6.50
Annual savings$338

How to save money on groceriesย does not require becoming a vegetarian. It requires being intentional about meat consumption.

For budget meal planning, see Best Budgeting Apps for Couples.

How to Save Money on Groceries: Tip 10

The tenth tip in how to save money on groceries is to never shop when hungry.

Shopping on an empty stomach is a guaranteed way to overspend. Everything looks good when you are hungry.

The Science Behind Hunger Shopping

FactorHungry ShopperFull Shopper
Impulse purchasesHighLow
Healthy choicesFewerMore
Average overspend30-50%5-10%
Store perimeter shoppingLessMore

How to Avoid Hunger Shopping

StrategyHow to Do It
Eat before you shopHave a snack or meal before leaving
Shop after a mealBest time is after lunch or dinner
Bring a water bottleSometimes thirst feels like hunger
Use grocery pickupNo store entry = no temptation

How to save money on groceries includes the simple strategy of eating before you shop.

For understanding impulse spending triggers, seeย How to Get Out of Credit Card Debt Fast When You Have No Money.

How to Save Money on Groceries: Tip 11

The eleventh tip in how to save money on groceries is to use the unit price to find the best deal.

The unit price tells you how much you are paying per ounce, pound, or liter. It is the only way to compare different package sizes.

How to Read the Unit Price

ItemPackage SizePriceUnit PriceBest Buy
Pasta16 oz$1.50$0.094/ozโœ…
Pasta32 oz$2.80$0.088/ozโœ…
Pasta48 oz$4.50$0.094/ozโŒ

Common Unit Price Mistakes

MistakeCorrect Approach
Assuming bigger is always cheaperCheck unit priceโ€”sometimes smaller packages are on sale
Ignoring the unit priceIt is on the shelf tag for a reason
Buying bulk you will not useIf it spoils, the unit price does not matter

When Bulk Buying Makes Sense

CategoryBuy in BulkDo Not Buy in Bulk
Dry goods (rice, beans, pasta)โœ…
Canned goodsโœ…
Frozen vegetablesโœ…
Fresh produceโŒ
DairyโŒ
Items you have not triedโŒ

How to save money on groceries requires reading the shelf tag, not just the price.

For tracking grocery spending, seeย Best Free Portfolio Trackers for Crypto and Stocks.

How to Save Money on Groceries: Tip 12

The twelfth tip in how to save money on groceries is to grow your own herbs and vegetables.

Even a small windowsill garden can save money on fresh herbs and salad greens.

What to Grow Indoors

PlantStart CostAnnual SavingsDifficulty
Basil$5 (seeds)$30-50Easy
Mint$5 (plant)$20-40Very easy
Green onions$2 (starts)$30-60Very easy
Lettuce$5 (seeds)$50-100Medium
Cherry tomatoes$10 (plant)$100-150Medium

What to Grow Outdoors (if you have space)

PlantStart CostAnnual SavingsDifficulty
Tomatoes$10$100-200Medium
Peppers$10$50-100Medium
Zucchini$5$50-100Easy
Herbs (variety)$20$100-150Easy

How to save money on groceries can include growing your own food with minimal investment.

For saving money across all areas, seeย How to Build an Emergency Fund from Scratch.

Weekly Meal Planning Template

How to save money on groceries starts with a plan.

Blank Weekly Meal Plan

DayBreakfastLunchDinnerLeftovers?
Monday
Tuesday
Wednesday
Thursday
Friday
Saturday
Sunday

Sample Low-Cost Weekly Meal Plan

DayBreakfastLunchDinnerCost Estimate
MondayOatmealLeftover dinnerBean burritos$8
TuesdayEggsSandwichesLentil soup$10
WednesdayOatmealLeftover soupRice and beans$6
ThursdayEggsSandwichesPasta with tomato sauce$8
FridayOatmealLeftover pastaEgg fried rice$9
SaturdayPancakesLeftover riceVegetable stir-fry$12
SundayOatmealSandwichesChicken and vegetables$15
Weekly total$68

How to save money on groceries is easier when you have a plan.

For more meal planning help, seeย How to Stop Living Paycheck to Paycheck.

How to Save Money on Groceries: Frequently Asked Questions

How much should a family of 4 spend on groceries?

A family of 4 should spend $800-1,200 per month on groceries in 2026. The USDA publishes monthly food cost reports showing thrifty ($800), low-cost ($1,000), moderate ($1,200), and liberal ($1,500+) options.

What is the best day to grocery shop for deals?

Wednesday is the best day to shop. Stores release new weekly ads on Wednesday. You get the best selection of sale items before weekend crowds. Also check Tuesday evenings for markdowns on meat and produce expiring soon.

How do I save money on groceries with a small budget?

Prioritize: (1) Plan meals around sale items, (2) Buy store brands, (3) Eat less meat, (4) Use grocery pickup to avoid impulse buys, (5) Cook from scratch. Start with the 12 tips above in order of easiest to hardest.

Is it cheaper to buy groceries online?

Using grocery pickup is often cheaper than in-store shopping because you avoid impulse purchases. Delivery services may add fees ($5-10) that offset savings. Pickup is free at most stores.

How do I save on groceries without clipping coupons?

(1) Buy store brands, (2) Shop at discount grocers (Aldi, Lidl), (3) Use grocery pickup, (4) plan meals around sales, and (5) Buy whole foods instead of pre-cut items. These strategies save as much as couponing without the time investment.

What grocery store is cheapest?

StoreRelative Cost
AldiLowest
LidlLowest
WalmartLow
KrogerMedium
SafewayMedium
Whole FoodsHigh

How to save money on groceries often starts with choosing the right store.

For more grocery savings, seeย How to Survive the 2026 Cost of Living Crisis.

For budgeting groceries, seeย Best Budgeting Apps for Couples.

For saving the difference, seeย Automated Savings Apps That Actually Work.

Your Action Plan for This Week

How to save money on groceries starts today.

Today (15 minutes)

ActionWhy
Check what food you already haveAvoid buying duplicates
Plan dinner for tonight using what you haveUse before it spoils
Eat before your next grocery tripAvoid hunger shopping

This Week (30 minutes)

ActionWhy
Plan all 7 dinners for next weekTip 1
Make a shopping list from your planTip 2
Choose store brands for 5 itemsTip 3

Next Week (1 hour)

ActionWhy
Try grocery pickup for your next shopTip 4
Download Ibotta and FetchTip 6
Buy one whole food instead of pre-cutTip 7

The Bottom Line

Grocery prices are up 25% since 2020. Fifty percent of Americans struggle to afford food. But how to save money on groceries is a skill you can learn.

TipPotential Monthly Savings
Meal planning$50-100
Store brands$30-80
Grocery pickup$40-100
Digital coupons$20-60
Whole foods over pre-cut$30-80
Reduce beverages$40-100
Eat less meat$20-50
Total possible savings$230-570

The difference between struggling and thriving at the grocery store is not income. It is a strategy.

Ready to save money on groceries? Download our grocery savings tracker or share this guide with someone who needs it.

How to Build an Emergency Fund from Scratch in 2026: 7-Step Plan

How to build an emergency fund from scratch in 2026: 7 steps showing set $500 goal, open high-yield savings account, start small with $5-20 per week, automate split direct deposit, find money leaks, use windfalls, and protect progress with 52% of Americans unable to cover $1,000 emergency

Why You Need an Emergency Fund More Than Ever in 2026

How to build an emergency fund from scratch has become the most important financial priority for Americans in 2026.

The numbers are alarming. According to the Federal Reserve’s May 2026 report,ย 52% of Americans cannot cover a $1,000 emergency expenseย from savings. Even more concerning,ย 64% of Americans live paycheck to paycheckโ€”meaning any unexpected cost can trigger a financial crisis.

How to build an emergency fund from scratch matters because life happens. Your car breaks down. Your refrigerator dies. You lose your job. Your child gets sick. Without savings, these normal life events become catastrophic.

The good news is that how to build an emergency fund from scratch is not complicated. It requires a plan, consistency, and patience. You do not need a high income. You need a system.

The 2026 Emergency Fund Reality

StatisticValue
Americans who cannot cover a $1,000 emergency52%
Americans living paycheck to paycheck64%
Average emergency expense$400-1,000
Time to build $1,000 saving $20/week50 weeks
Time to build $1,000 saving $50/week20 weeks

How to build an emergency fund from scratch is achievable even on a tight budget.

For understanding why you need this fund, seeย How to Survive the 2026 Cost of Living Crisis.

For managing financial anxiety while saving, seeย How to Stop Worrying About Money.

How to Build an Emergency Fund from Scratch: Step 1

The first step in how to build an emergency fund from scratch is to set a specific savings goal.

Most people fail because their goal is vague. “I want to save more money” is not a goal. “I will save $1,000 by December 31” is a goal.

The Three Emergency Fund Goals

GoalAmountTimeframePurpose
First buffer$50030-90 daysBreaks the paycheck cycle
One month of expenses$2,000-5,0006-12 monthsCovers job loss or major emergency
Three months of expenses$6,000-15,0001-2 yearsFull financial protection

How to build an emergency fund from scratch starts with the first $500. This is the most important goal because it changes your relationship with money.

Why $500 Changes Everything

Without $500 BufferWith $500 Buffer
Car repair equals panic.Car repair is annoyance.
Medical bill = sleepless nightsMedical bill = pay and rebuild
Late paycheck = overdraft feesLate paycheck = use buffer
Daily balance checking = anxietyWeekly checking = calm

Research in behavioral economics shows that a $500 liquid buffer reduces financial anxiety by 60-70%. Most emergencies cost less than $500.

How to Calculate Your Monthly Expenses

Expense CategoryYour Monthly Cost
Housing (rent/mortgage)$_____
Utilities (electric, water, internet)$_____
Food (groceries, not dining out)$_____
Transportation (gas, insurance, payment)$_____
Healthcare (insurance, medications)$_____
Minimum debt payments$_____
Total Monthly Expenses$_____

Once you know your monthly expenses, you know your emergency fund target.

How to build an emergency fund from scratch requires knowing the number.

For budgeting help, seeย Best Budgeting Apps for Couples.

How to Build an Emergency Fund from Scratch: Step 2

The second step in how to build an emergency fund from scratch is to open a separate high-yield savings account.

Keeping your emergency fund in your checking account is dangerous. You will spend it. Keeping it in a low-yield savings account at your regular bank means losing money to inflation.

Where to Put Your Emergency Fund

Account TypeProsConsBest For
High-yield savings4-5% APY, FDIC insured, liquidTakes 1-3 days to transferEmergency fund
Regular savings0.01-0.10% APYLosing value to inflationNot recommended
Money market accountHigher rates, check writingHigher minimumsLarger funds
CDsFixed ratesPenalty for early withdrawalNot for emergencies

Best High-Yield Savings Accounts in June 2026

BankAPYMinimumFeeBest For
SoFi4.5%$0$0Banking + savings
Ally Bank4.2%$0$0No minimums
Discover Bank4.3%$0$0Customer service
Capital One 3604.25%$0$0Large ATM network
CIT Bank4.8%$100$0Highest rate

How to build an emergency fund from scratch is easier when your money is growing faster than inflation.

How to Open an Account (15 Minutes)

StepAction
1Choose a bank from the list above
2Click “Open Account.”
3Provide your personal information
4Link your checking account
5Set up automatic transfer (Step 4)

For digital banking guidance, seeย Digital Banking vs Traditional Banking.

For automated savings features, seeย Automated Savings Apps That Actually Work.

How to Build an Emergency Fund from Scratch: Step 3

The third step in how to build an emergency fund from scratch is to start small and be consistent.

Do not wait until you have “extra money” to save. You will never have extra money. You have to prioritize saving before spending.

The 1% Rule

If saving a large amount feels impossible, start with 1% of your income.

Monthly Income1% Monthly Savings5% Monthly Savings10% Monthly Savings
$2,000$20$100$200
$3,000$30$150$300
$4,000$40$200$400
$5,000$50$250$500

How to build an emergency fund from scratch works at any percentage. 1% is better than 0%.

The 52-Week Savings Challenge

WeekSave This WeekTotal Saved
Week 1$1$1
Week 2$2$3
Week 3$3$6
………
Week 52$52$1,378

By the end of one year, you have saved $1,378 without ever saving more than $52 in a single week.

The Round-Up Method

PurchaseActual CostRounded UpSaved
Coffee$4.75Rounded to $5.00$0.25
Groceries$47.20Rounded to $48.00$0.80
Lunch$12.50Rounded to $13.00$0.50
Gas$38.15Rounded to $39.00$0.85
Daily Total$102.60Rounded to $105.00$2.40

Annual savings from round-ups alone: ~$876

How to build an emergency fund from scratch can be done with pocket change.

For round-up apps, seeย Automated Savings Apps That Actually Work.

How to Build an Emergency Fund from Scratch: Step 4

The fourth step in how to build an emergency fund from scratch is to automate your savings.

You intend to save. You know you should save. But between payday and the end of the month, the money disappears. Automation removes you from the decision.

The Automation Hierarchy

LevelMethodSuccess Rate
1Manual saving after expenses15%
2Manual saving on payday35%
3Automated transfer on payday70%
4Split direct deposit to savings85%
5Automated + percentage-based increase90%

How to Set Up Split Direct Deposit (15 Minutes)

StepAction
1Contact your employer’s payroll department
2Request a split direct deposit form
3Send 10-15% to your high-yield savings account
4Send the remainder to your checking account
5Never look at the savings account balance

How to build an emergency fund from scratch becomes automatic. You save what you never see.

Sample Split Direct Deposit on $4,000 Monthly Paycheck

AccountPercentageMonthly Amount
High-yield savings10%$400
Checking90%$3,600

After 3 months: $1,200 saved. You never noticed it missing.

For payroll setup guidance, seeย How to Stop Living Paycheck to Paycheck.

How to Build an Emergency Fund from Scratch: Step 5

The fifth step in how to build an emergency fund from scratch is to find money in your existing budget.

Most people have leaks they do not see. Plugging these leaks funds your emergency fund.

The 30-Day Spending Audit

WeekFocusAction
Week 1Track all spendingWrite down every purchase
Week 2Identify patternsFind subscriptions and small purchases adding up
Week 3CategorizeRent, utilities, groceries, dining, entertainment
Week 4AnalyzeWhere is your money actually going?

Common Money Leaks

Spending LeakTypical Monthly CostAnnual Cost
Unused subscriptions$50-150$600-1,800
Daily coffee shop$40-80$480-960
Food delivery fees$30-100$360-1,200
Impulse online purchases$50-200$600-2,400
Convenience store stops$20-60$240-720
Bank fees (overdraft, monthly)$10-50$120-600

The One-Cut Challenge

Pick ONE expense to cut this month. Redirect that money to your emergency fund.

CutMonthly SavingsEmergency Fund Impact
One streaming service$15$180/year
One meal out per week$40-80$480-960/year
Daily coffee$40-80$480-960/year
Bank fees$10-50$120-600/year

How to build an emergency fund from scratch does not require cutting everything. It requires cutting something.

For budgeting tools to find leaks, seeย Best Budgeting Apps for Couples.

For tracking spending, seeย Best Free Portfolio Trackers for Crypto and Stocks.

How to Build an Emergency Fund from Scratch: Step 6

The sixth step in how to build an emergency fund from scratch is to use windfalls and unexpected money.

Windfalls are perfect for emergency funds because you were not counting on that money anyway.

Types of Windfalls

Windfall TypeAverage AmountBest Use
Tax refund$1,500-3,000Emergency fund or debt
Work bonus$500-5,00080% to emergency fund
Gift money (birthday, holiday)$50-500100% to emergency fund
Side hustle income$50-500/month100% to emergency fund
Sold items (eBay, Facebook)$50-500100% to emergency fund
Cashback rewards$10-50/monthAdd to savings

The 80/20 Windfall Rule

PercentageUse
80%Emergency fund
20%Small reward for yourself

This balances progress with enjoyment.

Example: $2,000 Tax Refund

AllocationAmount
80% to emergency fund$1,600
20% to reward$400

You build your emergency fund while still enjoying the windfall.

How to build an emergency fund from scratch accelerates dramatically when you direct windfalls to savings.

For side hustle ideas to create more windfalls, seeย How to Get Out of Credit Card Debt Fast When You Have No Money.

For passive income, seeย Passive Income Portfolio with $1,000.

How to Build an Emergency Fund from Scratch: Step 7

The seventh step in how to build an emergency fund from scratch is to protect your progress.

You will face setbacks. The car will break. The roof will leak. The emergency fund is for emergencies.

What Is a Real Emergency?

ScenarioEmergency?Use Fund?
Car breaks down; need it for workโœ… YesYes
Unexpected medical billโœ… YesYes
Job lossโœ… YesYes
Sale on something you wantโŒ NoNo
Friend’s wedding travelโŒ NoNo
New phone because old is slowโŒ NoNo

The One-Month Rule

Before using your emergency fund for a non-emergency, wait 30 days.

DayAction
Day 1Want to spend the money
Day 7Still want it? Write down why.
Day 14Research alternatives
Day 21Can you get it cheaper?
Day 30If you still want it, save separately.

After 30 days, most urges pass.

How to Rebuild After an Emergency

StepAction
1Use emergency fund for true emergency
2Pause non-essential saving
3Redirect all extra money to rebuild fund
4Resume normal saving once fund is restored

Building an emergency fund from scratchย is not a one-time event. It is a cycle of building, using, and rebuilding.

For debt management while rebuilding, seeย How to Get Out of Credit Card Debt.

Where to Keep Your Emergency Fund in 2026

Understanding how to build an emergency fund from scratch includes knowing where to keep it.

The Three Rules for Emergency Fund Location

RuleWhy
LiquidYou can access it within 1-3 days
SafeNo risk of losing principal
SeparateNot in your checking account

Emergency Fund Comparison Table

Account Type Current APY Liquidity Risk Best For
High-Yield Savings 4.0-5.0% 1-3 days Very low Emergency fund
Money Market 4.0-4.5% Check writing Very low Larger funds
Regular Savings 0.01-0.10% Instant Very low Not recommended

How to build an emergency fund from scratch is best done in a high-yield savings account.

For bank comparisons, seeย Digital Banking vs Traditional Banking.

For protecting your savings, seeย Protect Your Brokerage Account from Hackers.

How to Build an Emergency Fund from Scratch: 90-Day Plan

How to build an emergency fund from scratch is a 90-day commitment.

Month 1: Foundation

WeekFocusActionTime
Week 1Set goalCalculate $500 target15 min
Week 2Open accountOpen high-yield savings15 min
Week 3Set automationSplit direct deposit (5% to savings)15 min
Week 4Find moneyDo 30-day spending audit1 hour

Month 1 Goal: $100-200 saved. Account open. Automation set.

Month 2: Momentum

WeekFocusActionTime
Week 5Increase savingIncrease split to 10%5 min
Week 6Find leaksCancel one unused subscription10 min
Week 7Use windfallsRedirect tax refund or bonus15 min
Week 8Side hustleStart one low-barrier side hustle2 hours

Month 2 Goal: $300-500 saved. First buffer achieved.

Month 3: Growth

WeekFocusActionTime
Week 9Increase againIncrease split to 15%5 min
Week 10Calculate expensesDetermine one-month expense target30 min
Week 11Side hustle incomeDirect 100% to savings2 hours
Week 12Celebrate$1,000 saved milestoneFree

Month 3 Goal: $800-1,000 saved. First $1,000 emergency fund complete.

Building an emergency fund from scratchย is achievable in 90 days with consistency.

For accountability, seeย Best Budgeting Apps for Couples.

For celebrating milestones, seeย How to Stop Worrying About Money.

How to Build an Emergency Fund from Scratch: Frequently Asked Questions

How much should I have in my emergency fund?

Start with $500. This covers the most common emergencies. Then build to one month of expenses ($2,000-5,000). Finally, build three months of expenses ($6,000-15,000). Financial experts recommend 3-6 months of expenses for full protection.

Where should I keep my emergency fund?

Keep your emergency fund in a separate high-yield savings account. Current rates are 4-5% APY. The account should be liquid (accessible in 1-3 days), safe (FDIC insured), and separate from your checking account.

How do I start an emergency fund with no money?

Start with $5 per week. Open a high-yield savings account with a $0 minimum. Set up an automatic transfer of $20 per month. Use round-up apps to save spare change. Sell unused items around your house. Every dollar counts.

How long does it take to build an emergency fund?

Saving $20/week builds $1,000 in 50 weeks. Saving $50/week builds $1,000 in 20 weeks. Saving $100/week builds $1,000 in 10 weeks. The key is consistency, not speed.

Should I pay off debt or build an emergency fund first?

Build a $500 emergency buffer first. Then split your extra money: 70% to high-interest debt (over 10%), 30% to an emergency fund. Once debt is gone, focus 100% on the emergency fund.

Can I use my emergency fund for non-emergencies?

No. Your emergency fund is for true emergencies only: job loss, medical emergencies, urgent car repairs, and emergency home repairs. Define “emergency” in writing before you need it.

What if I have to use my emergency fund?

That is what it is for. Use it. Then rebuild it. Pause non-essential saving. Redirect all extra money to rebuilding the fund. Once restored, resume normal saving.

How does the 2026 economy affect my emergency fund?

With inflation at 3.8% and economic uncertainty, an emergency fund is more important than ever. High-yield savings rates at 4-5% APY currently outpace inflation, making savings accounts attractive.

For more emergency fund strategies, seeย How to Stop Living Paycheck to Paycheck.

For debt payoff while saving, seeย How to Get Out of Credit Card Debt Fast When You Have No Money.

For long-term investing after your fund is built, seeย Passive Income Portfolio with $1,000.

Your Action Plan for This Week

How to build an emergency fund from scratch starts today.

Today (15 minutes)

ActionWhy
Open a high-yield savings accountChoose from list above
Set a $500 goalFirst milestone
Schedule $20 weekly transferStart small

This Week (30 minutes)

ActionWhy
Complete Week 1 of the 90-Day PlanFoundation
Contact HR for split direct deposit (5% to savings)Automate
Find one subscription to cancelRedirect savings

The Bottom Line

Fifty-two percent of Americans cannot cover a $1,000 emergency. Sixty-four percent live paycheck to paycheck. You do not have to be one of them.

How to build an emergency fund from scratch is not complicated:

StepAction
1Set a $500 goal
2Open a high-yield savings account
3Start with $5-20 per week
4Automate split direct deposit
5Find leaks in your budget
6Use windfalls for savings
7Protect your progress

The difference between those who have an emergency fund and those who do not is not income. It is a strategy.

Ready to build your emergency fund? Download our emergency fund tracker or share this guide with someone who needs it.

How to Stop Worrying About Money: 43% of Americans Feel This Way in 2026

How to stop worrying about money in 2026: 7 methods including separate facts from fear, build $500 buffer, automate finances, weekly money date, stop daily checking, worry budget, and talk openly about money

The 43% Crisis: Why Most Americans Worry About Money Every Week

How to stop worrying about money has become the most urgent mental health challenge for 43% of Americans.

According to The Penny Hoarder’s 2026 Financial Anxiety Barometer Report,ย 43% of Americans worry about their finances multiple times per week. This is not an occasional concern. This is chronic, draining anxiety that affects sleep, relationships, and work performance.

How to stop worrying about money matters because financial anxiety is not just about numbers. It is about your health. Studies show that persistent financial worry increases the risk of depression by 300%, heart disease by 40%, and divorce by 35%.

The problem is not your fault. The structural conditions of 2026 are creating unprecedented financial pressure.

The 2026 Financial Anxiety Numbers

MetricValueSource
Americans worrying weekly about finances43%Penny Hoarder 2026
Financial anxiety affects physical health38% report stress symptoms
Avoid opening bills or checking accounts29%
Financial stress impacts work performance34%
Avoid social activities to save money47%

How to stop worrying about money requires understanding that you are not alone. Nearly half of America is in the same boat.

For understanding the debt component of this anxiety, seeย How to Get Out of Credit Card Debt.

For breaking the paycheck cycle, seeย How to Stop Living Paycheck to Paycheck.

How to Stop Worrying About Money: 7 Science-Backed Methods

How to stop worrying about money requires behavioral change, not just better budgeting.

MethodFocusTime to See Results
1Separate facts from fearImmediate
2Build a $500 buffer30-90 days
3Automate your finances1 week
4Weekly 15-minute money date1 week
5Stop checking accounts daily1 day
6Create a worry budget1 hour
7Talk about money openlyOngoing

How to stop worrying about money is not about having more money. It is about changing your relationship with the money you have.

For automated solutions, seeย Automated Savings Apps That Actually Work.

For budgeting tools, seeย Best Budgeting Apps for Couples.

For debt-specific anxiety, seeย How to Get Out of Credit Card Debt.

Method 1: Separate Financial Facts from Emotional Fear

How to stop worrying about money starts with distinguishing what is real from what is feared.

The Cognitive Distortion Cycle

ThoughtDistortionReality Check
“I will never get out of debt”Fortune-tellingYou have paid off debt before. You can again.
“Everyone else has more money.”Comparison trap43% of Americans worry about money too.
“One emergency will ruin me.”CatastrophizingMost emergencies cost $400-1,000. You can plan.
“I am bad with money.”LabelingYou are learning. The past does not dictate the future.

The Facts vs. Feelings Exercise

StepActionExample
1Write down the anxious thought“I will never afford retirement”
2Identify the fear underneath“I am afraid of being old and broke”
3Find the factual counterpoint“I am 35. I have 30 years to save. Even $200/month grows to $228,000 at 7%.”
4Take one small action“I will increase my 401(k) by 1% tomorrow.”

How to stop worrying about money is not about eliminating fear. It is about not letting fear drive your decisions.

For retirement planning, seeย Robo-Advisors vs Human Advisors.

Method 2: Build a $500 Buffer to Eliminate Urgency Fear

How to stop worrying about money changes dramatically when you have a buffer.

Why $500 Changes Everything

Without BufferWith $500 Buffer
Car repair equals panic.Car repair is an annoyance.
Medical bill = sleepless nightsMedical bill = pay and rebuild
Late paycheck = overdraft feesLate paycheck = use buffer
Daily balance checking = anxietyWeekly checking = calm

The Fear Reduction Math

Research in behavioral economics shows that a $500 liquid buffer reduces financial anxiety by 60-70%. The reason is simple: most emergencies cost less than $500.

EmergencyAverage Cost
Car repair$350-500
Minor medical visit$150-300
Appliance replacement$200-400
Unexpected bill$100-250

How to stop worrying about money starts with the peace of knowing you can handle most emergencies.

How to Build Your Buffer Fast

MethodTimeAction
One-time boost1 monthTax refund, bonus, sell items
Weekly savings10 weeksSave $50/week
Daily savings50 daysSave $10/day
Reduce expenses2-3 monthsCut $100-200/month

For saving tools, seeย Automated Savings Apps That Actually Work.

Method 3: Automate Your Finances to Remove Daily Decisions

How to stop worrying about money requires removing yourself from daily financial decisions.

The Decision Fatigue Problem

Without AutomationWith Automation
Decide to save each monthSavings happens automatically
Remember to pay each billBills pay automatically
Transfer money to savingsSplit direct deposit
Log in to check balancesMonthly summary only

What to Automate

ItemHow to AutomateTime Saved Per Month
Bill paymentsAuto-pay from checking2 hours
SavingsSplit direct deposit1 hour
InvestmentsAuto-invest into 401(k), IRA1 hour
Debt paymentsAuto-pay above minimum30 minutes
Total4.5 hours of decision-making

How to stop worrying about money works when you stop making daily choices about money. The system runs without you.

The 15-Minute Setup

DayActionTime
1Log in to your bank and set up auto-pay for all bills15 minutes
2Contact HR to split direct deposit (10-15% to savings)10 minutes
3Set up auto-invest for retirement account10 minutes
4Set up auto-pay for credit cards (minimum or fixed amount)10 minutes

Total time to automate your entire financial life: 45 minutes.

For automation tools, seeย Automated Savings Apps That Actually Work.

Method 4: Schedule a Weekly 15-Minute “Money Date.”

How to stop worrying about moneyย is counterintuitive: worrying less requires looking at your money moreโ€”but only on a schedule.

Why a Weekly Money Date Works

Without ScheduleWith Weekly Date
Worry daily about unknownCheck once and know everything
Avoid bills, make anxiety worseFace finances, reduce fear
Sporadic checking misses issuesRegular review catches problems early
No dedicated time = never happens15 minutes on calendar = done

The 15-Minute Money Date Agenda

MinuteActivity
0-2Open accounts, take a breath
2-5Check balances (no judgment, just observation)
5-8Pay all pending bills
8-10Review spending against budget
10-12Check progress toward goals (buffer, debt, savings)
12-14Adjust upcoming week’s spending plan
14-15Close accounts, thank yourself, move on

The Most Important Rule

Do not check your money on any other day.

The weekly money date contains your financial anxiety in one 15-minute container. The rest of the week, you trust the system.

How to stop worrying about money is about containment, not elimination.

For couples doing this together, seeย Best Budgeting Apps for Couples.

Method 5: Stop Checking Your Bank Account Multiple Times Per Day

How to stop worrying about money requires breaking the checking habit.

The Checking Addiction

Checking FrequencyAnxiety Level
Multiple times per dayHigh (constant reinforcement of fear)
Once per dayMedium
2-3 times per weekLow
Weekly (money date only)Lowest

Why Checking Makes Anxiety Worse

Psychological EffectWhat Happens
Hyper-vigilanceYour brain stays on alert for threats
False pattern recognitionYou see “problems” that are not there
Small fluctuations feel catastrophicA $50 dip becomes a crisis
No time for perspectiveYou react to today, not the trend

The 30-Day Checking Reduction Plan

WeekAllowed ChecksTrick
Week 13 times per dayDelete banking apps from phone home screen
Week 22 times per dayLog out after each check
Week 31 time per dayCheck only on the computer, not a phone.
Week 43 times per weekSchedule specific times

How to stop worrying about money means trusting that the money will be there without constant surveillance.

For digital banking management, see Digital Banking vs Traditional Banking.

Method 6: Create a “Worry Budget” for Financial Fears

How to stop worrying about money requires giving anxiety a container.

What Is a Worry Budget?

A worry budget is a scheduled time to write down your financial fears without trying to solve them. The act of externalizing worry reduces its power.

The Worry Budget Template

DayTimeActivity
Sunday10 minutesWrite down all money worries for the week
Wednesday5 minutesReview and note which worries came true (almost none will)

What to Write

PromptExample
What am I afraid will happen?“I am afraid my car will break down and I cannot fix it.”
What evidence supports this fear?“My car has 150,000 miles and makes a noise.”
What evidence contradicts this fear?“My car passed inspection last month. I have $400 saved.”
What is one small action I can take?“Get the noise checked next week. Cost $50.”

Why This Works

Psychological PrincipleEffect
ExternalizationWriting moves worry from brain to paper
ContainmentWorry happens only in budget time
Reality testingMost predicted disasters never occur
Action orientationWorry becomes plan, not paralysis

How to stop worrying about money is not about pretending everything is fine. It is about processing fear constructively.

For financial planning to address actual risks, seeย Passive Income Portfolio with $1,000.

Method 7: Talk About Money Openly (It Reduces Anxiety by 40%)

It’s impossible to stop worrying about moneyย when money is a secret.

The Shame Spiral

Secrecy CycleOpenness Cycle
Feel shame about moneyFeel normal about money
Hide from partner/friendsShare with trusted people
Anxiety grows aloneAnxiety shared = anxiety halved
Avoid helpReceive support

Research on Financial Openness

Studies show that couples who talk about money openly have

MetricImprovement
Financial anxiety40% lower
Relationship satisfaction35% higher
Debt payoff speed30% faster
Savings rate25% higher

How to Start the Conversation

Script for PartnerScript for Friend/Family
“I have been feeling anxious about money. Can we talk about our finances together?”“I am working on my financial anxiety. Can I share what I am learning?”
“I want us to have a weekly money date. Are you open to that?”“How do you handle money stress? I am trying to get better at it.”
“I am struggling with [specific fear]. Can we make a plan together?”“I read that 43% of Americans worry about money weekly. That helped me feel less alone.”

How to stop worrying about moneyย becomes easier when you realize everyone else is worried, too.

For couples budgeting together, seeย Best Budgeting Apps for Couples.

How to Stop Worrying About Money: The 30-Day Anxiety Reduction Plan

How to stop worrying about money is a 30-day practice, not a one-time fix.

Week 1: Awareness

DayActionTime
1Write down every money worry that comes upAll day (capture)
2Categorize worries: real vs. feared15 minutes
3Share one worry with a trusted person10 minutes
4Delete banking apps from phone home screen5 minutes
5Check accounts only once todayAll day
6Complete Facts vs. Feelings exercise20 minutes
7Create worry budget template15 minutes

Week 2: Action

DayActionTime
8Set up bill auto-pay15 minutes
9Contact HR for split direct deposit (5% to savings)10 minutes
10Schedule weekly money date (every Sunday at 7 PM)5 minutes
11Reduce account checking to 3 times this weekAll week
12Write worries in budget, not in your head10 minutes
13Check progress on $500 buffer5 minutes
14Celebrate one week of reduced checkingFree

Week 3: Automation

DayActionTime
15Increase split direct deposit to 10%5 minutes
16Set up auto-pay for credit cards10 minutes
17Set up auto-invest for retirement15 minutes
18Reduce account checking to 2 times this weekAll week
19Use worry budget for all fears10 minutes
20Have money conversation with partner20 minutes
21Check buffer progress ($250 milestone?)5 minutes

Week 4: Momentum

DayActionTime
22Reduce account checking to 1 time this weekAll week
23Increase savings to 15% if buffer complete5 minutes
24Complete first weekly money date15 minutes
25Write down worries that came true (likely zero)5 minutes
26Share progress with accountability partner10 minutes
27Plan month 2 goals15 minutes
28Celebrate 30 days of reduced anxietyFree

How to stop worrying about money is a skill. Like any skill, it improves with practice.

For ongoing support, seeย Best Budgeting Apps for Couplesย (if you have a partner).

How to Stop Worrying About Money: Frequently Asked Questions

Is financial anxiety normal in 2026?

Yes.ย 43% of Americans worry about money multiple times per week. You are not broken. You are responding to real economic pressure: inflation at 3.8%, wage growth at 3.6%, and credit card delinquencies at a 15-year high.

How can I stop worrying about money when I have real problems?

How to stop worrying about money is not about pretending problems do not exist. It is about separating what you can control from what you cannot. Use the Facts vs. Feelings exercise (Method 1). Build a buffer (Method 2). Automate what you can (Method 3). Take action on what you can control. Release what you cannot.

What if I cannot build a $500 buffer?

Start with $50. Or $20. Or $5. The peace comes from progress, not perfection. Every dollar in your buffer reduces anxiety more than the dollar before.

How do I talk to my partner about money anxiety?

Use “I” statements: “I have been feeling anxious about money. ” I want us to work on this together. Can we have a weekly money date? ” Avoid blame. Assume good intentions.ย How to stop worrying about moneyย as a couple is easier than alone.

Will financial anxiety ever go away completely?

No. Money will always matter. But how to stop worrying about money means moving from daily, debilitating anxiety to occasional, manageable concern. The goal is not zero worry. The goal is worry that does not control your life.

What if I try these methods and still feel anxious?

Financial anxiety can be a symptom of generalized anxiety disorder or depression. If these methods do not help after 90 days, consider speaking with a therapist. There is no shame in professional support.

For professional financial guidance, seeย Robo-Advisors vs Human Advisors.

For mental health resources, consider speaking with a licensed therapist.

Your Action Plan for Today

How to stop worrying about money starts with one small action.

Right Now (15 minutes)

ActionWhy
Write down your biggest money fearExternalizing reduces power
Check if you can take one small action todayAction reduces anxiety
Schedule your first weekly money date (Sunday at 7 PM)Containment starts this week

This Week (30 minutes)

ActionWhy
Complete Week 1 of the 30-Day PlanBuild awareness
Delete banking apps from home screenBreak the checking habit
Tell one person you are working on financial anxietyShare the burden

This Month

ActionWhy
Complete all 4 weeks of the 30-day plan.Build new habits
Build $100 toward your bufferProgress, not perfection
Attend every weekly money dateConsistency wins

The Bottom Line

43% of Americans worry about money every week. You are not alone. You are not broken. And you can change your relationship with money.

How to stop worrying about moneyย is not about having more. It is about needing less money to feel safe.

Ready to stop worrying about money? Download our financial anxiety workbook or share this guide with someone who needs it.

How to Stop Living Paycheck to Paycheck in 2026: 7 Steps That Work

How to stop living paycheck to paycheck in 2026: 7 steps showing calculate real wage, track spending, zero-based budget, build $500 buffer, automate savings, reduce expenses, and increase income with side hustles

Why 64% of Americans Live Paycheck to Paycheck Right Now

How to stop living paycheck to paycheck is the most urgent financial question for 64% of Americans.

According to the Federal Reserve’s May 2026 Survey of Household Economics, 64% of adults say they live paycheck to paycheckโ€”meaning they would struggle to cover a $400 emergency expense. This number has barely budged since 2021, despite inflation cooling to 2.8%.

How to stop living paycheck to paycheck 2026 infographic showing paycheck cycle break, $500 buffer goal, automated savings, and 7 steps from zero-based budget to emergency fund

How to stop living paycheck to paycheck matters because the traditional advice is failing. “Cut out lattes” does not work when rent takes 50% of your income. “Make a budget” does not work when you have nothing left after bills.

The problem is structural. Wages have increased 18% since 2020. Housing costs have increased 35%. Food is up 25%. Transportation is up 20%. The gap is widening.

How to stop living paycheck to paycheck requires a different approachโ€”not deprivation, but systems.

For tracking your progress, see Best Free Portfolio Trackers for Crypto and Stocks.

The May 2026 Reality by the Numbers

MetricValueChange from 2020
Americans living paycheck to paycheck64%+8%
Median rent (US)$2,050/month+35%
Average grocery bill (family of 4)$1,200/month+25%
Average new car payment$740/month+22%
Hourly wage growth$32.50+18%

How to stop living paycheck to paycheck requires acknowledging that expenses have grown faster than income for most Americans.

For budgeting tools to help, see Best Budgeting Apps for Couples.

How to Stop Living Paycheck to Paycheck: The 7-Step Framework

How to stop living paycheck to paycheck is not one action. It is a system.

StepFocusTime to Complete
1Calculate your real hourly wage1 hour
2Track every dollar for 30 days30 days (10 min/day)
3Create a zero-based budget2 hours
4Build a $500 buffer30-90 days
5Automate your savings1 hour
6Reduce three biggest expenses1-3 months
7Increase incomeOngoing

How to stop living paycheck to paycheck is a marathon, not a sprint. But each step builds momentum.

For savings automation, see Automated Savings Apps That Actually Work.

For emergency fund building, see Passive Income Portfolio with $1,000.

Step 1: Calculate Your Real Hourly Wage (It Is Lower Than You Think)

How to stop living paycheck to paycheck starts with honesty about your time.

Most people calculate their hourly wage as annual salary / 2,080 hours. But that ignores commute time, unpaid breaks, work travel, and overtime without extra pay.

The Real Hourly Wage Formula

StepCalculationExample
1Start with annual salary$50,000
2Add hours worked per week (including unpaid overtime)45 hours
3Add weekly commute time10 hours
4Add weekly work-related tasks (emails, prep)5 hours
5Total weekly time60 hours
6Real hourly wage = salary / (hours ร— 52)$50,000 / (60 ร— 52) = $16.03

How to stop living paycheck to paycheck using real hourly wages reveals:

Nominal Hourly WageReal Hourly Wage (with 60-hour week)Difference
$25$16.03-36%
$35$22.44-36%
$50$32.05-36%

Why This Matters for How to Stop Living Paycheck to Paycheck

When you see your real hourly wage, spending decisions change:

PurchaseHours of Work (Nominal $25/hr)Hours of Work (Real $16/hr)
$4 coffee10 minutes15 minutes
$50 dinner out2 hours3 hours
$500 new phone20 hours31 hours
$1,000 rent40 hours62 hours

How to stop living paycheck to paycheck becomes easier when you connect spending to real time, not money.

For time tracking tools, see AI Budget Trackers for Freelancers.

Step 2: Track Every Dollar for 30 Days Without Judgment

How to stop living paycheck to paycheck requires knowing where your money actually goes.

Most people guess. They are wrong. Studies show people underestimate discretionary spending by 30-50%.

The 30-Day Spending Tracking Method

WeekFocusAction
Week 1Track all spendingWrite down or use app for every purchase
Week 2Identify patternsLook for surprises (subscriptions, small purchases adding up)
Week 3CategorizeRent, utilities, groceries, dining, entertainment, etc.
Week 4AnalyzeWhere is your money actually going?

Free Tracking Tools

ToolPriceBest For
EveryDollar (free version)FreeManual entry, Ramsey method
GoodbudgetFree for 20 envelopesEnvelope system
Pen and paperFreeNo app distraction
Spreadsheet (Excel/Google Sheets)FreeCustom categories

What You Will Discover

Common SurpriseTypical AmountAction
Subscription services$50-150/monthCancel unused
Food delivery fees$30-100/monthCook one more meal a week.
Impulse Amazon purchases$50-200/month24-hour rule
Convenience store stops$20-60/monthPlan ahead

How to stop living paycheck to paycheck starts with awareness. You cannot fix what you do not measure.

For automatic tracking, see Automated Savings Apps That Actually Work.

Step 3: Create a Zero-Based Budget That Works for Irregular Income

How to stop living paycheck to paycheck requires a budget that assigns every dollar a job.

Zero-based budgeting means income minus expenses minus savings minus giving equals zero.

Zero-Based Budget Template

CategoryPercentage of IncomeExample ($4,000/month)
Housing (rent/mortgage)30-35%$1,200-1,400
Utilities (electric, water, internet, phone)8-10%$320-400
Food (groceries, not dining)10-15%$400-600
Transportation (car payment, gas, insurance)10-15%$400-600
Insurance (health, life, renters)5-10%$200-400
Minimum debt payments5-10%$200-400
Savings (emergency fund first)10-15%$400-600
Personal (clothing, entertainment, dining)5-10%$200-400
Total100%$4,000

How to Budget for Irregular Income

If you are paid weekly, bi-weekly, or irregularly:

StrategyHow It Works
Base budget on lowest monthBudget for your smallest paycheck, not average
Use a buffer accountHold excess from high months to cover low months
Prioritize essentials firstRent, utilities, groceries before anything else
Percentage-based categories50% needs, 30% wants, 20% savings (after buffer)

How to stop living paycheck to paycheck requires a budget that fits your income pattern, not a generic template.

For budgeting apps for couples, see Best Budgeting Apps for Couples.

Step 4: Build a $500 Buffer to Break the Cycle First

How to stop living paycheck to paycheck requires breaking the timing mismatch.

Living paycheck to paycheck means your bills come due before your next paycheck. A $500 buffer breaks this cycle.

Why $500 Works

Without BufferWith $500 Buffer
The paycheck arrivesThe paycheck arrives
Pay all bills immediatelyBills are already covered
Nothing left for 14 daysSurplus builds
Emergency = debtEmergency = buffer

How to Build a $500 Buffer

MethodTimeAction
One-time boost1 monthTax refund, bonus, side hustle
Weekly savings10 weeksSave $50/week
Daily savings50 daysSave $10/day
Expense reduction2-3 monthsCut $100-200/month

Where to Keep Your Buffer

Account TypeBest For
High-yield savings (separate from checking)Not tempted to spend
Dedicated checking accountBills only
Envelope of cashVisual motivation

How to stop living paycheck to paycheck physically changes when you have a buffer. You stop timing your payments. You stop calculating if you can afford groceries. You just live.

For high-yield savings options, see Digital Banking vs Traditional Banking.

For automated saving, see Automated Savings Apps That Actually Work.

Step 5: Automate Your Savings Before You See the Money

How to stop living paycheck to paycheck requires removing your own decision-making from saving.

You intend to save. You know you should save. But between payday and the end of the month, the money disappears.

The Automation Hierarchy

LevelActionEffectiveness
1Manual saving after expenses15% success
2Manual saving on payday35% success
3Automated transfer on payday70% success
4Split direct deposit to savings85% success
5Automated + percentage-based increase90% success

How to Set Up Split Direct Deposit

StepAction
1Contact your employer’s payroll department
2Request a split direct deposit form
3Send 10-15% to a separate savings account
4Send the remainder to checking
5Never look at the savings account

How to stop living paycheck to paycheck becomes automatic. You save what you never see.

Savings Goals for Paycheck-to-Paycheck Breakers

GoalAmountTimeframe
First buffer$50030-90 days
One month of expenses$2,000-5,0006-12 months
Three months of expenses$6,000-15,0001-2 years

For savings automation tools, see Automated Savings Apps That Actually Work.

Step 6: Reduce the Three Biggest Budget Busters

How to stop living paycheck to paycheck requires focusing on big wins, not small cuts.

The three largest expenses for most Americans are the following:

CategoryAverage Monthly CostTypical Savings Opportunity
Housing (rent/mortgage)$2,050$200-500
Transportation (car payment, gas, insurance)$1,100$150-400
Food (groceries + dining)$1,000$150-300
Total potential savings$4,150$500-1,200

Housing Savings Strategies

StrategyPotential SavingsEffort
Get a roommate$500-1,000/monthMedium
Negotiate rent renewal$100-200/monthLow
Move to less expensive area$200-500/monthHigh
Rent out parking or storage$50-150/monthLow

Transportation Savings Strategies

StrategyPotential SavingsEffort
Shop car insurance (every 6 months)$200-600/yearLow
Refinance auto loan (if credit improved)$50-150/monthMedium
Reduce driving (combine trips, transit)$50-100/monthLow
Sell a car with high payment and buy used one$200-500/monthHigh

Food Savings Strategies

StrategyPotential SavingsEffort
Meal plan weekly$50-100/monthMedium
Shop sales and use coupons$30-80/monthLow
Reduce dining out by one meal/week$40-100/monthMedium
Buy store brands$20-50/monthLow
Use grocery pickup (avoid impulse buys)$30-60/monthLow

How to stop living paycheck to paycheck targets the biggest expenses first. Saving $10 on coffee is good. Saving $200 on rent is transformative.

For budgeting groceries, see Best Budgeting Apps for Couples.

Step 7: Increase Income with Low-Barrier Side Hustles

How to stop living paycheck to paycheck has a limit on cutting expenses. You cannot cut your way to zero.

The other side of the equation is income.

Low-Barrier Side Hustles (Start Within 1 Week)

Side HustleStartup CostMonthly PotentialTime Required
Freelance writing (Upwork, Fiverr)$0$200-1,0005-10 hours/week
Virtual assistant$0$300-1,50010-15 hours/week
Pet sitting/walking (Rover, Wag)$0$200-6005-10 hours/week
Food delivery (DoorDash, UberEats)$0$400-80010-15 hours/week
Online tutoring (TutorMe, Wyzant)$0$300-1,0005-10 hours/week
User testing (UserTesting)$0$100-3005 hours/week
Sell unused items (eBay, Facebook Marketplace)$0$100-1,000 one-time2-5 hours

Higher-Barrier Side Hustles (Longer Setup)

Side HustleStartup CostMonthly PotentialSetup Time
Affiliate marketing website$50-100/year$500-5,0003-6 months
Print on demand (Redbubble, Merch by Amazon)$0$100-1,0001-2 months
Digital products (Notion templates, spreadsheets)$0$200-2,0001-2 months
Bookkeeping for small businesses$200 (software)$500-2,0001 month

How to Use Extra Income to Stop Living Paycheck to Paycheck

Extra Income AmountBest Use
First $500Build buffer (Step 4)
Next $1,000Pay off high-interest debt
Next $2,000-5,000Build 1-month emergency fund
BeyondInvest (see Passive Income Portfolio with $1,000)

How to stop living paycheck to paycheck becomes sustainable when income exceeds expenses by 10-20%.

For side hustle ideas, see AI Budget Trackers for Freelancers.

For passive income, see Passive Income Portfolio with $1,000.

How to Stop Living Paycheck to Paycheck: Sample 90-Day Timeline

How to stop living paycheck to paycheck is achievable in 90 days with focus.

Month 1: Foundation

WeekFocusAction
Week 1Calculate real wage and track spendingSet baseline
Week 2Continue tracking and identify budget bustersFind leaks
Week 3Create zero-based budgetPlan every dollar
Week 4Open separate savings accountPrepare for automation

Month 1 Goal: Know exactly where your money goes. Have a budget that works for your income pattern.

Month 2: Build Buffer

WeekFocusAction
Week 5Reduce top 3 expensesHousing, transportation, food
Week 6Start side hustleAdd $100-200/week
Week 7Automate split direct deposit10% to savings
Week 8Reach $500 bufferBreak the cycle

Month 2 Goal: $500 buffer. Automated savings. Reduced fixed expenses.

Month 3: Expand

WeekFocusAction
Week 9Increase savings to 15%Adjust direct deposit
Week 10Pay down high-interest debtSnowball or avalanche
Week 11Build 1-month emergency fund$2,000-5,000
Week 12Plan next 90 daysSet new goals

Month 3 Goal: One month of expenses saved. Debt reduced. System automated.

How to stop living paycheck to paycheck is not about perfection. It is about progress.

For accountability, see Best Budgeting Apps for Couples (if you have a partner).

How to Stop Living Paycheck to Paycheck: Frequently Asked Questions

How long does it take to stop living paycheck to paycheck?

Most people can build a $500 buffer in 30-90 days. Building a full emergency fund takes 6-12 months. The 7-step framework above provides a 90-day timeline for breaking the immediate cycle.

What if I have irregular income (freelance, commission)?

How to stop living paycheck to paycheck with irregular income requires a different approach: base your budget on your lowest month, build a larger buffer (1-2 months of expenses), and use percentage-based categories (50/30/20) rather than fixed dollar amounts.

How much should I save before I stop living paycheck to paycheck?

GoalAmountPriority
First buffer$500Highest (breaks the cycle)
1 month’s expenses$2,000-5,000Second
3 months’ expenses$6,000-15,000Third
6 months’ expenses$12,000-30,000Fourth

Can I stop living paycheck to paycheck on a low income?

Yes. The steps work at any income level. However, if your basic expenses (housing, utilities, food, transportation) exceed your income, you must either reduce expenses (Step 6) or increase income (Step 7). There is no magic solution when math does not work.

What is the most common mistake people make?

Trying to cut too much too fast. Deprivation leads to bingeing. How to stop living paycheck to paycheck works when you automate savings (Step 5) and focus on big wins (Step 6) rather than tiny cuts.

Do budgeting apps actually help?

Yes. People who use budgeting apps save 15-20% more than those who do not. The key is consistency. How to stop living paycheck to paycheck with an app is easier than with spreadsheets.

For app recommendations, see Best Budgeting Apps for Couples.

For automated savings, see Automated Savings Apps That Actually Work.

For building wealth after breaking the cycle, see Passive Income Portfolio with $1,000.

Your 30-Day Action Plan to Stop Living Paycheck to Paycheck

How to stop living paycheck to paycheck is not knowledge. It is action.

Week 1: Awareness (30 minutes/day)

DayActionTime
1Calculate your real hourly wage1 hour
2Download a spending tracker app10 minutes
3List all recurring subscriptions20 minutes
4Review bank statements for the last 3 months30 minutes
5Identify top 3 spending categories20 minutes
6Cancel unused subscriptions15 minutes
7Create zero-based budget for next month1 hour

Week 2: Buffer Building (15 minutes/day)

DayActionTime
8Open separate high-yield savings account15 minutes
9Set up split direct deposit (5% to savings)15 minutes
10Reduce one budget buster (call insurance, etc.)30 minutes
11List items to sell on Facebook Marketplace20 minutes
12Post 3 items for sale15 minutes
13Pick a side hustle and sign up30 minutes
14Complete first side hustle task1 hour

Week 3: Automation (15 minutes/day)

DayActionTime
15Increase split direct deposit to 10%10 minutes
16Set up automatic bill pay for all fixed expenses20 minutes
17Download an authenticator app for brokerage security10 minutes
18Review insurance policies (auto, home, renters)30 minutes
19Negotiate one recurring bill15 minutes
20Meal plan for next week30 minutes
21Cook one extra meal at home instead of dining out1 hour

Week 4: Momentum (15 minutes/day)

DayActionTime
22Check buffer progress ($500 reached?)5 minutes
23Increase savings to 15% if buffer complete10 minutes
24Refer a friend to your side hustle platform10 minutes
25Review month 1 spending vs. budget30 minutes
26Adjust budget for month 220 minutes
27Celebrate progress (free activity)2 hours
28Plan month 2 goals30 minutes

How to stop living paycheck to paycheck is a 30-day start, not a finish line.

Ready to break the cycle? Download our 90-day paycheck-to-paycheck workbook or share this guide with someone who needs it.

Open Banking Explained: Your Bank Data Is Not Safe in 2026

Open banking explained data flow diagram showing how your bank data moves from your bank to aggregators like Plaid to third-party apps like budgeting and lending platforms

Open Banking Explained: The Silent Takeover of Your Financial Data

Open banking explained starts with an uncomfortable truth: your bank data is already being shared without your full understanding.

Every time you connect a budgeting app to your checking account, use “pay with bank” at checkout, or apply for a loan through a fintech platform, you are participating in open banking. Open banking, simply explained, means allowing third-party apps to access your financial data through secure APIs.

The numbers are staggering. According to a May 2026 report by Plaid, 89% of Americans now use at least one fintech app that connects to their bank account. The average connected consumer has 6 apps linked to their financial data.

Open banking explained is not a future trend. It is happening right now. And most people have no idea who has access to their account balances, transaction history, or even their social security number.

Open banking matters because your financial data is among the most sensitive information you own. Unlike a stolen password, you cannot change your transaction history.

For managing your connected finances, see Best Free Portfolio Trackers for Crypto and Stocks.

What Is Open Banking? A Simple Definition

Open banking explained data flow diagram showing how your bank data moves from your bank to aggregators like Plaid to third-party apps like budgeting and lending platforms

Open banking explained in one sentence: Open banking is a system that allows third-party financial service providers to access your banking data through secure application programming interfaces (APIs) with your permission.

The Traditional Way vs. Open Banking

Traditional BankingOpen Banking
Your data stays inside your bankYour data can be shared with approved apps
You cannot use budgeting apps that auto-syncApps like Mint, YNAB, and Rocket Money work seamlessly
Applying for a loan requires manual paperworkLenders can verify income instantly
Switching banks is difficultAccount aggregation shows all accounts in one place

Open banking explained is the technology behind every financial app that shows your account balance without logging into your bank.

The Key Players in Open Banking

PlayerRole in Open Banking
You (the consumer)Own the data and give permission
Your bankHolds the data and provides API access
Third-party appRequests access to provide a service
RegulatorSets rules for how data can be shared

Open banking explained puts you in controlโ€”at least in theory.

For budgeting apps that rely on open banking, see Best Budgeting Apps for Couples.

Open Banking Explained: How Third-Party Apps Access Your Accounts

Open banking explained requires understanding the technology behind it.

The Old Way: Screen Scraping

Before open banking, apps used a risky method called screen scraping. The app stored your bank username and password, then “scraped” data from the bank’s website as if it were you logging in.

Problem with Screen ScrapingWhy It Was Dangerous
Apps stored your login credentialsData breaches exposed usernames and passwords
Violated bank terms of serviceNo fraud protection if something went wrong
No visibility into what data was accessedApps could take more than they needed
Credentials could be used maliciouslyThere is no way to revoke access without changing the password

Open banking explained replaced screen scraping with secure APIs.

The New Way: API-Based Access

Feature of API AccessWhat It Means for You
No password sharingYou authenticate directly with your bank
Granular permissionsApps only see what you approve
Read-only accessApps cannot move money
Revocable tokensYou can cut off access instantly

Open banking explained through APIs is far safer than the screen scraping era. But risks remain.

For security best practices, see Cybersecurity for Investors: Protecting Your Brokerage Accounts (coming soon).

The Benefits of Open Banking: Why Apps Want Your Data

Open banking explained is not all bad. There are genuine benefits that explain why 89% of Americans use connected apps.

Benefit #1: Budgeting That Actually Works

Without Open BankingWith Open Banking
Manually enter every transactionAutomatic syncing of all accounts
Spending reports take hoursReal-time categorization
You forget purchasesEvery transaction captured
Budgeting feels like homeworkBudgeting happens automatically

Benefit #2: Faster Loan Approvals

Open banking explained in lending: Instead of uploading pay stubs and bank statements, you can give lenders secure access to verify your income and spending in minutes.

Time saved: Days or weeks reduced to minutes.

Benefit #3: Account Aggregation

See all your bank accounts, credit cards, investments, and loans in one dashboard. Open banking explained makes this possible without logging into eight different websites.

Benefit #4: Better Fraud Detection

When your bank sees spending patterns across multiple apps, fraud detection improves. Unusual activity flagged faster.

Benefit #5: Easier Account Switching

Open banking explained for switching banks: your new bank can automatically transfer your direct deposits, bill payments, and transaction history.

For maximizing these benefits safely, see Digital Banking vs Traditional Banking.

Open Banking Explained: The Hidden Risks to Your Privacy

Open banking explained must include the dangers. Here is what the apps do not tell you.

Risk #1: Data Brokers Are Buying Your Transaction History

A May 2026 investigation by The Markup found that major data brokers are purchasing anonymized bank transaction data from open banking aggregators.

Even “anonymized” data can be re-identified. Researchers have shown that with just four transaction locations and approximate amounts, they could identify 90% of individuals in a dataset.

Open banking explained means your grocery purchases, rent payments, and even doctor visit copays are being sold to advertisers.

Risk #2: Apps Are Collecting More Data Than They Need

What You Think They SeeWhat They Actually Collect
Your account balanceFull transaction history for 24+ months
Spending categoriesMerchant names, locations, and amounts
Income depositsPayroll details and employer name
Connected accountsData from every linked financial account

Open banking explained includes the uncomfortable reality that most privacy policies grant apps far more access than required.

Risk #3: Data Breaches Expose Financial Histories

YearBreachData Exposed
2024Plaid settlementMillions of users’ bank login data collected without consent
2025Tink breachTransaction histories of 500,000+ European users
2026Finicity incidentAPI credentials exposed for 72 hours

“Open banking explained” means your data is only as secure as the weakest app you connect.

Risk #4: You Cannot Delete Your Data

Even after disconnecting an app, most retain your transaction history indefinitely. Their privacy policies permit using “de-identified” data for product improvement and resale.

Open banking explained reveals that permission is often one-way. You can stop sharing new data, but old data remains.

Risk #5: Third-Party Apps Can Make Mistakes

In 2025, a popular budgeting app incorrectly categorized thousands of rent payments as “”gambling”โ€”affecting users’ credit scores when lenders accessed the data.

Open banking explained means errors by third-party apps can have real financial consequences.

For protecting your data, see KYC/AML Automation for Fintech Startups.

Who Has Access to Your Bank Data Right Now?

Open banking explained requires knowing who already has your information.

Major Open Banking Aggregators

These companies provide the infrastructure that most fintech apps use to connect to banks:

AggregatorConnected AppsMarket Share
PlaidVenmo, Robinhood, Coinbase, Betterment70%
YodleeEnvestnet, Chase, Fidelity15%
FinicityWells Fargo, Experian, Mastercard8%
MXAlly, SoFi, LendingClub5%

“Open banking explained” means that if you use any connected financial app, your data has likely passed through one of these aggregators.

Common Apps That Use Open Banking

App CategoryExamples
BudgetingMint, YNAB, Rocket Money, Copilot
InvestingRobinhood, Acorns, Betterment, Wealthfront
LendingAffirm, Klarna, Upstart, SoFi
PaymentVenmo, PayPal, Cash App, Zelle
Credit monitoringCredit Karma, Experian, WalletHub

“Open banking explained” means every app on this list has access to some portion of your financial data.

For tracking which apps have access, see Best Free Portfolio Trackers.

Open Banking Explained: US vs. EU Regulations

“Open banking explained” varies dramatically by where you live.

European Union: Strong Consumer Protection

The EU’s Revised Payment Services Directive (PSD2) has governed open banking since 2018. Key protections include the following:

ProtectionWhat It Means
Explicit consent requiredApps must ask permission for each data type
Data minimizationApps can only access what they need
Right to deletionYou can request data removal
Strict liabilityBanks liable for unauthorized access
Regulatory oversightNational authorities monitor compliance

Open banking explained in the EU puts consumers firmly in control.

United States: A Patchwork of Protections

The US has no federal open banking law. Instead:

ProtectionStatus
CFPB Section 1033Proposed rule (expected 2026) โ€“ not yet final
State lawsCalifornia, Virginia, Colorado, Connecticut have privacy laws
Bank terms of serviceVary dramatically by institution
Third-party agreementsApps set their own policies

Open banking explained in the US means fewer protections than in Europe. The CFPB’s Section 1033 rule is expected to be finalized in late 2026.

What the CFPB Section 1033 Rule Would Do

Proposed RequirementConsumer Impact
Banks must provide data accessCannot block third-party apps
Standardized API formatEasier to switch banks
Data minimizationApps cannot collect excess data
Revocation rightsYou can stop data sharing anytime
Prohibition on data sellingAggregators cannot resell your data

Open banking explained with Section 1033 would bring the US closer to EU standards. But the rule is not yet law.

For compliance developments, see Fintech Compliance for Small Businesses.

How to See Which Apps Have Access to Your Bank Accounts

“Open banking explained” is useless without action. Here is how to audit your connected apps.

Method #1: Check Your Bank’s Connected Apps Page

Most major banks now have a “Connected Apps” or “Third-Party Access” section:

BankWhere to Find Connected Apps
ChaseProfile & Settings โ†’ Connected Apps
Bank of AmericaSecurity Center โ†’ Connected Apps
Wells FargoAccount Settings โ†’ Third-Party Access
CitiSecurity โ†’ App Permissions
Capital OneSettings โ†’ External Accounts

Open banking explained includes knowing that each bank has a different interface. Search for “connected apps” or “third-party access” in your bank’s settings.

Method #2: Check Your Aggregator Dashboard

AggregatorHow to See Connected Apps
Plaidmy.plaid.com (create account using same credentials)
Yodleeyodlee.com โ†’ Consumer Portal

Method #3: Revoke Access Immediately

StepAction
1Review every connected app
2Ask yourself: “Have I used this in the last 90 days?”
3If no, revoke access immediately
4For active apps, review their privacy policy

Open banking explained includes the power to say no.

For managing your digital footprint, see Digital Banking vs Traditional Banking.

Open Banking Explained: Frequently Asked Questions

Is open banking safe?

Open banking explained safely: When implemented with secure APIs and strong regulations, it is safer than screen scraping. However, your data is only as secure as the apps you connect. In the US, fewer regulations mean a higher risk than in the EU.

Can apps steal my money through open banking?

No. Open banking explained through APIs typically provides read-only access. Apps cannot initiate transfers or make payments without explicit authorization for each transaction.

How do I know if an app is using open banking?

If the app asks you to log into your bank account through a secure window (not by typing your credentials into the app itself), it is likely using secure open banking APIs. If the app asks you to type your bank username and password directly into the app, it may still be using screen scraping.

Can I opt out of open banking?

Yes. You can revoke access to any third-party app through your bank’s connected apps page. However, your past data may remain with the app. To request deletion, you must contact each app directly.

Is open banking available in all countries?

No. The US is still developing federal open banking rules through the CFPB’s Section 1033. The EU has had PSD2 since 2018. The UK, Australia, Canada, Brazil, and India have varying levels of open banking implementation.

Does open banking affect my credit score?

Indirectly. If lenders access your transaction history through open banking, spending patterns could influence credit decisions. Errors in third-party categorization could affect how lenders view your financial behavior.

For credit monitoring, see Passive Income Portfolio with $1,000.

Your 30-Day Action Plan to Protect Your Bank Data

Open banking explained is not just knowledgeโ€”it is action.

Week 1: Audit Your Connected Apps

DayActionTime
1Log into your primary bank and find “Connected Apps” or “Third-Party Access”15 minutes
2Make a list of every app with access10 minutes
3For each app, ask: “Have I used this in the last 3 months?”15 minutes
4Revoke access for unused apps10 minutes

Week 2: Review Active App Permissions

DayActionTime
5-6For each active app, read its privacy policy (search for “data retention” and “data sharing”)30 minutes
7Check if the app sells anonymized data to third parties15 minutes
8Decide which apps are worth the privacy trade-off15 minutes

Week 3: Strengthen Your Defenses

DayActionTime
9-10Enable two-factor authentication on your bank account10 minutes
11-12Set up bank alerts for new third-party connections10 minutes
13-14Review your bank’s fraud protection policies15 minutes

Week 4: Stay Vigilant

DayActionTime
15-30Check your connected apps monthly10 minutes/month
OngoingBefore connecting new apps, ask: “Is the benefit worth the data access?”5 minutes per app

Open banking explained is about informed consent. You cannot consent if you do not understand.

AI in Personal Finance 2026: 6 Ways Your Wallet Is at Risk

AI in personal finance 2026: 401k, retrenchment, budgeting, savings, and financial health categories visualized for personal finance management

AI in Personal Finance 2026: The Invisible Force Controlling Your Money

AI in personal finance 2026 is quietly deciding your financial future. Right now, as you read this, algorithms are making decisions that affect your money, your job, and your credit.

You cannot see them. You cannot talk to them. But AI in personal finance 2026 now influences the following:

  • Whether you get hired for a job
  • Whether you qualify for a mortgage or a car loan
  • How much interest do you pay on credit cards
  • What financial advice appears on your phone
  • Whether a debt collector contacts you at dinner

The data is clear. According to a May 2026 survey by TD Bank, 55% of Americans now use AI to help manage their financesโ€”up from just 10% in 2025. Today, more people consult chatbots for financial guidance than consult human financial advisors.

Banks are also embracing AI in personal finance 2026. Major lenders use AI to screen loan applications. Employers use AI to filter job candidates. Debt collectors use AI to maximize contact attempts.

Here is the problem: AI in personal finance 2026 systems are not neutral. They inherit biases from their training data. They make mistakes. And when they hurt you, proving it is nearly impossible because the algorithms are “black boxes”โ€”even their creators cannot fully explain how they decide.

AI in personal finance 2026 is here to stay. But you need to understand how it works, where it fails, and how to fight back.

For tracking how AI affects your investments, see Best Free Portfolio Trackers for Crypto and Stocks.

AI in Personal Finance 2026 Risk #1: Getting Hired or Ghosted by Machines

AI in personal finance 2026 starts with your career. Before a human ever sees your resume, an AI system has already judged you.

The Lawsuit That Changes Everything

In January 2026, a class action lawsuit was filed against Eightfold AI, a company that provides AI hiring platforms to major financial institutions, including BNY, Morgan Stanley, and PayPal.

The lawsuit alleges that Eightfold’s AI in personal finance 2026 system

  • Scrapes personal data from across the internet without your consent
  • Generates a “Match Score” ranking candidates from 0 to 5
  • Uses this score to filter applicants before any human reviews a resume

One plaintiff, Erin Kistler, has a computer science degree from Ohio State, spent six years as a program manager at Microsoft, and has 19 years of product management experience. Yet she received automated rejections from PayPal, Microsoft, and Netflix.

“I’ve applied to hundreds of jobs,” Kistler said, “but it feels like an unseen force is stopping me from being fairly considered.”

That unseen force is AI in personal finance 2026.

How AI Hiring Works Against You

StepWhat HappensWhy It Hurts You
1You submit a job applicationAI begins collecting data immediately
2AI scrapes your online presenceSocial media, location, browsing history are judged
3AI generates a “match score.”You are reduced to a number from 0 to 5
4Employers filter by scoreLow-scoring applicants never seen by humans
5You receive automated rejectionNo explanation of why you were filtered out

AI in personal finance 2026 means your dream job may never be seen by a human being.

Your Rights Under the Law

The lawsuit argues that Eightfold is operating as a “consumer reporting agency” under the Fair Credit Reporting Act (FCRA) without complying with the law.

Under the FCRA:

  • Companies must disclose when they use consumer reports for employment decisions
  • You have the right to review and dispute information
  • Adverse action notices must explain the specific reasons for denial

AI in personal finance 2026 does not exempt employers from these requirements.

What You Can Do Right Now

ActionWhy It Helps
Research if employers use AI screeningGlassdoor and Reddit often have this information
Request your consumer report under FCRAFind out what data AI systems have on you
Save all automated rejection emailsDocumentation helps in legal challenges

AI in personal finance 2026 is not going away, but knowing your rights is the first step to protecting them.

For managing your finances after a job search, see Digital Banking vs Traditional Banking.

AI in Personal Finance 2026 Risk #2: Loan Denials You Cannot Appeal

AI in personal finance 2026 has made getting a loan fasterโ€”and more dangerous.

How AI Decides Your Creditworthiness

Traditional lending used human underwriters who could explain their decisions. AI in personal finance 2026 uses machine learning models that even their developers cannot fully explain.

When you apply for a mortgage, car loan, or credit card, AI in personal finance 2026 systems evaluate the following:

  • Your credit score and history
  • Your employment and income
  • Your spending patterns
  • Your online behavior (in some cases)
  • Your location and demographics

The algorithm then produces a decision: approve or deny. If denied, you often receive a generic letter citing “insufficient credit history” or “high debt-to-income ratio”โ€”without specific explanations.

The Gender Bias Problem

In Australia, where similar trends are emerging, experts warn that AI in personal finance 2026 tools will make it harder for women to secure loans.

Leonora Risse, an economist focused on gender equality, explains: “These systems aren’t designed to discriminate on the basis of gender. But once you put them into practice, they end up being gender biased because of the very different experiences and circumstances that men and women tend to be in.”

FactorHow AI Interprets ItWhy It Hurts Women
Career breaksGaps in employment historyWomen take more career breaks for family
Part-time workLower income trajectoryWomen more likely to work part-time
Spending patternsAlgorithms infer riskWomen’s spending differs from male norm
Credit historyBased on traditional modelsWomen may have shorter credit histories

AI in personal finance 2026 amplifies existing discrimination rather than eliminating it.

The CFPB’s Position

The Consumer Financial Protection Bureau has been clear: existing fair lending laws apply fully to AI in personal finance in 2026. The Equal Credit Opportunity Act (ECOA) requires creditors to provide specific reasons for adverse actions.

In September 2023, Circular 2023-03 clarified that creditors cannot satisfy this requirement by pointing to generic reasons. When an AI denies a loan, the lender must provide specific, accurate explanations that reflect the actual model reasoning.

AI in personal finance 2026 does not give lenders a pass on explaining their decisions.

What You Can Do Right Now

ActionWhy It Helps
Request specific reasons for any loan denialUnder ECOA, you are entitled to them
Challenge generic explanationsGeneric reasons may violate the law
File a complaint with the CFPBThe CFPB is actively enforcing against AI discrimination

AI in personal finance 2026 should not mean you accept unfair treatment silently.

For building credit to improve AI loan decisions, see Passive Income Portfolio with $1,000.

AI in Personal Finance 2026 Risk #3: Financial Advice That Costs You Thousands

AI in personal finance 2026 is now the most popular financial advisor in America.

The Numbers Are Staggering

According to a May 2026 survey by TD Bank, 55% of Americans now use AI to help manage their finances. This represents a dramatic jump from just 10% in 2025.

AI in personal finance 2026 has become more popular than human financial advisors. Only about two-fifths of Americans consult financial professionals for advice.

Is the Advice Any Good?

Researchers at MIT, Stanford, and the University of Texas studied this question. They built a simulation of how people earn, invest, and spend over their lifetimes, then fed human-written prompts into ChatGPT and Gemini.

The good news: AI in personal finance 2026 generally gives sensible advice. It recommends:

  • Saving more during working years
  • Investing in diversified stock funds
  • Reducing stock exposure after age 45
  • Building emergency savings buffers

Following AI in personal finance 2026 advice helped simulate people build significant wealth, often exceeding $1 million by retirement.

The bad news: The quality of AI in personal finance 2026 advice depends entirely on how you ask the question.

The Literacy Gap

The MIT research found that advice from prompts written by people with low financial literacy produced nearly $50,000 less wealth at age 60 than advice from high-literacy users.

AI in personal finance 2026 is not magic. Garbage in, garbage out.

The Gender Gap

Advice from prompts written by women led to nearly $60,000 less wealth than advice from prompts by men.

Two-thirds of this gap came from differences in how men and women write prompts. The remaining third came from AI in personal finance 2026, treating gender itself as a signalโ€”recommending more stock exposure when the same prompt was labeled as coming from a man.

What You Can Do Right Now

ActionWhy It Helps
Write specific, detailed promptsInclude your age, income, debt, goals, and timeline
Learn basic financial literacyYour knowledge directly impacts AI advice quality
Compare answers from multiple AI modelsChatGPT, Gemini, and Claude give different advice
Verify major decisions with human expertsAI is a tool, not an oracle

AI in personal finance 2026 can help you build wealth โ€“ but only if you know how to ask.

For building financial literacy, see Best Budgeting Apps for Couples.

AI in Personal Finance 2026 Risk #4: Debt Collectors Who Never Stop Calling

AI in personal finance 2026 has made debt collection more aggressiveโ€”and more illegal.

How AI Debt Collection Works

Debt collection agencies are rapidly adopting AI in personal finance 2026 to maximize contact and recovery. AI systems can:

  • Call hundreds of numbers simultaneously
  • Track which times of day get answers
  • Adjust scripts based on your responses
  • Escalate accounts automatically

But AI in personal finance 2026 systems often break the law because compliance rules were not written into the model.

The FDCPA Violations

ViolationHow AI Causes ItPenalty
Over-contacting consumersAI tracks calls at campaign level, not per debt, exceeding 7-in-7 limit$1,000 per violation
Wrong-party contactAI pulls stale contact data and dials without identity confirmation$1,000 per violation
Opaque scoring decisionsAI flags accounts for escalation but cannot explain whyAdverse action violation
Ignoring opt-outsAI systems fail to honor opt-out requests across channels500โˆ’500โˆ’1,500 per contact

AI in personal finance 2026 does not exempt debt collectors from the Fair Debt Collection Practices Act.

The CFPB’s Warning

The CFPB has been explicit: “Existing laws apply fully to uses of AI.” Institutions remain fully responsible for what their AI systems produce, regardless of how automated the process is.

In March 2026, the CFPB confirmed that AI decisioning, data privacy, and automated communications remain active areas of regulatory focus.

AI in personal finance 2026: Debt collection is being watched closely by regulators.

What You Can Do Right Now

ActionWhy It Helps
Document every communicationTime, date, method, and content of each contact
Count contacts in any 7-day periodMore than 7 calls is a violation
Request debt validation in writingCollectors must prove you owe the debt
Report violations to the CFPBEnforcement actions start with consumer complaints

AI in personal finance 2026 does not mean you have to tolerate harassment.

For managing debt within your financial plan, see Digital Banking vs Traditional Banking.

AI in Personal Finance 2026 Risk #5: The EU AI Act Delay Leaves You Exposed

AI in personal finance 2026 regulation is comingโ€”but later than expected.

What Happened on May 7, 2026

On May 7, 2026, EU lawmakers reached a provisional agreement to overhaul the AI Act. The changes include significant delays.

ProvisionPrevious DeadlineNew Deadline
High-risk AI systems (employment, credit, etc.)August 2, 2026December 2, 2027
Transparency obligationsAugust 2, 2026December 2, 2026
National AI regulatory sandboxesAugust 2, 2026August 2, 2027

AI in personal finance 2026: High-risk systems now have 16 extra months to comply.

What Is Still Prohibited?

The update also adds a new prohibition on AI in personal finance 2026 systems that create child sexual abuse material or non-consensual intimate images. Compliance begins December 2, 2026.

What This Means for You

The delay gives companies more time to comply, but the law is still coming. AI in personal finance 2026 systems in employment, credit, and other sensitive areas will be regulated.

For EU residents, this means stronger protections against AI-driven discrimination in personal finance starting December 2027.

For US readers, watch how EU regulations influence US policy. The CFPB has already signaled aggressive enforcement of existing laws for AI in personal finance 2026 systems.

What You Can Do Right Now

ActionWhy It Helps
Follow EU AI Act developmentsUS policy often follows EU leadership
Support consumer protection legislationContact your representatives about AI regulation
Know your rights under existing lawsECOA, FCRA, and FDCPA already apply to AI

AI in personal finance 2026 regulation is coming. The delay is not a cancellation.

For understanding financial regulations, see Fintech Compliance for Small Businesses.

AI in Personal Finance 2026 Risk #6: Your Financial Literacy Determines Your Wealth

AI in personal finance 2026 is a tool. Like any tool, its effectiveness depends on the user.

The MIT Research Conclusion

The MIT, Stanford, and University of Texas research team reached a clear conclusion: AI in personal finance 2026 rewards financial literacy.

They found that prompting AI in personal finance 2026 with richer instructions โ€“ drawing on life-cycle planning, modern portfolio theory, and specific assumptions about finances โ€“ dramatically improved the quality of spending and saving advice.

How to Write Better Financial Prompts

Instead of ThisTry This
“How should I invest $1,000?”“I am 30 years old, have a stable job earning $60,000/year, no debt, and want to save for retirement in 3-5 years with moderate risk tolerance. How should I invest $1,000?”
“Should I buy a house?”“I have $50,000 saved and make $80,000/year, plan to stay in my city for at least 5 years, currently pay $1,800/month in rent, and have a 720 credit score. Should I buy a house?”
“How much should I save?”“I earn $4,000/month after taxes, spend 3,200 on rent, food, and transportation, have no high-interest debt, and want to retire comfortably at 65. How much should I save monthly?”

AI in personal finance 2026 gives better answers when you ask better questions.

What AI Still Gets Wrong

The MIT research found that AI in personal finance 2026 struggles with the following:

  • Adjusting spending after unexpected income shocks
  • Actively rebalancing portfolios (it tends to be passive)
  • Recommending appropriate drawdown strategies in retirement
  • Complex tax situations or estate planning

AI in personal finance 2026 is not a replacement for human expertise in complex situations.

What You Can Do Right Now

ActionWhy It Helps
Learn basic financial conceptsCompound interest, diversification, risk management
Write detailed promptsInclude age, income, debt, goals, and timeline
Compare advice from multiple AI modelsDifferent models give different answers
Verify major decisions with human expertsAI is a tool, not an oracle

AI in personal finance 2026 can help you build wealthโ€”but you must drive.

For continuing your financial education, see Robo-Advisors vs Human Advisors.

How to Protect Yourself From AI in Personal Finance 2026

Based on all the risks covered above, here is your complete action plan for AI in personal finance 2026.

Your Rights Under Existing Laws

LawWhat It ProtectsApplies to AI?
Equal Credit Opportunity Act (ECOA)Credit discriminationYes, CFPB confirmed
Fair Credit Reporting Act (FCRA)Consumer report accuracyPlaintiffs argue yes
Fair Debt Collection Practices Act (FDCPA)Debt collection harassmentYes โ€“ explicitly

AI in personal finance 2026 does not exempt companies from these laws.

Your 30-Day Action Plan for AI in Personal Finance 2026

WeekActionTime
Week 1Check your credit reports for free at AnnualCreditReport.com30 minutes
Week 2Review your bank statements for AI-driven fees or changes30 minutes
Week 3Test AI financial advice with detailed prompts. Compare ChatGPT, Gemini, and Claude.1 hour
Week 4Document any recent adverse decisions (job denials, loan denials) and request specific reasons1 hour

AI in personal finance 2026 is not going away. But you can protect yourself.

For tracking your financial progress, see Best Free Portfolio Trackers.

Frequently Asked Questions About AI in Personal Finance 2026

Is AI in personal finance 2026 safe to use?

Yes, with caveats. Research shows that AI in personal finance 2026 generally gives sensible financial advice. However, the quality depends on your financial literacy and how you ask the question. AI in personal finance 2026 also struggles with complex situations and may reflect demographic biases.

Can AI in personal finance 2026 deny me a loan?

Yes. Lenders use AI in personal finance 2026 models to evaluate creditworthiness. If the model flags your application, you can be denied without a human ever reviewing your file. Under ECOA, you have the right to specific reasons for denial.

What is the CFPB doing about AI in personal finance 2026?

The CFPB has confirmed that existing laws apply fully to AI in personal finance 2026. In September 2023, Circular 2023-03 clarified that adverse action notices must provide specific, accurate reasons reflecting actual model reasoning. The CFPB continues to prioritize AI in personal finance 2026 governance in examinations.

When does the EU AI Act regulate AI in personal finance 2026?

High-risk AI in personal finance 2026 rules (including for employment and credit) were scheduled for August 2, 2026, but have been delayed to December 2, 2027. The delay gives companies more time to comply but does not change the law’s fundamental requirements.

Will AI in personal finance 2026 replace human financial advisors?

Not entirely. AI in personal finance 2026 excels at basic guidance and portfolio management. But complex situationsโ€”estate planning, tax optimization, and behavioral coachingโ€”still benefit from human expertise. The best approach is hybrid: AI for routine tasks, humans for strategic decisions.

How do I know if an employer used AI in personal finance 2026 to reject me?

It is difficult. Most employers do not disclose their use of AI in personal finance 2026 screening tools. However, if you suspect AI discrimination, you can request any consumer reports used in the hiring process under the FCRA.

For more AI financial tools, see AI Budget Trackers for Freelancers.

AI in Personal Finance 2026: Your Action Plan

AI in personal finance 2026 is not a future trend. It is happening now.

The 6 Risks Summary

RiskKey Takeaway
#1: AI hiringAI filters candidates before humans see them. Know your FCRA rights.
#2: AI loan biasWomen face increased risk. Request specific denial reasons.
#3: AI advice55% use it. Quality depends on your literacy.
#4: AI debt collectionSystems violate FDCPA. Document everything.
#5: EU AI Act delayEnforcement pushed to 2027. Regulation is coming.
#6: Your literacyBetter questions = better answers. Invest in learning.

Your 30-Day Action Plan for AI in Personal Finance 2026

  1. Week 1: Check your credit reports for free at AnnualCreditReport.com
  2. Week 2: Review your bank and credit card statements for AI-driven fees or changes
  3. Week 3: Test AI in personal finance 2026 advice with specific, detailed prompts
  4. Week 4: Document any recent adverse decisions and request specific reasons

AI in personal finance 2026 is watching you. Now you know how to watch back.

Ready to take control? Download our AI financial rights checklist or compare AI financial tools side by side.

Reviewed by: Dennis M, FinTech Researcher

Dennis has tested over 50 digital banking apps and 25 crypto exchanges.