The Moment of Financial Independence.
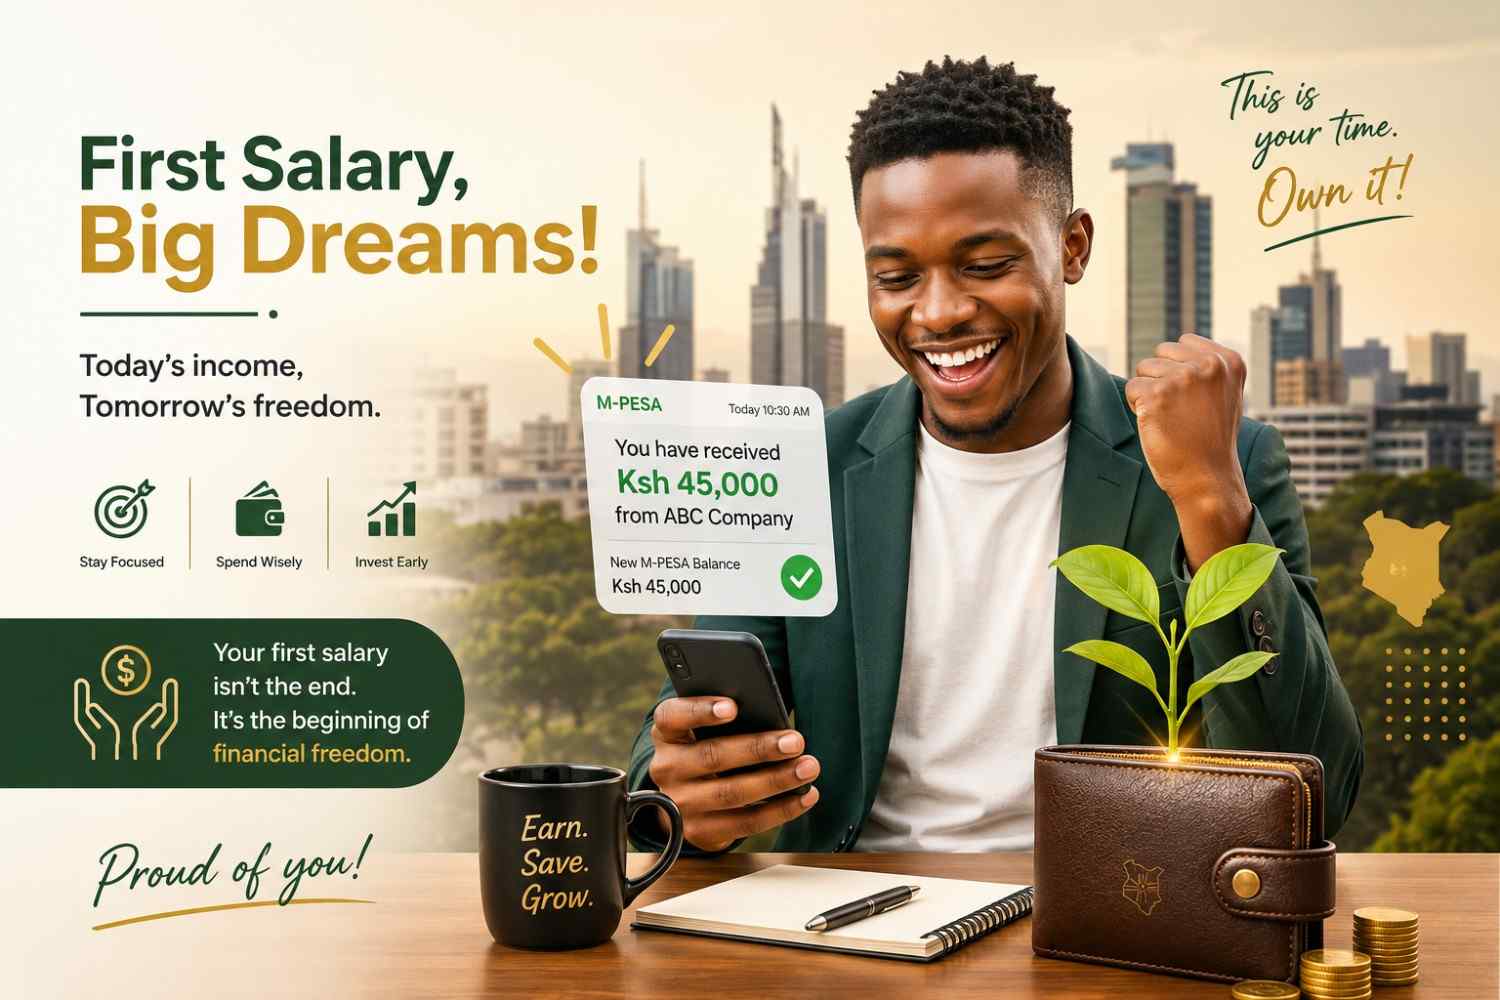
Receiving your first salary is one of the most exciting milestones in life. This first salary Kenya guide is designed to help you navigate this critical moment. For many young Kenyans, this first salary represents years of hard work, sacrifice, and the long-awaited transition from dependence to independence. Whether you’re earning Sh30,000 or Sh100,000, this first salary Kenya moment marks the beginning of your financial journey.
But here’s the reality: the choices you make with your very first salary can determine your financial trajectory for decades. According to financial experts, the first 24 months of employment should be dedicated to building an impenetrable financial foundation.
and rather than chasing high-risk investments or upgrading your lifestyle.
This first salary Kenya guide will show you exactly how to do that. The excitement of seeing money in your account can easily lead to impulse spending. Within two weeks, many young professionals find themselves wondering, “Where did all my money go?” The good news is that with the right habits, you can avoid this trap and build lasting wealth.
What This First Salary Guide Will Do For You
This comprehensive first salary Kenya guide will walk you through ten essential steps to manage your first salary wisely—tailored specifically for the Kenyan context. We’ll cover everything from understanding your payslip to starting your first investment, with practical examples and actionable strategies. This first salary Kenya guide is your roadmap to financial freedom.
Step 1: Know Your Net Pay—Before You Spend a Shilling
Personal financial advisor Sophia Achieng emphasizes that before spending anything, you must clearly understand your payslip. This first salary guide starts with this fundamental step. Your gross salary is not what lands in your account.
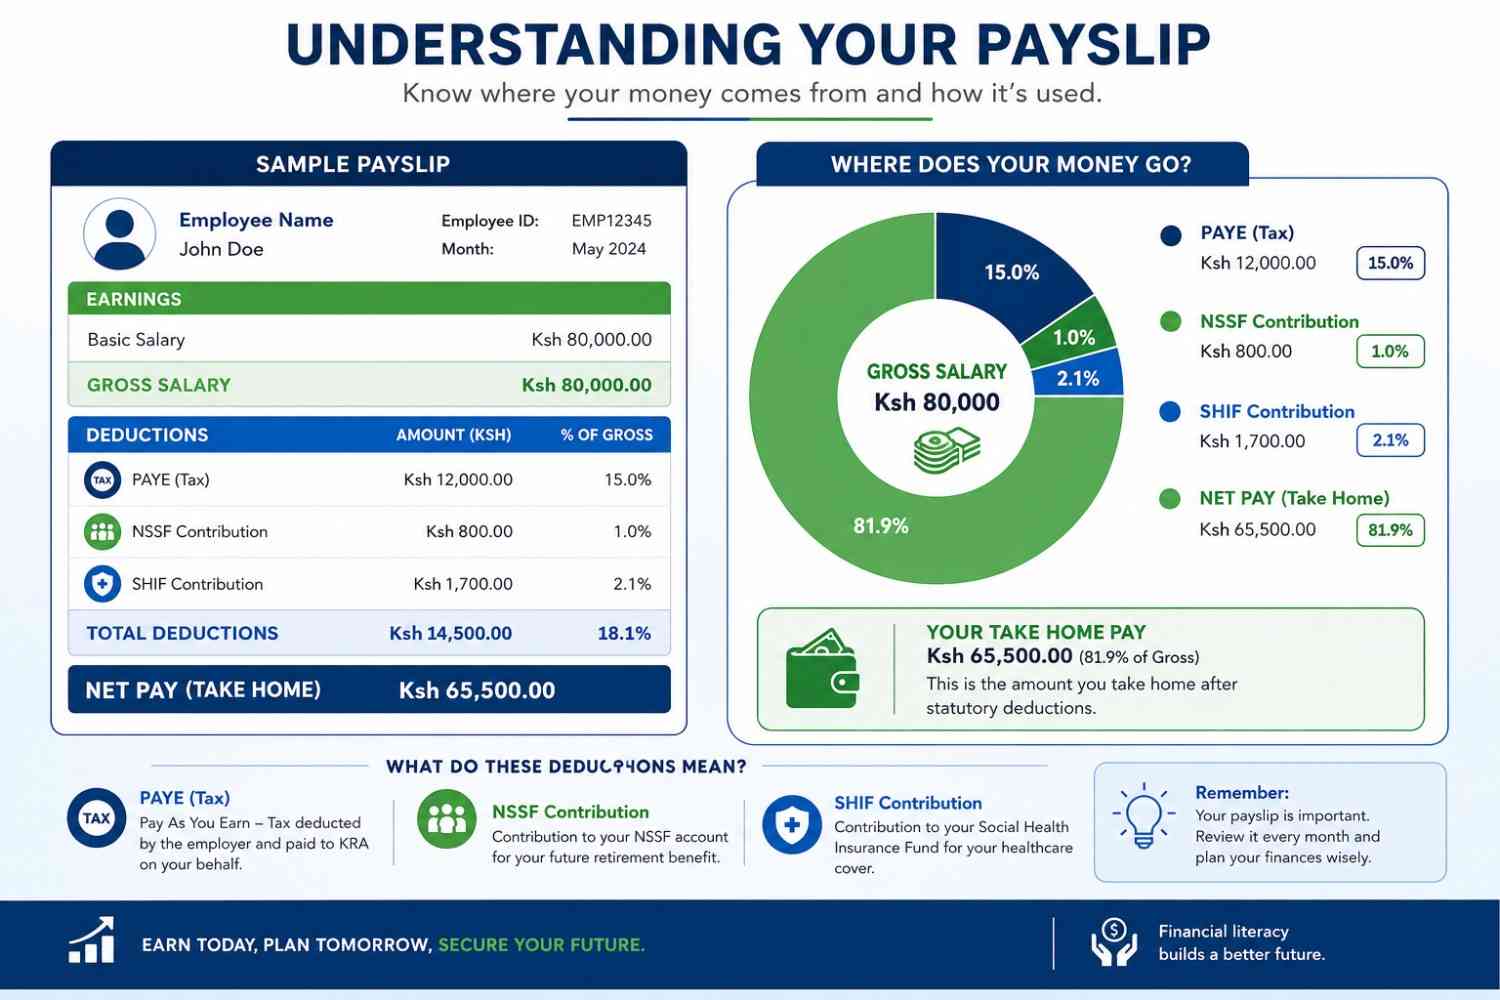
Understanding Your Payslip
When you receive your first payslip, look carefully at the deductions:
- PAYE (Pay As You Earn): Income tax deducted at source
- NSSF (National Social Security Fund): Pension contribution
- SHIF (Social Health Insurance Fund): Health insurance contribution
- Other deductions: Union dues, pension schemes, or loan repayments
For instance, if your gross salary is Sh50,000, your net take-home pay might be around Sh39,000 after statutory deductions. Knowing this helps you plan realistically. This first salary Kenya guide emphasizes that understanding your payslip is the foundation of all financial planning.
Confirm Your Employment Benefits
Before spending, understand your full compensation package:
- Medical cover details (is your family covered?)
- Transport and communication allowances
- Bonus structure and salary review timelines
- Insurance benefits
“Look at your payslip critically and get to know what deductions have been made,” advises Sophia Achieng. “People have this fear that if you negotiate, you will not be hired, which should not be the case. You should be firm enough and negotiate respectfully. If the salary is fixed, look to see if the benefits are flexible.”
Step 2: Create a Budget That Works in the Kenyan Context.
Budgeting is the cornerstone of financial freedom. This first salary Kenya guide recommends creating a budget immediately. It gives your money direction and prevents you from spending your entire salary within the first few weeks.
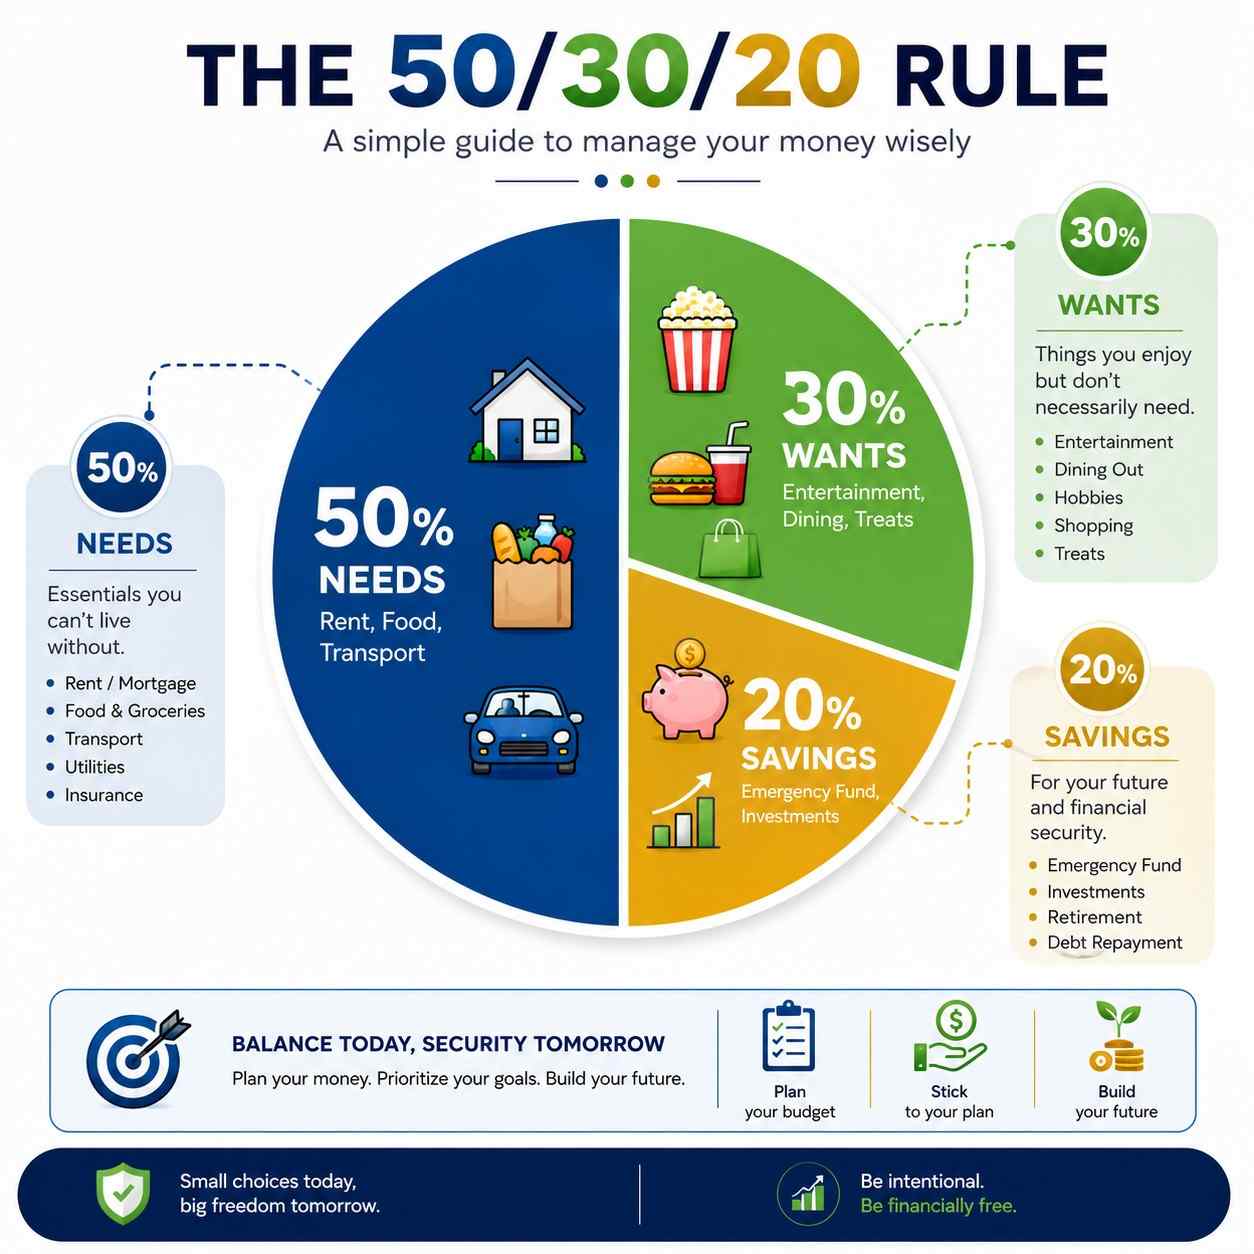
The 50/30/20 Rule (Adapted for Kenya)
A simple starting point is the 50/30/20 rule:
| Category | Percentage | Purpose |
|---|---|---|
| Needs | 50% | Essentials: rent, food, transport, utilities |
| Wants | 30% | Personal treats, entertainment, dining out |
| Savings/Investments | 20% | Emergency fund, investments, debt repayment |
If you earn Sh39,000 net, that’s:
- Sh19,500 for needs
- Sh11,700 for wants
- Sh7,800 for savings and investments
Adjust based on your reality: If rent takes from your first salary a larger share, trim from wants, not savings. The most important thing is being consistent. This first salary guide stresses that consistency is more important than perfection.
Practical Budgeting Tips for Kenya
- Track your expenses for at least a month using a spreadsheet, a budgeting app, or even a notebook. The M-Pesa app can help you track spending.
- Identify “money leaks”—those small, seemingly harmless expenses that add up. Daily coffee, snacks, and impulse online shopping can significantly impact your wallet.
- Create a budget before you spend, not after. Give every shilling a purpose.
“For those considering whether to rent or buy, our guide on Rent vs Buy California provides 7 smart lessons that can help inform your decision.”
Step 3: Save First, Spend Later—The “Pay Yourself First” Rule.
One of the most powerful money habits you can develop is treating savings like a non-negotiable bill on your first salary. Pay yourself before you pay anyone else. This first salary guide emphasizes this principle above all others.
Why This Matters
As soon as your salary hits your account, immediately transfer a predetermined amount to savings. If you never see the money in your everyday account, you won’t miss it.
How Much Should You Save?
Finance coach Margaret Njeri recommends saving 20% of every income. Even small amounts teach discipline and set the stage for future financial stability.
If you earn Sh30,000 and aim to save 10%, immediately transfer Sh3,000 to a separate savings account when the money comes in. A financial advisor from Abojani Investment emphasizes that a minimum of 10-15% of net salary should be funneled into savings.
Automate Your Savings
Many employers or banks can facilitate automatic deductions to a savings or SACCO account. Automation removes temptation. You can set up:
- Standing orders to your savings account
- Automatic transfers to M-Shwari or KCB M-Pesa
- SACCO monthly contributions
Step 4: Build Your Emergency Fund.
Life does not always go according to plan. You may experience job changes, medical emergencies, or unexpected bills. Having emergency savings gives you a safety net and reduces financial stress. This first salary guide recommends prioritizing this step.
What Is an Emergency Fund?
An emergency fund is money set aside specifically for unexpected expenses. According to financial experts, you should aim to build an emergency fund that covers three to six months of living expenses.
How to Start Building It
- Start small: Begin with a target of one month’s expenses, then gradually grow it.
- Automate transfers: Set up a standing order to your emergency fund at the beginning of each month.
- Keep it liquid: Your emergency fund should be easily accessible—ideally in a money market fund or a savings account.
Real Example: If your monthly expenses are Sh30,000, save Sh5,000 monthly to reach your first goal within six months.
Finance coach Margaret Njeri explains: “Habits form now, and waiting until adulthood makes saving harder.”
Step 5: Understanding Where to Save.
Where you save matters. Different savings vehicles serve different purposes. This first salary guide will help you make the right choice.
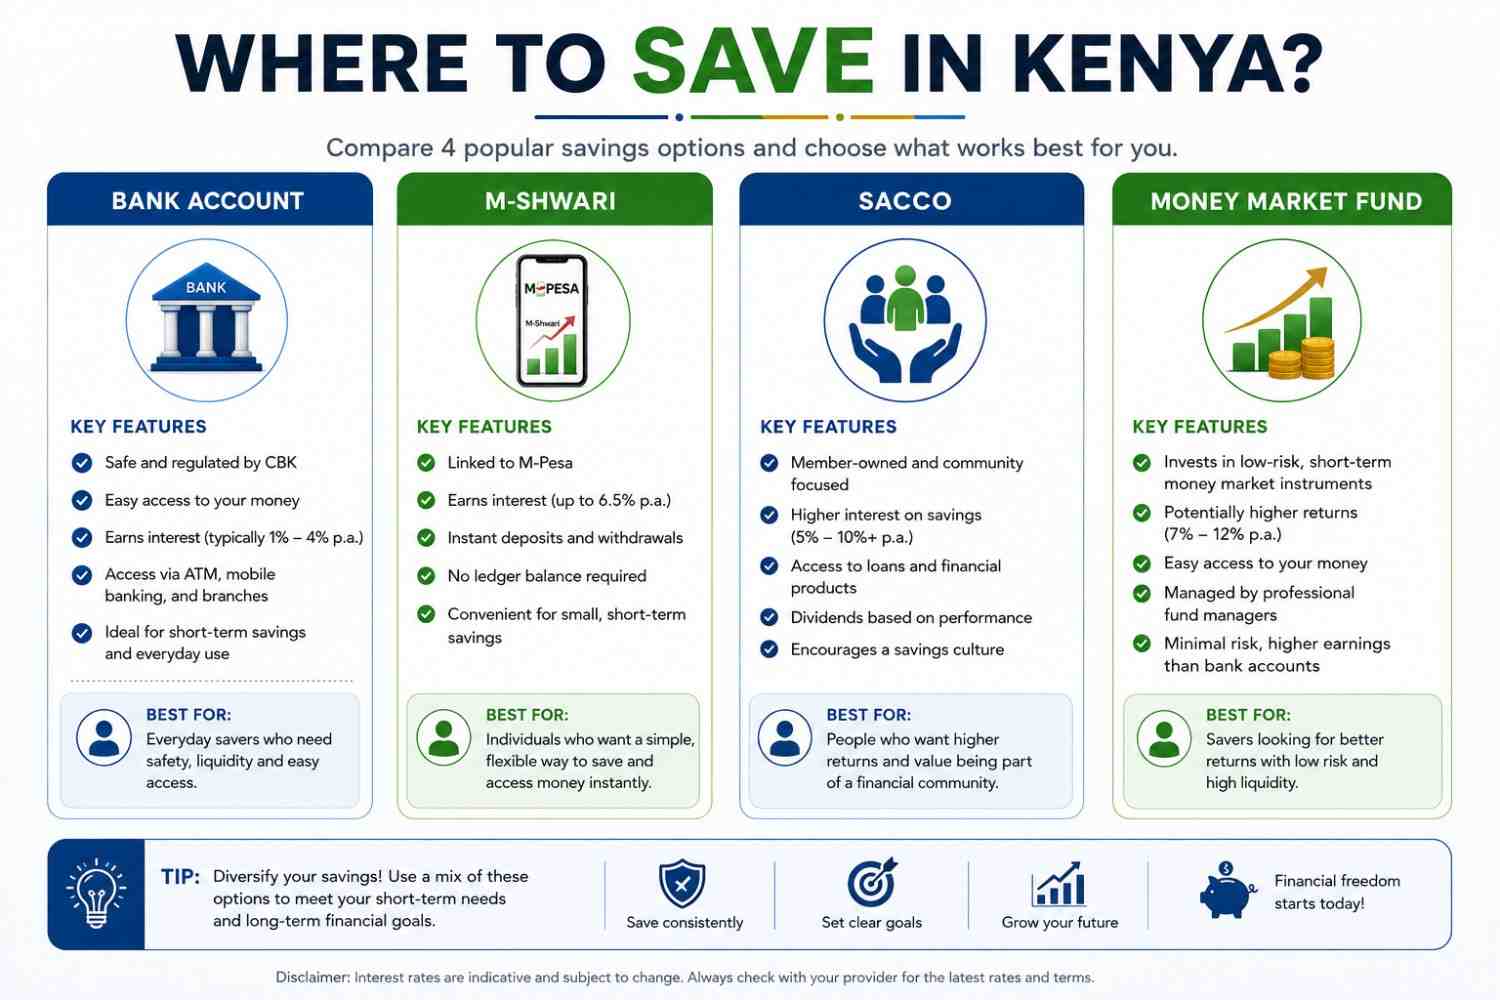
Options for Your Savings in Kenya-Africa
| Savings Vehicle | Best For | Key Features |
|---|---|---|
| Savings Account | Emergency funds, short-term goals | Easy access, low interest (4-7% at KCB Goal Savings) |
| M-Shwari | Quick, mobile savings | 2-5% interest, accessible via M-Pesa |
| SACCO | Disciplined saving, dividends | 5-10% annual dividends, loan access |
| Money Market Fund | Emergency funds, short-term parking | Higher returns (10-12% in Kenya), same-day/next-day liquidity |
| Locked M-Shwari | Discipline, saving with a goal | Lock your savings for a chosen period. |
| Fixed Deposit | Medium-term savings | Higher interest but no access until maturity |
Making the Right Choice
For short-term needs and emergency funds, use a secure and liquid place like a savings account or Money Market Fund. Digital savings platforms like M-Shwari are popular—you can save on your phone and earn interest. For disciplined saving with added benefits like loan access, join a SACCO.
Step 6: Start Investing—Even With Ksh 1,000.
Once you’ve built a savings cushion, consider investing—even with small amounts. According to investment experts from Absa Bank Kenya, many unit trusts let you start with as little as Sh1,000. This first salary Kenya guide encourages you to start investing early.
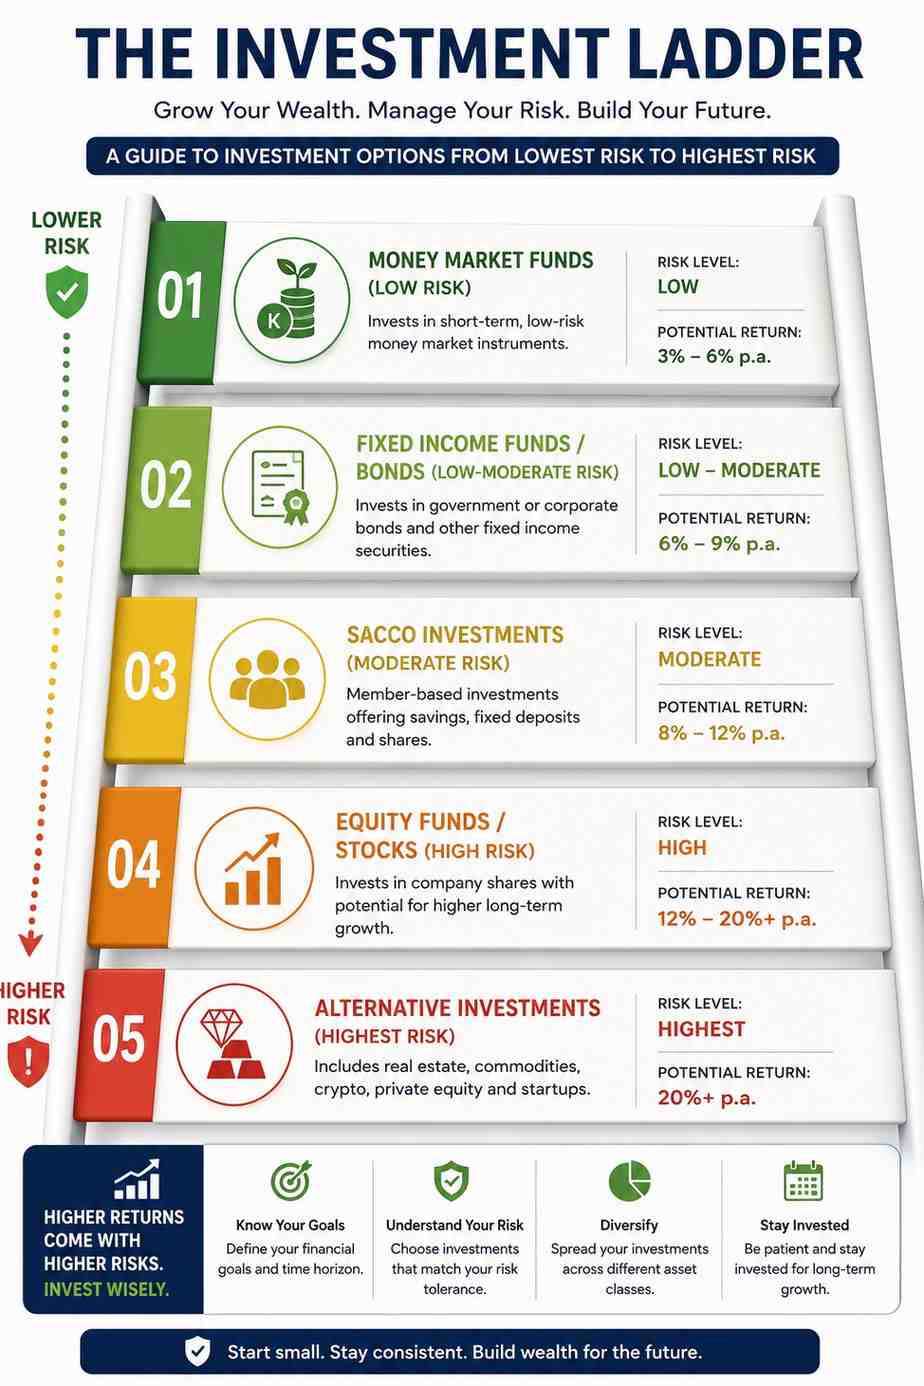
Why You Need to Invest
Inflation reduces your money’s value over time. If inflation is 5% and your savings earn 4%, you’re effectively losing 1% in purchasing power each year—your shillings grow in number but shrink in value.
Beginner Investment Options in Kenya
According to investment experts from Absa Bank Kenya and @the_acemt Consulting, think of investments on a spectrum:
| Investment Type | Risk Level | Best For |
|---|---|---|
| Money Market Funds | Low | Emergency funds, short-term goals |
| Treasury Bills | Low | “Near cash” options, low risk |
| Fixed Income Funds/Bonds | Low-Moderate | Steadier returns over 3-7 years |
| SACCO Investments | Moderate | Dividends, loan access, community |
| Equity Funds (Stocks) | High | Long-term growth, higher volatility |
How to Start Investing Practically
- Define your goals: Know what you’re saving for and when after you get your first salary.
- Build a safety net: Keep emergency cash in a money market fund first.
- Understand your risk tolerance: Know how you’d react if your investment dropped in value.
- Start small and be consistent: Even Sh1,000 a month can snowball into substantial wealth over time.
- Invest regularly: Set up a standing order for monthly contributions.
The Power of Compounding
James Njagi, Head of Business Development at CIC Asset Management Limited, explains: “Investing just Sh500 a month can snowball into substantial wealth over time. Compounding—earning returns on your returns—is the engine of wealth. Delay costs more than risk.”
“If you’re ready to go further, our Complete Beginner’s Guide to Investing & Personal Finance covers everything from budgeting to advanced trading strategies.”
Step 7: Avoid Lifestyle Inflation—The Silent Wealth Killer.
When income rises, it’s tempting to upgrade everything—from your apartment to your gadgets to your social life. But lifestyle inflation can stall your progress. This first salary Kenya guide warns you about this common trap.
What Is Lifestyle Inflation?
Lifestyle inflation (also called lifestyle creep) is when your spending increases as your income increases. That first paycheck on your first salary makes you feel like you need to prove you’re doing well. You feel pressured to buy expensive outfits, upgrade your phone, take friends out, or live beyond your means.
How to Avoid Lifestyle Inflation
- Maintain your current spending level and channel extra income into investments or savings.
- Grow your lifestyle gradually as your income improves, not immediately.
- Live below your means: Financial advisor Benjamin Cheruiyot advises keeping rent strictly below 25% of net income.
- Quiet growth beats loud spending. You don’t need to prove anything to anyone.
“Instead of upgrading everything at once, take time to understand your true monthly expenses. It is better to grow your lifestyle gradually as your income improves rather than struggle to maintain an image you cannot afford.”
Step 8: Manage Debt Wisely.
Debt can either help you grow or trap you. According to financial experts, avoid borrowing for daily expenses or lifestyle upgrades. Mobile loans and “buy now, pay later” options can quickly snowball. This first salary Kenya guide recommends caution with debt.
Good Debt vs. Bad Debt
- Good Debt: Borrowing for education, a business, or an asset that appreciates.
- Bad Debt: Borrowing for consumption—clothes, phones, eating out, or daily expenses.
Smart Debt Management Tips
- If you have multiple debts, prioritize paying off the ones with the highest interest first.
- Before taking any loan, understand the repayment terms and interest rates clearly.
- Credit should complement a budget, not replace one.
- Ask yourself: Is this loan helping me build something valuable or simply funding a lifestyle I cannot afford?
“When it comes to making important financial decisions, understanding how to choose someone to act on your behalf is crucial—our detailed guide on How to Choose a Financial Power of Attorney outlines 7 critical steps to consider.”
Step 9: Support Family Smartly – The “Black Tax” Strategy.
Many young Kenyans who start earning their first salary feel the responsibility to help parents, siblings, or relatives. Supporting family is important, but it is also necessary to plan your own finances.
The “Black Tax” Reality
The cultural expectation to provide for family can be a significant financial burden. Without a strategy, “black tax” can drain your resources and trap you in a cycle of dependency.
How to Support Family Without Breaking Your Budget
- Set aside an amount you can comfortably give without putting yourself under financial pressure.
- Structure your support: Instead of erratic cash hand-outs, consider paying specific bills (like school fees or SHIF premiums for parents).
- Set healthy boundaries: You cannot pour from an empty cup.
- “Support family but set boundaries”—Set aside an amount you can comfortably give without putting yourself under financial pressure.
The Most Impactful Way to Help
Financial advisor Benjamin Cheruiyot recommends purchasing comprehensive medical insurance or consistently paying SHIF premiums for aging parents. This proactive move protects you from catastrophic, out-of-pocket hospital bills that can instantly wipe out years of savings.
Step 10: Invest in Your Most Valuable Asset—You.
Your earning potential is your greatest asset. According to financial experts, the highest-yielding asset a 25-year-old possesses is their own earning potential.
Why Investing in Yourself Matters
Redirecting early income into professional development provides returns that far outpace traditional financial instruments. Skills and knowledge compound just like money.
How to Invest in Your Career
- Enroll in short courses and obtain industry-specific certifications like KASNEB or CIFA.
- Acquire complementary skills such as data analytics, foreign languages, or digital marketing.
- Invest in mentorship to gain insights and guidance.
- Set career goals that align with your financial aspirations.
- View your income as a tool to fund your next level, not a reward to exhaust.
In a fiercely competitive Kenyan job market, specialized knowledge rapidly translates into accelerated promotions, superior negotiating leverage, and substantially higher compensation packages.
Common Mistakes to Avoid.
Based on expert insights, here are the most common money mistakes young professionals make—and how to avoid them:
1. Upgrading Lifestyle Too Fast
The Mistake: Moving into an expensive apartment, buying a new phone, or eating out daily just to match a new social status.
The Fix: Understand your true monthly expenses. Live within your means and aim to save a portion of your income before spending.
2. Ignoring Savings and Emergency Funds
The Mistake: Delaying savings, thinking you’ll start later when you earn more.
The Fix: Start by saving at least 10% of your salary from your first month. Build a small emergency fund to cover hospital bills, job loss, or family emergencies without borrowing.
3. Not Tracking Where Money Goes
The Mistake: Spending without tracking, then wondering at month-end where it all went.
The Fix: Track your expenses for at least one month. A budget only works if you follow it.
4. Falling for “Guaranteed High Returns” Scams
The Mistake: Chasing investment schemes promising unrealistic returns.
The Fix: Only deal with CMA- or CBK-licensed institutions. If it sounds too good to be true, it probably is.
5. Not Reading the Fine Print on Loans
The Mistake: Taking loans without understanding interest rates and repayment terms.
The Fix: Before taking any loan, understand the repayment terms and interest rates clearly. Credit should complement a budget, not replace one.
6. Spending Before Understanding Your Net Pay
The Mistake: Spending based on gross salary, not net income after deductions.
The Fix: Look at your payslip critically and confirm your net pay before planning your budget.
Your 30-Day Action Plan.
Here’s a practical step-by-step plan for your first month of employment:
Week 1: Understanding Your Money
- □ Review your payslip—understand all deductions
- □ Confirm your net pay (take-home amount)
- □ List all your essential expenses (rent, transport, food, utilities)
- □ Open a separate savings account if you don’t have one
Week 2: Creating Your Budget
- □ Create a budget using the 50/30/20 rule based on your net income
- □ Calculate your expenses and set realistic spending limits
- □ Set up a standing order to transfer 10-20% of your salary to savings
Week 3: Building Your Foundation
- □ Start building your emergency fund—even Sh500 is a start
- □ Research the best savings vehicle for you (bank account, M-Shwari, SACCO, or Money Market Fund)
- □ Identify areas where you can reduce expenses
Week 4: Planning for the Future
- □ Research beginner investment options—money market funds, SACCOs, or unit trusts
- □ Identify one skill you can invest in to boost your career
- □ Set a SMART financial goal for the next 12 months
Conclusion.
Your first salary is a powerful tool. Used wisely, it can set you on a path toward financial freedom. Used carelessly, it can lock you into a cycle of living paycheck to paycheck.
Key Takeaways from This First Salary Kenya Guide:
- Know your net pay before you start spending.
- Create a budget that works for your Kenyan context.
- Save first, spend later—pay yourself at least 10% of every income.
- Build an emergency fund to cover 3-6 months of expenses.
- Start investing early, even with small amounts like Sh1,000.
- Avoid lifestyle inflation—live below your means.
- Support family smartly without breaking your own budget.
- Invest in yourself—skills and education compound.
- Avoid common mistakes—don’t ignore savings, don’t chase get-rich-quick schemes.
Remember what CPA Ruth Omae reminds us: “It’s not how much you earn, it’s how you manage what you earn.” Financial freedom isn’t achieved overnight; it’s built paycheck by paycheck, choice by choice.
Your journey to financial freedom starts now. Every shilling you save and invest today is a down payment on the future you deserve. This first salary Kenya guide has given you the tools; now it’s time to take action.
“For a deeper dive into protecting your legacy, explore our comprehensive guide that breaks down The 5 essential differences between a Financial Power of Attorney and a Living Trust.”
Sources.
- Pulse Kenya. “Personal finance for young professionals: Managing your first salary in Kenya.” https://www.pulse.co.ke/story/personal-finance-for-young-professionals-managing-your-first-salary-in-kenya-2025102308584226897
- FXPesa. “Practical Steps To Saving.” https://support.fxpesa.com/hc/en-us/articles/27401309915793-Practical-Steps-To-Saving
- Business Daily. “Investing in 2026? Start smart, not scared.” https://www.businessdailyafrica.com/bd/lifestyle/personal-finance/investing-in-2026-start-smart-not-scared-5291302
- K24 Digital. “Just got your first salary? 10 smart money moves every Gen Z should make.” https://k24.digital/lifestyle/money/just-got-your-first-salary-10-smart-money-moves-every-gen-z-should-make
- K24 Digital. “5 common money mistakes Kenyans make after landing a new job.” https://k24.digital/heartbeat/5-common-money-mistakes-kenyans-make-after-landing-new-job
- Money254. “Sinking Fund: What It Is and 5 Reasons You Should Start One in 2023. ” https://www.money254.co.ke/post/sinking-fund-what-it-is-and-5-reasons-you-should-start-one-in-2023-money-management
- The Standard. “Early financial habits every student should start building today.” https://standardmedia.co.ke/evewoman/index.php/managing-your-money/article/2001530701/early-financial-habits-every-student-should-start-building-today
- The Standard. “What you should know about your first salary.” https://www.standardmedia.co.ke/evewoman/index.php/managing-your-money/article/2001540610/what-you-should-know-about-your-first-salary
- The Kenyan Wall Street. “Budgeting Tips to Start 2025 Right.” https://kenyanwallstreet.com/budgeting-tips-to-start-2025-right
- Daily Nation. “I got my first job, earned Sh40,000. But after expenses, help me with a savings plan.” https://nation.africa/kenya/life-and-style/saturday-magazine/i-got-my-first-job-earn-sh40-000-but-left-with-zero-after-expenses-help-me-with-a-savings-plan-5182670
- Payscale. “Average Early-Career Accountant with Financial Reporting Skills Salary in Kenya.” https://www.payscale.com/research/KE/Job=Accountant/Salary/f498acd5/Early-Career-Financial-Reporting
- LinkedIn (CPA Ruth Omae). “Payday Tips.” https://www.linkedin.com/posts/cpa-ruth-omae-b4a763162_personalfinance-financialwellness-moneymanagement-activity-7391830938692870144-68tH
- Streamline. “5 Smart Money Moves to Make After Landing Your First Job.” https://streamlinefeed.co.ke/news/5-smart-money-moves-to-make-after-landing-your-first-job
- The Star. “NJAGI: Are you working for your money, or is your money working for you? ” https://the-star.co.ke/business/commentary/2025-09-01-njagi-are-you-working-for-your-money-or-is-your-money-working-for-you
- Nax Today. “Kenyans Online Highlight Struggles in Viral Salary Clip.” https://nax.today/slider-stories-breaking-news-and-top-stories-in-kenya/article/3691/kenyans-online-highlight-struggles-in-viral-salary-clip