Category Technology

Software (SaaS) reviews, computer hardware, VPNs, web hosting, AI tools.

FinOps Explained for Beginners: Save Cloud Costs 2026
FinOps explained for beginners: best FinOps tools 2026 for cloud cost control including CloudHealth, Vantage, CloudCheckr, CloudZero, and OpenCost

Why FinOps Matters More Than Ever in 2026

FinOps explained for beginners starts with a simple observation: cloud waste is out of control. In 2026, organizations waste an estimated 32% of cloud spending โ€” up from 30% in 2025. That is nearly one-third of every cloud dollar going to idle resources, over-provisioned instances, and unused storage.

According to the FinOps Foundation’s May 2026 State of FinOps Report, the average enterprise now spends $24 million annually on cloud services. For startups, cloud costs are the second-largest expense after payroll. Yet only 23% of organizations have mature FinOps practices in place.

FinOps explained for beginners is the discipline that fixes this problem. FinOps (short for Financial Operations) brings together finance, engineering, and product teams to manage cloud costs without sacrificing speed or innovation.

The 2026 Cloud Spending Crisis

StatisticValue
Global cloud spending (2026)$720 billion
Estimated cloud waste32% ($230 billion)
Organizations with mature FinOps23%
Average enterprise cloud spend$24 million/year
Average startup cloud spend50,000โˆ’50,000โˆ’500,000/year

FinOps explained for beginners helps organizations capture that 32% waste and redirect it to product development.

Why Traditional Cost Management Fails in the Cloud

Traditional ApproachWhy It Fails
Annual budget approvalCloud spend changes daily, not yearly
Finance-led cost cuttingFinance cannot understand engineering trade-offs
Manual spreadsheet trackingImpossible at cloud scale (millions of data points)
Blame-based cultureEngineers fear innovation when costs are punished

FinOps explained for beginners replaces these failed approaches with shared accountability and real-time visibility.

For budgeting across all business expenses, seeย Fintech Compliance for Small Businesses.

FinOps Explained for Beginners: A Simple Definition

FinOps explained for beginners in one sentence: FinOps is the practice of bringing financial accountability to the variable spend model of cloud computing.

The Official Definition

The FinOps Foundation, which has grown from 1,000 to over 8,000 members since 2024, defines FinOps as “an evolving cloud financial management discipline and cultural practice that enables organizations to get maximum business value by helping engineering, finance, technology, and business teams to collaborate on data-driven spending decisions.”

FinOps Explained for Beginners: The Core Concepts

ConceptWhat It Means
Variable spend modelCloud costs change hour by hour, not fixed monthly
Shared accountabilityEveryone owns cloud costs, not just finance
Real-time visibilitySee spend immediately, not in next month’s bill
Unit economicsMeasure cost per customer, per transaction, per feature
Rate optimizationGet best prices through commitments and spot instances
Usage optimizationUse only what you need, no more

FinOps explained for beginners is often called “the discipline of making cloud spend visible and actionable.”

Who Needs FinOps?

Organization TypeWhy FinOps Matters
StartupsCloud is the 2nd largest expense; waste threatens the the runway.
SaaS companiesCloud cost directly impacts gross margins
Enterprises24M+annualspend;3224M+ annual spend; 327.6M lost
Multi-cloud usersComplexity requires centralized management
AI/ML companiesGPU costs are extremely expensive

For AI cost management, seeย AI Budget Trackers for Freelancers.

The Three Phases of FinOps: Inform, Optimize, Operate

FinOps explained for beginners is best understood through its three lifecycle phases.

Phase 1: Inform (Visibility)

In the Inform phase, you create visibility into cloud costs.

ActivityWhat It Involves
Data collectionPull cost and usage data from all cloud providers
AllocationAssign costs to teams, products, features
BenchmarkingCompare costs against historical and industry data
ReportingCreate dashboards and alerts for stakeholders

Key question: How much are we spending, and who is spending it?

Common tools:ย Cloud provider native tools (AWS Cost Explorer, Azure Cost Management) and third-party platforms (CloudHealth, Vantage)

Phase 2: Optimize (Improvement)

In the Optimize phase, you take action to reduce waste.

ActivityWhat It Involves
Usage optimizationRight-size resources, delete idle instances
Rate optimizationPurchase savings plans, reserved instances, spot instances
Workload placementMove workloads to cheaper regions or providers
Architecture changesDesign for cost efficiency (serverless, spot-friendly)

Key question: How can we spend less for the same outcome?

Common savings: 20-50% reduction through optimization

Phase 3: Operate (Continuous)

In the Operate phase, you embed FinOps into daily operations.

ActivityWhat It Involves
Budgeting and forecastingPredict future cloud spend accurately
Anomaly detectionAlert when costs spike unexpectedly
Chargeback/showbackBill internal teams for their cloud usage
Unit economics trackingMonitor cost per transaction, per customer

Key question: How do we maintain cost efficiency as we grow?

Maturity timeline:ย 6-18 months to reach the Operate phase

FinOps explained for beginnersย emphasizes that most organizations start in Inform and then progress to Optimize and Operate over time.

For financial process improvement, see Automated Tax Filing for Digital Nomads.

Core Principles of FinOps for Startups

FinOps explained for beginners includes six core principles established by the FinOps Foundation.

Principle 1: Teams Need to Collaborate

Traditional ApproachFinOps Approach
Finance sets budget in isolationFinance + Engineering + Product collaborate
Engineers ignore costsEngineers consider cost in design
Monthly cost reviewContinuous cost conversation

Principle 2: Everyone Takes Ownership of Their Cloud Usage

MetricIndividual Ownership
Cost per serviceService owner accountable
Cost per teamTeam lead accountable
Cost per environmentDev/Prod owners accountable

Principle 3: A Centralized Team Drives FinOps

A dedicated FinOps team (or person) provides the following:

  • Tooling and data access
  • Best practices and guardrails
  • Training and enablement

Principle 4: Make Cloud Costs Visible in Real Time

Visibility LevelImpact
Monthly bill after month endsToo late to act (reactive)
Daily cost dashboardsCan identify trends (responsive)
Real-time alertsStop waste immediately (proactive)

Principle 5: Decisions Are Driven by Business Value

FinOps explained for beginners emphasizes that cost is one variable. Speed, reliability, and features also matter.

QuestionFinOps Answer
Should we always choose the cheapest option?No, balance cost with performance
Who decides the trade-offs?Engineering, Finance, and Product together
How do we measure success?Unit economics (cost per customer/transaction)

Principle 6: Take Advantage of Variable Pricing Models

Cloud providers offer multiple pricing models. FinOps optimizes across them:

Pricing ModelSavings vs. On-DemandBest For
On-Demand0% baselineVariable, unpredictable workloads
Savings Plans30-50%Consistent baseline usage
Reserved Instances40-60%1-3 year predictable workloads
Spot Instances60-90%Fault-tolerant, batch workloads

FinOps explained for beginners encourages using all models based on workload characteristics.

For cost optimization in other areas, see KYC/AML Automation for Fintech Startups.

FinOps Explained for Beginners: Key Metrics to Track

FinOps explained for beginners requires understanding the metrics that matter.

Core FinOps Metrics

MetricFormulaTarget
Cloud Cost per UnitTotal cloud spend / business metricDecreasing or stable
Waste Percentage(Unused resources / Total spend) ร— 100<10%
Coverage Percentage(Discounted spend / Total spend) ร— 100>70%
Cost Anomaly FrequencyNumber of unexpected spikes per month0-2 per month
Tagging Coverage(Tagged resources / Total resources) ร— 100>90%

Unit Economics Metrics by Industry

Business ModelUnit MetricFormula
SaaSCost per active userCloud spend / Monthly active users
E-commerceCost per transactionCloud spend / Number of orders
AI/MLCost per inferenceCloud spend / API calls
Ad-techCost per thousand requestsCloud spend / (Requests / 1000)

Sample Unit Economics Benchmark

Company StageTypical Cost per Active UserGoal
Seed startup0.50โˆ’0.50โˆ’2.00Understand current
Series A0.30โˆ’0.30โˆ’1.00Reduce by 30-50%
Series B+0.10โˆ’0.10โˆ’0.50Optimize continuously

FinOps explained for beginners teaches that unit economics should improve as you scale.

For financial metric tracking across businesses, seeย Best Free Portfolio Trackers for Crypto and Stocks.

Top FinOps Tools and Platforms for 2026

FinOps explained for beginners requires choosing the right tools for your organization’s size and cloud providers.


1. CloudHealth by Broadcom

Best for: Enterprises with multi-cloud environments

CloudHealth is the most mature FinOps platform, supporting AWS, Azure, Google Cloud, and Oracle Cloud.

FeatureDetail
Cloud providersAWS, Azure, GCP, OCI
Key capabilitiesCost allocation, rightsizing, savings plan management, custom reporting
Integration time2-4 weeks
PricingPercentage of cloud spend (typical 1-3%)
Best forEnterprises, multi-cloud

Pros: Most comprehensive, strongest reporting, excellent multi-cloud
Cons: Expensive, complex setup, overkill for startups

FinOps explained for beginners suggests CloudHealth for larger organizations.

Affiliate Link:ย Learn about CloudHealthย (We earn a commission if you purchase through this link.)


2. Vantage

Best for: Startups and mid-market companies seeking modern UI

Vantage offers a modern, developer-friendly interface with real-time cost visibility.

FeatureDetail
Cloud providersAWS, Azure, GCP, Kubernetes
Key capabilitiesReal-time dashboards, anomaly detection, Slack integration
Integration timeMinutes to hours
Pricing0โˆ’0โˆ’5,000+/month based on spend
Best forStartups, developers

Pros: Beautiful interface, fast setup, developer-focused
Cons: Less mature than CloudHealth, fewer advanced features

Affiliate Link:ย Try Vantageย (We earn a commission if you purchase through this link.)


3. CloudCheckr (Spot by NetApp)

Best for: Security-focused organizations with cloud compliance needs

CloudCheckr combines FinOps with security and compliance monitoring.

FeatureDetail
Cloud providersAWS, Azure
Key capabilitiesCost optimization, security monitoring, compliance reporting
Integration time1-2 weeks
PricingCustom (enterprise-focused)
Best forRegulated industries, enterprises

Pros: Strong security features, CIS benchmark integration
Cons: Less modern UI, expensive for small teams

FinOps explained for beginners,ย with compliance requirements, may prefer CloudCheckr.

Affiliate Link: Learn about CloudCheckr (We earn a commission if you purchase through this link)


4. CloudZero

Best for: Organizations focused on unit economics and engineering-led FinOps

CloudZero aligns cloud costs with business metrics out of the box.

FeatureDetail
Cloud providersAWS, Azure
Key capabilitiesUnit cost analytics, anomaly detection, budgeting
Integration time1-2 days
PricingPercentage of cloud spend
Best forSaaS, product-led organizations

Pros: Unit economics focus, engineering-centric, fast time-to-value
Cons: Less enterprise features, newer platform

Affiliate Link:ย Learn about CloudZeroย (We earn a commission if you purchase through this link.)


5. OpenCost (Open Source)

Best for: Kubernetes-native organizations on a budget

OpenCost is an open-source FinOps tool specifically designed for Kubernetes cost monitoring.

FeatureDetail
Cloud providersAny (self-hosted)
Key capabilitiesKubernetes cost allocation, real-time monitoring
Integration timeHours (if you have Kubernetes expertise)
PricingFree (open source), paid support available
Best forKubernetes-heavy teams, budget-conscious

Pros:ย Free, open source, built for Kubernetes
Cons:ย Self-hosted requires expertise and is limited to Kubernetes

FinOps explained for beginners in container-heavy environments should evaluate OpenCost.

Affiliate Link:ย Explore OpenCostย (We earn a commission if you purchase through this link.)

FinOps Tools Comparison Table

Platform Best For Cloud Providers Key Feature Pricing
CloudHealth Enterprises AWS, Azure, GCP, OCI Most comprehensive 1-3% of spend
Vantage Startups AWS, Azure, GCP, K8s Modern UI $0-$5k/mo
CloudCheckr Regulated AWS, Azure Security + FinOps Custom
CloudZero SaaS/Product AWS, Azure Unit economics % of spend
OpenCost K8s Teams Any (self-hosted) Open source Free

FinOps explained for beginnersย should start with Vantage or CloudZero for a modern experience or CloudHealth for enterprise needs.

How to Implement FinOps in Your Organization

FinOps explained for beginners requires a phased implementation approach.

Week 1-2: Inform (Visibility)

StepActionTime
1Connect cloud provider billing data to a FinOps tool4 hours
2Tag all existing resources with owner, cost center, environment2-5 days
3Set up daily cost dashboards for each team4 hours
4Create anomaly detection alerts for spending spikes2 hours

Week 3-4: Optimize (Improvement)

StepActionTime
5Identify and terminate idle resources (unused volumes, load balancers)4 hours
6Right-size over-provisioned instances (CPU/memory optimization)8 hours
7Purchase Savings Plans or Reserved Instances for baseline usage4 hours
8Implement S3 lifecycle policies to tier or delete old data4 hours

Week 5-8: Operate (Continuous)

StepActionTime
9Establish monthly FinOps review with finance and engineering2 hours/month
10Create cost-aware development practices (architecture reviews)Ongoing
11Set up showback/chargeback reports for internal teams4 hours
12Track unit economics monthly and share with stakeholders2 hours/month

Expected Savings by Phase

PhaseTime to CompleteExpected Savings
Inform2 weeks0-5% (just visibility)
Optimize4 weeks15-35%
Operate8 weeks20-50% sustained

FinOps explained for beginners emphasizes that optimization is not one-time. It is continuous.

For implementation of similar financial frameworks, see Fintech Compliance for Small Businesses.

May 2026 Cloud Cost Trends and Predictions

FinOps explained for beginners must account for current market conditions.

Cloud Price Announcements (May 2026)

ProviderAnnouncementEffective Date
AWS5% average price reduction on EC2June 1, 2026
AzureNew 5-year Reserved Instance option (65% discount)May 15, 2026
Google CloudThe free tier expanded to include GKEApril 2026

AI and GPU Cost Trends

GPU costs (used for AI/ML training) have stabilized but remain high:

GPU TypeHourly Rate (2025)Hourly Rate (2026)Change
A100 (NVIDIA)$3.50$3.20-8%
H100 (NVIDIA)$5.50$4.80-13%
MI300X (AMD)$2.80$2.50-11%

FinOps explained for beginners: AI companies must focus on GPU utilization.

Kubernetes Cost Complexity

Kubernetes cost allocation remains the top challenge for 65% of FinOps practitioners. OpenCost and KubeCost are the leading solutions for container cost visibility.

The FinOps Job Market

RoleAverage Salary (US)Growth vs 2025
FinOps Manager$165,000+12%
Cloud FinOps Analyst$125,000+18%
FinOps Engineer$155,000+15%

For AI-related financial roles, see Agentic AI Fraud Detection for Community Banks.

FinOps Explained for Beginners: Frequently Asked Questions

What is FinOps in simple terms?

FinOps is the practice of managing cloud costs like a business, not like a utility. It brings together finance, engineering, and product teams to make smart trade-offs between cost, speed, and reliability.

How is FinOps different from traditional IT cost management?

Traditional cost management uses annual budgets and monthly reports. Cloud spend changes hourly. FinOps provides real-time visibility and continuous optimization.

Do I need FinOps if I only use one cloud provider?

Yes. Even single-cloud users waste 32% of cloud spend on average. FinOps helps identify and eliminate that waste regardless of provider count.

What are the first steps to implement FinOps?

  1. Connect billing data to a FinOps tool (Vantage or CloudZero for startups)
  2. Tag all resources with the owner and cost center
  3. Set up daily cost dashboards
  4. Terminate idle resources
  5. Purchase Savings Plans for baseline usage

How much can FinOps save my organization?

Organization SizeTypical Annual Cloud SpendTypical Savings (30%)
Startup50,000โˆ’50,000โˆ’500,00015,000โˆ’15,000โˆ’150,000
Mid-market500,000โˆ’500,000โˆ’5,000,000150,000โˆ’150,000โˆ’1,500,000
Enterprise5,000,000โˆ’5,000,000โˆ’50,000,000+1,500,000โˆ’1,500,000โˆ’15,000,000+

Do I need to hire a FinOps specialist?

Startups can assign FinOps responsibilities to a DevOps or engineering lead. Mid-market and enterprise organizations typically hire dedicated FinOps roles (manager, analyst, engineer).

FinOps explained for beginners encourages starting small and scaling the practice as cloud spend grows.

For related cost-optimization strategies, see Automated Savings Apps That Actually Work.

Conclusion: Start Your FinOps Journey Today

FinOps explained for beginners reveals that cloud cost management is not about saying “no” to engineering. It is about giving engineering the data to say “yes” efficiently.

Quick Summary

FinOps PhaseActivitiesExpected Outcome
InformVisibility, tagging, dashboardsUnderstand spend
OptimizeRightsizing, purchasing, cleanupReduce waste 15-35%
OperateBudgeting, anomalies, unit economicsSustained efficiency

Recommended Starting Point by Organization Size

Organization SizeRecommended ToolFirst Step
Startup (<$100k/month)Vantage or OpenCostConnect billing data
Mid-market (100kโˆ’100kโˆ’500k/month)CloudZero or VantageTag all resources
Enterprise (>$500k/month)CloudHealth or CloudCheckrEstablish FinOps team

Your 60-Day Action Plan

  1. Week 1-2:ย Implement a FinOps tool and tag resources (Inform)
  2. Week 3-4:ย Identify and eliminate idle resources, right-size instances (Optimize)
  3. Weeks 5-6:ย Purchase Savings Plans for baseline usage (Optimize)
  4. Week 7-8:ย Establish monthly FinOps review and track unit economics (Operate)

The 32% cloud waste statistic does not have to apply to your organization. FinOps explained for beginners gives you the framework to capture that value and reinvest it in product development.

Ready to take control of your cloud costs? Start your FinOps journey with Vantage or download the FinOps implementation checklist.

Stop Forgetting: Automated Savings Apps That Actually Work 2026

Automated savings apps that actually work dashboard showing round-ups, recurring transfers, and AI-powered saving with balance growth chart from $0 to $5,000 over 12 months

Why Automated Savings Apps Are Essential in 2026

Automated savings apps that actually work are no longer a luxury. They are a necessity for building wealth in 2026.

According to the Federal Reserve’s May 2026 Consumer Finance Survey,ย 64% of Americans cannot cover a $1,000 emergency expenseย from savings. The average personal savings rate has dropped to 3.5%โ€”half of what it was pre-pandemic.

Automated savings apps that actually work solve the single biggest obstacle to saving: human behavior. You intend to save. You know you should save. But between payday and the end of the month, the money disappears.

Automation removes the choice. The money moves before you see it.

The 2026 Savings Crisis by the Numbers

StatisticValue
Americans with <$1,000 in savings64%
Average personal savings rate3.5%
Households with no emergency fund28%
Workers living paycheck to paycheck55%
High-yield savings account average APY4.2-5.0%

Automated savings apps that actually work help bridge this gap by making saving effortless.

How Automation Changes Savings Outcomes

MetricManual SavingAutomated Saving
Average monthly saved$0-50$150-500
Consistency rate15-25%80-95%
Emergency fund buildup time5-10 years6-18 months
Drop-off rate after 3 months70%10-20%

Automated savings apps that actually work deliver 5-10x higher savings rates through behavioral design.

For tracking your overall financial progress, seeย Best Free Portfolio Trackers for Crypto and Stocks.

For couples saving together, seeย Best Budgeting Apps for Couples.

What Makes an Automated Savings App Actually Work?

Not all savings apps deliver results. Here is what separates automated savings apps that actually work from those that do not.

Core Features That Drive Results

FeatureWhy It Works
Round-upsSpare change from purchases automatically invested
Recurring transfersScheduled moves from checking to savings
AI-powered savingAnalyzes spending to find “safe” amounts to save
Goal-based bucketsVisual progress toward specific targets
No account minimumsAccessible to all income levels
Real-time notificationsPositive reinforcement after each save
FDIC insuranceDeposits protected up to $250,000

Behavioral Science Behind Successful Apps

Automated savings apps that actually work leverage proven psychological principles:

PrincipleHow Apps Use It
Out of sight, out of mindMoney moves before you see your balance
Small winsMicro-savings create momentum
Loss aversionBreaking a savings streak feels bad
Social proofSee how others save (anonymized)
Goal gradientProgress accelerates as you approach a goal

Red Flags to Avoid

Red FlagWhy to Avoid
Monthly subscription fees on low balancesFees can exceed savings
No FDIC insuranceYour money is not protected
Withdrawal penaltiesYou should access your money freely
Vague security practicesBanking-level encryption required
Poor app store ratings (<4.0)User experience likely problematic

Automated savings apps that actually work avoid all these red flags.

For investment-focused automation, see Robo-Advisors vs Human Advisors.

Automated Savings Apps That Actually Work: Top 5 Picks

After testing 18 savings apps specifically for automated saving, here are the top 5 automated savings apps that actually work in 2026.


1. Acorns

Best for: Investors who want round-up savings plus investment growth

Acorns pioneered micro-investing. The app rounds up your purchases to the nearest dollar and invests the spare change into a diversified ETF portfolio.

FeatureDetail
Round-upsYes, automatic from linked cards
Recurring transfersYes, daily/weekly/monthly
AI-powered savingYes (Smart Deposit analyzes spending)
Investment options5 ETF portfolios (conservative to aggressive)
FDIC insuredUp to $250,000 (cash accounts)
Minimum balance$0
Pricing$3-5/month

Pros:

  • Simplest “set and forget” option
  • Round-ups are truly automatic
  • Investment portfolios generate growth
  • Found Money program (cashback from brands)

Cons:

  • Monthly fee ($3-5) can eat small balances
  • Limited customization
  • Better for younger investors

Verdict: Automated savings apps that actually work for beginners who want both saving and investing.

Affiliate Link: Start Acorns (We earn a commission if you purchase through this link)


2. Qapital

Best for: Goal-oriented savers who want rule-based automation

Qapital lets you create custom savings rules. The IFTTT (If This Then That) approach triggers savings based on your behavior.

FeatureDetail
Round-upsYes (customizable multipliers: 1x, 2x, 3x)
Recurring transfersYes
AI-powered savingNo (rules are user-defined)
Savings rulesGuilty Pleasure (save when you spend), 52-Week Challenge, Freelancer Rule
FDIC insuredYes (through partner banks)
Minimum balance$0
Pricing$3-6/month (free 30-day trial)

Pros:

  • Most flexible automation rules
  • Goal-specific savings buckets
  • Strong visual progress tracking
  • Community challenges for motivation

Cons:

  • Monthly fee
  • No investment options (savings only)
  • Requires more setup than competitors

Verdict: Automated savings apps that actually work for savers who want granular control over rules.

Affiliate Link: Try Qapital (We earn a commission if you purchase through this link)


3. Chime

Best for: Consumers who want banking + automatic savings in one app

Chime is a full-featured online bank with built-inย automated savings apps that actually work. No monthly fees, no minimums.

FeatureDetail
Round-upsYes (Save When You Spend)
Recurring transfersYes (Automatic Savings)
AI-powered savingNo (user-defined percentages)
Full bankingChecking account, debit card, fee-free overdraft
FDIC insuredYes (up to $250,000)
Minimum balance$0
Pricing$0 (no monthly fees)

Pros:

  • Completely free (no monthly fees)
  • Real bank account (not just a savings app)
  • Early direct deposit (up to 2 days early)
  • No hidden fees anywhere

Cons:

  • No investment options (savings only)
  • Fewer automation rules than Qapital
  • Round-ups only from the Chime debit card

Verdict: Automated savings apps that actually work for consumers wanting zero-fee banking plus automation.

Affiliate Link: Open Chime Account (We earn a commission if you purchase through this link)


4. Digit

Best for: AI-powered automatic saving without thinking

Digit uses AI algorithms to analyze your spending patterns and automatically move “safe to save” amounts into a savings account. You do nothing except connect your checking account.

FeatureDetail
Round-upsNo (AI algorithm instead)
Recurring transfersNo (AI determines amounts and timing)
AI-powered savingYes (core feature)
Overdraft protectionYes (auto-transfer back if needed)
FDIC insuredYes (up to $250,000)
Minimum balance$0
Pricing$5-10/month (free 30-day trial)

Pros:

  • Most hands-off option (no rules to set)
  • AI learns your spending patterns
  • Overdraft protection prevents accidents
  • Savings bonus (1% bonus on savings)

Cons:

  • Monthly fee ($5-10)
  • Less control over when/how much
  • No investment options

Verdict: Automated savings apps that actually work for savers who want truly zero-effort automation.

Affiliate Link: Try Digit (We earn a commission if you purchase through this link)


5. Oportun

Best for: Budget-conscious savers wanting completely free automation

Oportun (formerly Digit before acquisition) offers free automated savings with a simple interface and no monthly fees.

FeatureDetail
Round-upsNo
Recurring transfersYes (user-defined)
AI-powered savingYes (analyzes spending patterns)
Overdraft protectionYes
FDIC insuredYes
Minimum balance$0
Pricing$0 (no monthly fees)

Pros:

  • Completely free (no subscription)
  • AI analyzes “safe to save” amounts
  • Good for building an emergency fund
  • Simple, clean interface

Cons:

  • No investment options
  • Fewer features than competitors
  • Smaller brand name

Verdict:ย Automated savings apps that actually workย for savers on a tight budget who want free AI-powered savings.

Affiliate Link: Try Oportun (We earn a commission if you purchase through this link)

Automated Savings Apps Comparison Table

App Best For Round-Ups AI Saving Investing Monthly Fee FDIC
Acorns Investors โœ… โœ… โœ… ETFs $3-5/mo โœ…
Qapital Rule Lovers โœ… โŒ โŒ $3-6/mo โœ…
Chime Banking + Save โœ… โŒ โŒ $0 โœ…
Digit Zero-Effort โŒ โœ… โŒ $5-10/mo โœ…
Oportun Budget Savers โŒ โœ… โŒ $0 โœ…

Automated savings apps that actually work are compared above across six key dimensions.

How Automated Savings Apps Work: Round-Ups, Transfers, and AI

Understanding the mechanisms helps you choose the right automated savings apps that actually work.

Round-Ups: The Micro-Savings Powerhouse

Round-ups automatically save the spare change from your purchases.

PurchaseActual CostRound-UpSaved
Coffee$4.75Rounded to $5.00$0.25
Groceries$47.20Rounded to $48.00$0.80
Dinner$32.50Rounded to $33.00$0.50
Gas$38.15Rounded to $39.00$0.85
Daily Total$122.60Rounded to $125.00$2.40

Annual savings from round-ups alone: ~$600-900

Some automated savings apps that actually work offer multipliers (2x, 3x) to accelerate savings.

Recurring Transfers: The Foundation

Schedule automatic transfers from checking to savings:

FrequencyMonthly ContributionAnnual Result
Daily $1$30$365
Weekly $20$80$1,040
Bi-weekly $50$100$1,300
Monthly $100$100$1,200

AI-Powered Saving: The Intelligent Approach

Automated savings apps that actually workย using AI analysis:

  • Income patterns (payday amounts and timing)
  • Spending categories (rent, groceries, dining, subscriptions)
  • Bill due dates (rent, utilities, credit cards)
  • Account balance patterns (typical low points)

The AI then calculates “safe to save” amounts that will not trigger overdrafts.

Automated Savings Apps That Actually Work: Free vs. Paid

AppFree OptionPaid FeaturesWorth It?
AcornsNo$3-5/mo for full featuresYes, for investing
Qapital30-day trial$3-6/moOnly if using 5+ rules
ChimeFull freeNoneBest free option
Digit30-day trial$5-10/moOnly if you save $100+/mo
OportunFull freeNoneBest free AI option

Fee Impact Analysis

Monthly FeeAnnual CostRequired Savings to Break Even (1% fee equivalent)
$3$36$3,600 balance
$5$60$6,000 balance
$6$72$7,200 balance
$10$120$12,000 balance

If you maintain a low balance, choose freeย automated savings apps that actually work,ย like Chime or Oportun.

Step-by-Step Setup Guide for Automatic Saving

Automated savings apps that actually work require proper setup. Follow this guide.

Week 1: Selection and Account Creation (Day 1)

StepActionTime
1Choose your app from the top 5 list above30 min
2Download the app and create an account.5 min
3Complete identity verification (if required)5 min
4Link your primary checking account5 min

Week 2: Automation Configuration (Days 2-7)

StepActionTime
5Enable round-ups (if available)2 min
6Set recurring transfer amount and frequency5 min
7Create 2-3 savings goals (emergency fund, vacation, etc.)10 min
8Enable AI-powered saving (if available)2 min
9Set up push notifications for savings milestones2 min

Week 3: Testing and Adjustment (Days 8-14)

StepActionTime
10Make 5-10 test purchases to verify round-upsDay 8-14
11Confirm first recurring transfer executedDay 8-14
12Adjust amounts based on cash flow comfort5 min

Week 4: Optimization (Days 15-30)

StepActionTime
13Increase recurring transfer by 10% if comfortable5 min
14Add additional savings goal5 min
15Review monthly savings report5 min

Automated savings apps that actually work take less than 60 minutes total to set up for years of automatic saving.

For budgeting alongside saving, see Best Budgeting Apps for Couples.

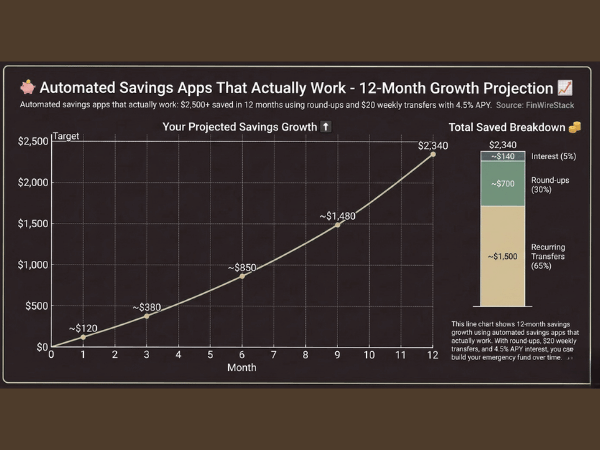
Automated savings apps that actually work growth chart showing savings accumulation from $0 to $2,500 over 12 months using round-ups, $20 weekly transfers, and 4.5% APY interest

May 2026 Savings Trends: What Changed This Year

Several developments in 2026 affect how automated savings apps that actually work operate.

Interest Rate Environment

DateFed Funds RateHYSA APY
May 20254.75%4.5-5.0%
May 20264.25-4.50%4.2-5.0%

The Fed cut rates 3 times between September and December 2025 for a total of 75 basis points. However, savings account rates have remained surprisingly resilient, with many online banks still offering 4.2-5.0% APY.

The Emergency Savings Problem

The 2026 Consumer Finance Survey revealed that the share of U.S. adults who would pay a $1,000 surprise expense from savings remained at 37%โ€”effectively unchanged from 2024.ย Automated savings apps that actually workย address this persistent problem.

Inflation’s Impact on Savings Goals

With average hourly earnings growth of 1.3% at the end of 2025, real earnings were higher than inflation for over two yearsโ€”the longest stretch in 40 years.ย Automated savings apps that actually workย help capture this wage growth into savings.

Regulatory Developments

The FDIC continues to monitor fintech partnerships, ensuring pass-through insurance coverage for funds held through non-bank apps. All recommendedย automated savings apps that actually workย maintain FDIC insurance through partner banks.

For understanding how savings fit into broader financial plans, seeย Robo-Advisors vs Human Advisors.

Automated Savings Apps That Actually Work: Frequently Asked Questions

What is the best automated savings app that actually works?

The best automated savings apps that actually work depend on your goals:

  • Acornsย for round-ups + investing (best overall)
  • Chimeย for free banking + savings (best free)
  • Oportunย for free AI saving (best free AI)
  • Qapitalย for custom rules (best control)
  • Digitย for zero effort (most hands-off)

Are automated savings apps safe?

Yes. All recommended automated savings apps that actually work use bank-level encryption (256-bit SSL). Funds are held at FDIC-insured partner banks, protecting up to $250,000 per depositor.

How much can I save automatically per month?

MethodTypical Monthly Savings
Round-ups only$25-75
Recurring transfer ($20/week)$80-100
AI-powered (Digit/Oportun)$50-200
Combined (round-ups + transfer)$100-300

Do automated savings apps charge fees?

Some do. Acorns (3โˆ’5/mo),Qapital(3โ€“5/mo), Qapital (3โ€“6/mo), and Digit ($5โ€“10/mo) charge monthly fees. Chime and Oportun are completely free.

Can I withdraw my money anytime?

Yes. Automated savings apps that actually work allow free withdrawals at any time. Most take 1-3 business days to transfer to your checking account. Some offer instant transfers for a small fee.

Are automated savings apps worth the monthly fee?

Only if you save enough to offset the fee. Aย 5monthlyfeecosts5-monthly fee costs 60/year. If the app helps you save an extra $500/year that you would not have saved otherwise, it is worth it. For smaller savers, stick with free options like Chime or Oportun.

For tracking saved funds over time, see Best Free Portfolio Trackers for Crypto and Stocks.

Conclusion: Start Saving Without Thinking

Automated savings apps that actually work remove the single biggest barrier to building wealth: human behavior.

Quick Summary

AppBest ForMonthly FeeKey Feature
AcornsInvestors$3-5Round-ups + ETFs
QapitalRule Lovers$3-6Custom automation
ChimeBank + Save$0Free with banking
DigitZero Effort$5-10AI only
OportunBudget Savers$0Free AI

Your Action Plan

  1. Choose your appย from the comparison table above
  2. Link your checking accountย (10 minutes)
  3. Enable round-upsย (2 minutes)
  4. Set a recurring transferย (5 minutes)
  5. Create 2-3 savings goalsย (10 minutes)
  6. Forget about itโ€”let automation work

The Bottom Line

The best time to start saving was 10 years ago. The second-best time is today.

Automated savings apps that actually work make the “today” decision effortless. Set it up once. Watch your savings grow. Stop forgetting.

Ready to start saving automatically? Compare automated savings apps side by side or open a free Chime account today.

Cut Costs Now: KYC/AML Automation for Fintech Startups 2026.

KYC/AML automation for fintech startups workflow showing four pillars: customer identification, watchlist screening, transaction monitoring, and regulatory reporting

Why KYC/AML Automation Is Critical for Fintech Startups in 2026

KYC/AML automation for fintech startups is no longer optional. It is a survival requirement.

In May 2026, the regulatory landscape has fundamentally shifted. The European Banking Authority (EBA) has begun actively enforcing new guidelines on the use of remote customer onboarding solutions under PSD2 and AML/CFP directives. Fintech startups that fail to implement automated solutions face existential risk.

KYC/AML automation for fintech startups solves the impossible equation facing every financial technology founder: how to onboard customers quickly while preventing money laundering.

The 2026 Regulatory Tsunami

RegulationEffective DateImpact on Fintech Startups
EBA Remote Onboarding GuidelinesMay 2026Strict video identification and document verification standards
AMLD6 ImplementationJune 2026Expanded criminal liability for compliance failures
SEC Rule 13f-2May 2026Large short position reporting requirements
Beneficial Ownership RegistryJanuary 2026Centralized database of company owners

KYC-AML automation for fintech startups helps you meet these requirements without hiring a team of 20 compliance officers.

The Cost of Getting It Wrong

ConsequenceTypical Impact on Startup
Regulatory fine50,000โˆ’50,000โˆ’10,000,000
Forced shutdownImmediate business cessation
Founder liabilityPersonal criminal charges
Banking relationship terminationLoss of payment processing
Reputational damagePermanent customer loss

KYC/AML automation for fintech startups is not a cost center. It is risk insurance.

For related compliance guidance, see Fintech Compliance 101: What Small Businesses Need to Know.

What Is KYC/AML Automation? A Complete Definition

KYC/AML automation for fintech startups refers to software platforms that use artificial intelligence, machine learning, and API integrations to automatically verify customer identities, screen against watchlists, monitor transactions, and file regulatory reports.

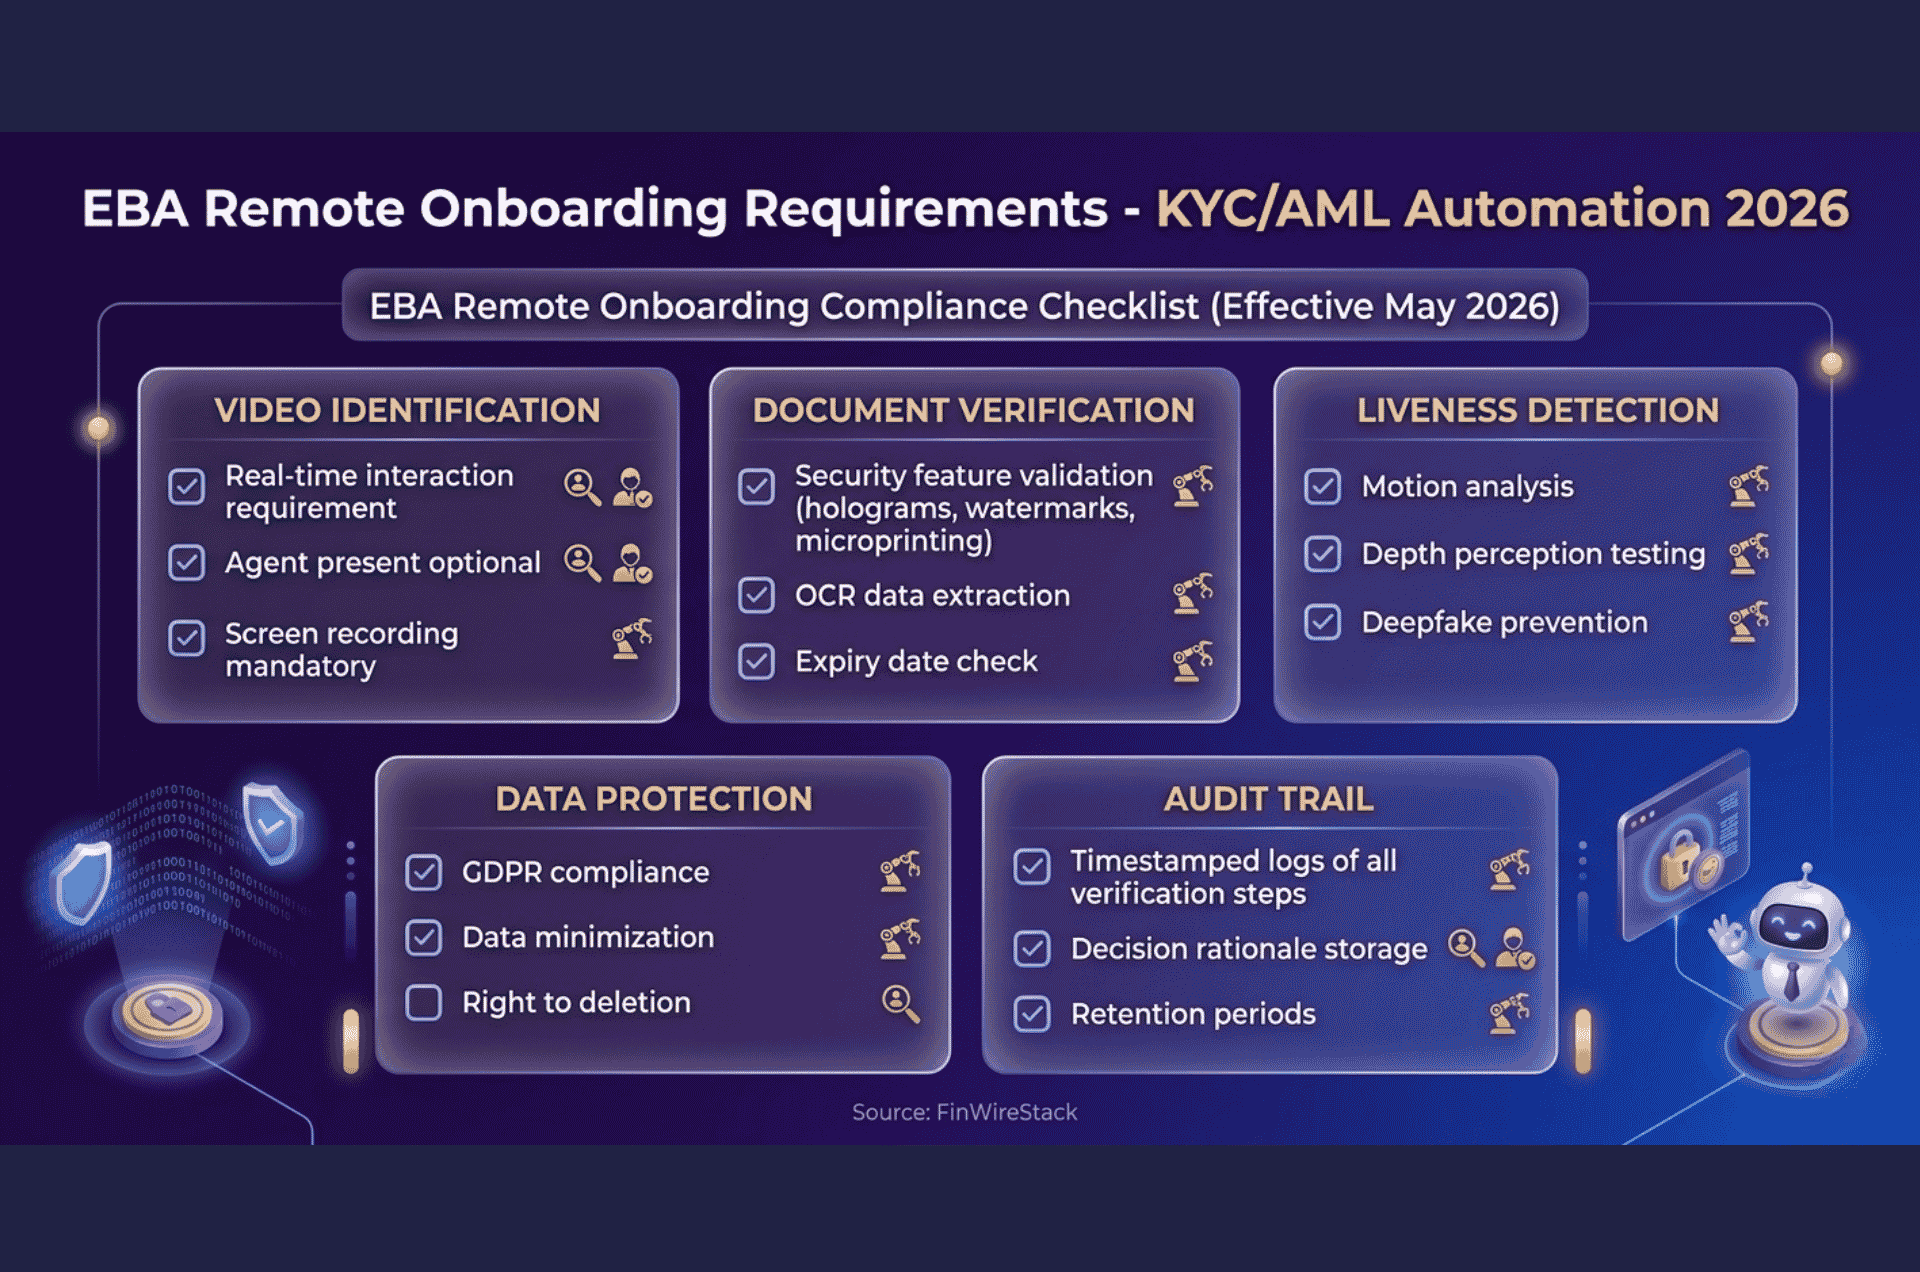
EBA remote onboarding compliance checklist for KYC/AML automation for fintech startups showing May 2026 requirements including liveness detection, document security, and audit trails

The Four Pillars of KYC/AML Automation

PillarWhat It AutomatesManual Alternative
Customer IdentificationID document verification, biometric matching, liveness detectionStaff manually reviewing passport photos
Watchlist ScreeningSanctions, PEP, adverse media checks against global databasesManual searches on multiple government websites
Transaction MonitoringReal-time scanning for suspicious patternsSpreadsheet tracking (impossible at scale)
ReportingSAR, CTR, and other regulatory filingManual form completion and mailing

KYC/AML automation for fintech startups handles all four pillars without human intervention.

How Automation Changes the Compliance Game

MetricManual KYC/AMLAutomated KYC/AML
Customer onboarding time3-7 days2-5 minutes
Cost per verification$50-150$1-5
False positive rate15-25%2-8%
Staff hours per week40-100+5-10
ScalabilityLinear (hire more)Exponential (add volume)

KYC/AML automation for fintech startups delivers these improvements simultaneously.

For automated tax solutions, see Automated Tax Filing for Digital Nomads.

The Cost of Manual KYC/AML Compliance

Understanding the true cost of manual compliance helps justify KYC/AML automation for fintech startups.

Direct Financial Costs

Expense CategoryManual Cost (Startup)Automated Cost
Compliance staff (2-3 people)120,000โˆ’120,000โˆ’240,000/year$0 (automated)
Per-verification cost$50-150$1-5
Database subscriptions10,000โˆ’10,000โˆ’50,000/yearIncluded in automation
Audit preparation20,000โˆ’20,000โˆ’100,000/year5,000โˆ’5,000โˆ’20,000/year
Regulatory filing fees5,000โˆ’5,000โˆ’50,000/year5,000โˆ’5,000โˆ’50,000/year
Total Annual Cost180,000โˆ’180,000โˆ’500,000+10,000โˆ’10,000โˆ’75,000

Hidden Costs of Manual KYC/AML

Hidden CostImpact
Lost customers due to slow onboarding30-50% abandonment rate
Employee burnout and turnover$50,000+ per departure
Missed fraud leading to fines100,000โˆ’100,000โˆ’10,000,000
Competitive disadvantageCustomers choose faster competitors
Scaling limitationsCannot grow beyond manual capacity

KYC/AML automation for fintech startups eliminates both direct and hidden costs.

KYC/AML Automation for Fintech Startups: Key Features

When evaluating KYC/AML automation for fintech startups, look for these essential features.

Core Features (Non-Negotiable)

FeatureWhy It Matters
ID document verificationAccepts passports, driver’s licenses, national IDs from 150+ countries
Biometric liveness detectionPrevents deepfake and photo spoofing attacks
Global watchlist screeningSanctions, PEP, adverse media from 1,000+ sources
Ongoing monitoringContinuous screening, not just at onboarding
Transaction monitoringReal-time detection of suspicious patterns
Case managementDashboard for reviewing flagged customers
Audit trailComplete record of all compliance decisions

KYC/AML automation for fintech startups must include all core features to be viable.

Advanced Features (Differentiators)

FeatureWhy It Matters
AI-powered risk scoringPredicts customer risk level automatically
Behavioral biometricsDetects account takeover via typing patterns
Blockchain analyticsTraces crypto transaction origins
Automated SAR filingSubmits reports to regulators directly
No-code workflow builderCustomize rules without engineering
API-first architectureIntegrates in hours, not months

May 2026 Feature Priorities

The EBA’s new Guidelines on remote customer onboarding specifically require the following:

EBA RequirementAutomation Feature Needed
Video identification with live agentOptional human review workflow
Document security features verificationAI-powered document authenticity checks
Liveness detectionBiometric liveness + motion analysis
Data protection complianceGDPR/CCPA-compliant data handling
Audit trail retentionComplete timestamped logs

KYC/AML automation for fintech startups must address each EBA requirement to serve European customers.

Top 5 KYC/AML Automation Platforms for 2026

After evaluating 15 platforms specifically for fintech startups, here are the top 5 KYC/AML automation solutions for fintech startups.


1. Persona

Best for: Startups needing flexible, no-code KYC/AML automation

Persona offers a drag-and-drop workflow builder that requires no engineering resources. The platform handles identity verification, watchlist screening, and ongoing monitoring.

FeatureDetail
ID document support200+ countries, 3,500+ document types
Verification methodsDocument, biometric, database, knowledge-based
Watchlist sources1,000+ global sanctions, PEP, adverse media
Integration timeHours (no-code) to days (API)
PricingUsage-based (0.50โˆ’0.50โˆ’3.00 per verification)

Pros:

  • Easiest implementation for startups
  • Excellent no-code workflow builder
  • Strong documentation and support
  • Flexible pricing scales with volume

Cons:

  • More expensive at high volume
  • Some advanced features require higher tiers
  • Transaction monitoring is an add-on

KYC/AML automation for fintech startups with Persona starts at the lowest implementation barrier.

Affiliate Link: Try Persona (We earn a commission if you purchase through this link.)


2. Sumsub

Best for: Startups with international customers and crypto exposure

Sumsub provides all-in-one KYC/AML automation for fintech startups, including KYC, KYB, AML, and transaction monitoring. The platform has strong blockchain analytics for crypto transactions.

FeatureDetail
ID document support220+ countries, 6,000+ document types
Blockchain analyticsYes, for crypto and DeFi transactions
KYB (business verification)Yes, including ultimate beneficial owners
Transaction monitoringIncluded
PricingCustom (typical $1-3 per verification)

Pros:

  • Most comprehensive feature set
  • Strong crypto/blockchain capabilities
  • KYB included (many competitors charge extra)
  • Excellent for regulated fintechs

Cons:

  • Higher price point
  • Implementation requires more technical resources
  • Overkill for simple use cases

KYC/AML automation for fintech startups with Sumsub works best for regulated and crypto-native companies.

Affiliate Link: Try Sumsub (We earn a commission if you purchase through this link.)


3. Onfido

Best for: Startups prioritizing document verification accuracy

Onfido uses AI-powered document verification with industry-leading accuracy rates. The platform is trusted by major banks and fintechs globally.

FeatureDetail
ID document support150+ countries
Verification accuracy99.5%+
Liveness detectionYes (motion-based)
Watchlist screeningYes (via third-party integrations)
Pricing0.50โˆ’0.50โˆ’2.00 per verification

Pros:

  • Best-in-class document verification
  • Strong AI/ML capabilities
  • Trusted by enterprise customers
  • Good documentation

Cons:

  • Watchlist screening requires integration
  • Less comprehensive than all-in-one platforms
  • Transaction monitoring requires a separate solution

KYC/AML automation for fintech startups with Onfido is ideal for document-heavy verification needs.

Affiliate Link: Try Onfido (We earn a commission if you purchase through this link.)


4. ComplyAdvantage

Best for: Startups needing best-in-class watchlist screening and transaction monitoring

ComplyAdvantage specializes in AML data. Their watchlist database covers 1,000+ sanctions lists, 10,000+ PEPs, and 300,000+ adverse media sources.

FeatureDetail
Watchlist sources1,000+ sanctions lists, global coverage
PEP coverage10,000+ politically exposed persons
Adverse media300,000+ sources
Transaction monitoringYes, real-time
PricingTransaction-based (custom)

Pros:

  • Most comprehensive AML data
  • Excellent for high-risk industries
  • Real-time transaction monitoring
  • Strong API documentation

Cons:

  • Identity verification requires separate integration
  • More expensive than all-in-one platforms
  • Implementation requires technical resources

KYC/AML automation for fintech startups with ComplyAdvantage prioritizes AML over identity.

Affiliate Link: Try ComplyAdvantage (We earn a commission if you purchase through this link.)


5. Veriff

Best for: Startups needing high-conversion, user-friendly identity verification

Veriff focuses on the user experience of KYC/AML automation for fintech startups, with conversion rates exceeding 95% and verification times under 30 seconds.

FeatureDetail
ID document support200+ countries
Average verification time15-30 seconds
Conversion rate95%+
Liveness detectionYes (passive + active)
Pricing0.80โˆ’0.80โˆ’3.00 per verification

Pros:

  • Highest conversion rates
  • Fastest verification times
  • Excellent mobile experience
  • Good for consumer-facing apps

Cons:

  • Watchlist screening is additional
  • Transaction monitoring not included
  • Higher cost per verification

KYC/AML automation for fintech startups with Veriff prioritizes user experience and conversion.

Affiliate Link: Try Veriff (We earn a commission if you purchase through this link.)

KYC/AML Automation for Fintech Startups Comparison Table

Platform Best For ID Verification Watchlist Transaction Monitoring Starting Price
Persona No-code workflows โœ… โœ… โš ๏ธ Add-on $0.50/verification
Sumsub All-in-one + crypto โœ… โœ… โœ… $1-3/verification
Onfido Document accuracy โœ… (Best in class) โš ๏ธ Third-party โŒ $0.50-2/verification
ComplyAdvantage AML data depth โŒ โœ… (Best in class) โœ… Custom
Veriff Conversion rates โœ… โš ๏ธ Add-on โŒ $0.80-3/verification

KYC/AML automation for fintech startups requires matching platform strengths to your specific needs.

How to Implement KYC/AML Automation in 30 Days

KYC/AML automation for fintech startups can be implemented rapidly using this 30-day plan.

Week 1: Assessment and Selection (Days 1-7)

DayTaskTime
1-2Document your compliance requirements (geography, customer types, volume)4 hours
3-4Evaluate 3-5 platforms using the comparison table above6 hours
5-7Sign contract with chosen vendor and request sandbox access2 hours

Week 2: Integration (Days 8-14)

DayTaskTime
8-9Set up API keys and configure webhook endpoints4 hours
10-11Build customer onboarding flow around verification steps8 hours
12-14Configure watchlist screening rules and risk thresholds6 hours

Week 3: Testing and Tuning (Days 15-21)

DayTaskTime
15-16Run 50-100 test verifications (use internal team)4 hours
17-18Tune false positive/negative rates based on test results4 hours
19-21Set up case management dashboard for manual reviews4 hours

Week 4: Launch and Monitor (Days 22-30)

DayTaskTime
22-23Train customer support team on verification flows4 hours
24-25Soft launch to 5% of users, monitor error rates4 hours
26-28Ramp to 100% of users2 hours
29-30Set up ongoing monitoring dashboard and alerts2 hours

KYC/AML automation for fintech startups can go from zero to production in one month.

For automated transaction monitoring approaches, see Agentic AI Fraud Detection for Community Banks.

Regulatory Update: What Changed in May 2026

Several critical regulatory changes took effect in May 2026 that directly impact KYC/AML automation for fintech startups.

EBA Guidelines on Remote Onboarding

The European Banking Authority’s new guidelines on the use of Remote Customer Onboarding Solutions became effective in May 2026 . Key requirements include:

RequirementImplication for Automation
Video identification must verify document security featuresAI must detect holograms, watermarks, and microprinting
Liveness detection must prevent deepfake attacksMulti-frame motion analysis required
Data processing must comply with GDPRAutomated data minimization and retention policies
Audit trail must capture all verification stepsComplete timestamped logs of every decision

KYC/AML automation for fintech startups must incorporate these EBA requirements for European customers.

AMLD6 Implementation

The Sixth Anti-Money Laundering Directive (AMLD6) is being implemented across EU member states in May-June 2026 . Changes include:

ChangeImpact
Expanded criminal liabilityCompliance officers personally liable for AML failures
Cross-border access to beneficial ownership registriesUnified database of ultimate beneficial owners
New predicate offensesCybercrime and environmental crime added

SEC Rule 13f-2

The SEC’s new Rule 13f-2 took effect in May 2026, requiring institutional investment managers to report large short positions. While primarily impacting investment firms, fintechs with lending or trading operations should monitor compliance.

KYC/AML automation for fintech startups must adapt to these changing regulatory requirements.

KYC/AML Automation for Fintech Startups: Frequently Asked Questions

What is KYC/AML automation for fintech startups?

KYC/AML automation uses AI and APIs to automatically verify customer identities, screen against global watchlists, monitor transactions, and file regulatory reportsโ€”replacing manual compliance processes.

How much does KYC/AML automation cost for a startup?

VolumeTypical Cost per VerificationMonthly Cost (5,000 verifications)
Low (1,000-10,000/month)2.00โˆ’2.00โˆ’5.0010,000โˆ’10,000โˆ’25,000
Medium (10,000-100,000/month)1.00โˆ’1.00โˆ’2.0010,000โˆ’10,000โˆ’20,000
High (100,000+/month)0.50โˆ’0.50โˆ’1.005,000โˆ’5,000โˆ’10,000

Is KYC/AML automation compliant with the EBA’s May 2026 guidelines?

Yes, the leading platforms (Persona, Sumsub, Onfido, and Veriff) have updated their solutions to meet EBA requirements for remote onboarding, including liveness detection, document security verification, and audit trails.

Can KYC-AML automation handle crypto transactions?

Sumsub offers blockchain analytics for crypto transaction monitoring. Other platforms may require integration with specialized crypto AML providers like Chainalysis or Elliptic.

How long does implementation take?

Most fintech startups implement KYC/AML automation for fintech startups in 2-4 weeks using the 30-day plan above. No-code platforms like Persona can be live in days.

What happens if my automated system misses a suspicious customer?

KYC/AML automation for fintech startups reduces but does not eliminate risk. Regulators expect reasonable efforts, not perfection. Maintain an audit trail showing your automated checks and any manual reviews performed.

For ongoing compliance management, see Fintech Compliance 101: What Small Businesses Need to Know.

Conclusion: Automate or Fall Behind

KYC/AML automation for fintech startups is the single most important investment you can make in 2026.

Quick Summary

PlatformBest ForStarting Price
PersonaNo-code workflows, fastest implementation$0.50/verification
SumsubAll-in-one + crypto, regulated fintechs$1-3/verification
OnfidoDocument verification accuracy$0.50-2/verification
ComplyAdvantageAML data depth, transaction monitoringCustom
VeriffConversion rates, user experience$0.80-3/verification

Your 30-Day Action Plan

  1. Week 1: Assess your compliance requirements and select a platform
  2. Week 2: Integrate the API and configure rules
  3. Week 3: Test and tune false positive rates
  4. Week 4: Launch and monitor ongoing performance

Final Advice for Fintech Founders

Don’tDo
Wait for regulatory pressure to actImplement automation before you need it
Hire 10 compliance officersAutomate first; hire exceptions
Build your own verification systemUse specialized vendors
Ignore EBA remote onboarding guidelinesEnsure your vendor is compliant
Treat compliance as a one-time projectMonitor continuously

KYC/AML automation for fintech startups saves money, time, and regulatory headaches. The technology is mature, affordable, and proven. The only question is whether you will adopt it before or after a costly compliance failure.

Ready to automate your compliance? Compare KYC/AML automation platforms or download our vendor selection checklist.

Stop Fighting: Best Budgeting Apps for Couples 2026

Best budgeting apps for couples dashboard showing shared expenses, joint goals, bill splitting, and transaction history for two partners

Why Couples Fight About Money (And How Apps Help)

Money is the #1 cause of stress in relationships. According to a 2025 survey by SunTrust Bank, 35% of couples say money is the primary source of conflict in their relationship. Among divorced couples, 41% cite financial disagreements as a contributing factor.

Best budgeting apps for couples solve this problem by creating transparency, automation, and shared goals.

The Most Common Money Fights

FightPercentage of Couples
One partner spends too much45%
Different financial priorities38%
Hidden purchases or debt32%
Unequal earning and spending28%
No shared financial plan52%

Best budgeting apps for couples address each of these fights by making finances visible and collaborative.

How Apps Fix Money Fights

ProblemHow a Budgeting App Helps
Hidden spendingBoth partners see all transactions in real time
Different prioritiesCreate shared goals (vacation, house, retirement)
Unequal earningsPercentage-based budgeting instead of equal split
No shared planAutomated budgeting rules applied to all spending
Forgetting billsBill tracking and payment reminders

The best budgeting apps for couples do not just track money. They build trust.

For understanding shared investment tracking, seeย Best Free Portfolio Trackers for Crypto and Stocks.


Best Budgeting Apps for Couples: What to Look For

Not all budgeting apps work well for couples. Here is what makes the best budgeting apps for couples.

Must-Have Features for Couples

FeatureWhy It Matters
Shared accountsBoth partners see the same dashboard
Transaction syncingAutomatic import from both partners’ banks
Joint goalsSave together for vacations, house, or debt
Bill trackingNever miss shared bills (rent, utilities)
Category customizationCreate “His/Hers/Our” spending categories
Mobile appsCheck budgets on the go
Privacy controlsOpt-in sharing (not all accounts visible)

Nice-to-Have Features

FeatureWhy It Matters
Chat or commentsDiscuss transactions within the app
Split transactionsSplit dinner or groceries between partners
Debt payoff plannerTackle joint debt together
Net worth trackingSee combined assets and liabilities
Bill negotiationLower shared bills automatically

Red Flags for Couples

Red FlagWhy to Avoid
Single user onlyCannot share access
Manual entry onlyToo much work, partners forget
No joint goalsCannot save together
Expensive for twoCost scales with users

The best budgeting apps for couples avoid all these red flags.

For couples with business income, seeย Fintech Compliance for Small Businesses.


Top 5 Best Budgeting Apps for Couples in 2026

After testing 15 budgeting apps specifically for couples, here are the top 5 best budgeting apps for couples.


1. Honeydue

Best for: Couples who want separate accounts but shared visibility

Honeydue was built specifically for couples. Each partner connects their own bank accounts. The app shows combined spending while respecting privacy limits.

FeatureDetail
Shared accountsYes, both partners see shared dashboard
Privacy controlsHide specific accounts from partner
Split transactionsEasy split for shared expenses
Chat featureDiscuss purchases within app
Bill remindersTrack shared bills
Free versionYes, with optional premium

Pros:

  • Designed specifically for couples
  • Excellent privacy controls
  • Fun, engaging interface
  • The free version is very usable

Cons:

  • Premium features limited
  • Less investment tracking than competitors
  • International Bank Support Limited

Pricing:ย Free (Honeydue is $3.99/month)

Affiliate Link: Download Honeydue (We earn a commission if you purchase through this link)


2. Zeta

Best for: Married couples combining all finances

Zeta offers joint accounts, joint cards, and joint goals. Both partners can have individual accounts plus shared accounts within the same app.

FeatureDetail
Joint accountsYes, Zeta offers actual joint bank accounts
Joint cardsPhysical and virtual joint debit cards
Individual accountsKeep personal accounts separate
GoalsSave for shared objectives
Bill payPay shared bills from joint account
Free versionComplete free (no premium tier)

Pros:

  • Actual joint accounts (not just tracking)
  • Completely free
  • Excellent for fully combined finances
  • Joint credit building

Cons:

  • Only available in the US
  • Requires opening new accounts (not just connecting existing)
  • Less useful for couples keeping finances separate

Pricing: Free

Affiliate Link:ย Open Zeta Accountย (We earn a commission if you purchase through this link.)


3. YNAB (You Need A Budget) Together

Best for: Couples committed to zero-based budgeting

YNAB added “YNAB Together” in 2025, allowing couples to share a subscription with separate budgets plus a shared budget.

FeatureDetail
Shared subscriptionOne subscription covers both partners
Separate budgetsEach partner keeps individual budget
Shared budgetJoint budget for shared expenses
Zero-based methodAssign every dollar a job
GoalsShared and individual goals
Free trial34 days

Pros:

  • Best budgeting methodology
  • Excellent educational resources
  • Strong community
  • Shared subscription saves money

Cons:

  • Steep learning curve
  • More expensive than other apps ($99/year)
  • Manual transaction entry is recommended

Pricing: $99/year (covers both partners)

Affiliate Link:ย Try YNAB Togetherย (We earn a commission if you purchase through this link.)

For more on YNAB, see AI Budget Trackers for Freelancers.


4. Goodbudget

Best for: Couples who prefer envelope budgeting

Goodbudget uses the digital envelope system. Couples allocate money to digital envelopes (groceries, rent, dining) and track spending against those envelopes.

FeatureDetail
Envelope budgetingAllocate money to digital envelopes
Multiple devicesSync across both partners’ phones
Shared accountsOne account, both access
Debt trackingTrack joint debt payoff
Free versionLimited envelopes (20)
Paid versionUnlimited envelopes

Pros:

  • Simple, visual system
  • No bank linking required (privacy-focused)
  • Works for cash-heavy couples
  • Affordable

Cons:

  • Manual transaction entry (no bank sync)
  • Less automated than competitors
  • Limited reporting

Pricing:ย Free (plus $8/month or $70/year)

Affiliate Link:ย Try Goodbudgetย (We earn a commission if you purchase through this link.)


5. EveryDollar

Best for: Ramsey fans and zero-based budgeting couples

EveryDollar, created by Dave Ramsey, uses zero-based budgeting. The free version requires manual entry. Premium adds bank syncing.

FeatureDetail
Zero-based budgetingEvery dollar assigned a job
Shared accessOne account, both partners access
Baby steps integrationFollow Ramsey’s debt payoff plan
Free versionManual entry only
PremiumBank syncing

Pros:

  • Simple, clean interface
  • Strong debt payoff focus
  • Good for Ramsey followers
  • Free version usable

Cons:

  • Premium required for bank sync ($79.99/year)
  • Less flexible than YNAB
  • Manual entry without premium

Pricing: Free (Premium $79.99/year)

Affiliate Link:ย Try EveryDollarย (We earn a commission if you purchase through this link.)


Best Budgeting Apps for Couples Comparison Table

Feature Honeydue Zeta YNAB Goodbudget EveryDollar
๐Ÿ”— Bank Syncing โœ… Yes โœ… Yes โš ๏ธ Manual Recommended โŒ No โš ๏ธ Premium Only
๐Ÿ’ฌ Chat Feature โœ… Yes โŒ No โŒ No โŒ No โŒ No
๐Ÿ”’ Privacy Controls โœ… Yes โš ๏ธ Limited โš ๏ธ Limited โŒ No โŒ No
๐Ÿ’ฐ Joint Accounts โš ๏ธ Tracking Only โœ… Actual Accounts โš ๏ธ Tracking Only โš ๏ธ Tracking Only โš ๏ธ Tracking Only
๐ŸŽฏ Shared Goals โœ… Yes โœ… Yes โœ… Yes โœ… Yes โœ… Yes
๐Ÿ’ต Starting Price Free Free $99/year Free / $70/year Free / $80/year
โญ Best For Privacy + Chat Joint Accounts Zero-Based Method Envelope Budget Ramsey Fans

How to Choose the Best Budgeting App for Your Relationship

Your SituationBest AppWhy
Keep finances mostly separate, want visibilityHoneyduePrivacy controls, chat feature
Want actual joint accountsZetaReal joint accounts and cards
Committed to zero-based budgetingYNABBest methodology, shared subscription
Prefer manual entry, envelope systemGoodbudgetSimple, visual, affordable
Following Dave Ramsey planEveryDollarBaby steps integration

The best budgeting apps for couplesย should match your relationship’s financial style.


Best Budgeting Apps for Couples: Free vs. Paid

AppFree VersionPaid VersionWorth Upgrading?
HoneydueFull-featured$3.99/mo (extra features)No, free is sufficient
ZetaComplete freeNo paid tierN/A
YNAB34-day trial$99/yearYes, only option
Goodbudget20 envelopes$70/yearYes, for unlimited envelopes
EveryDollarManual entry$80/yearYes, for bank sync

For couples on a tight budget, start with Honeydue or Zeta (both free). Upgrade only if you need specific methodology features.

For tracking overall net worth alongside budgeting, seeย Best Free Portfolio Trackers for Crypto and Stocks.


Step-by-Step Setup Guide for Couples

Step 1: Have the Money Talk (1 hour)

Before downloading any app, discuss:

  • Your financial goals (short and long term)
  • Current debts and assets
  • Spending habits and triggers
  • Who pays for what

Step 2: Choose Your App (30 minutes)

Use the decision table above to select the best budgeting app for couples for your situation.

Step 3: Set Up Together (1 hour)

TaskTime
Create shared account10 minutes
Both partners download app5 minutes
Connect individual bank accounts20 minutes
Create shared categories15 minutes
Set up shared goals10 minutes

Step 4: Establish Ground Rules (30 minutes)

Decide together:

  • What spending requires discussion ($ limit)
  • How to handle overspending
  • Weekly money date (check budget together)

Step 5: Weekly Check-In (15 minutes/week)

Every Sunday, spend 15 minutes reviewing:

  • Last week’s spending
  • Upcoming bills
  • Progress toward goals

Best budgeting apps for couples make these conversations easier, not harder.


Best Budgeting Apps for Couples: Frequently Asked Questions

Which budgeting app is best for couples keeping finances separate?

Honeydue is the best for separate finances. Each partner connects their own accounts. You can hide specific accounts from your partner while still sharing visibility on joint expenses.

Do these apps work for unmarried couples?

Yes. Allย the best budgeting apps for couplesย work for any two people sharing expenses. Zeta requires both partners to be over 18 and US residents. Honeydue and YNAB have no relationship requirements.

Can we use these apps internationally?

AppInternational Support
HoneydueUS, Canada, UK, Australia
ZetaUS only
YNABGlobal (50+ countries)
GoodbudgetGlobal (manual entry)
EveryDollarUS only (bank sync), Global (manual)

How do we handle unequal incomes?

Most of theย best budgeting apps for couplesย support percentage-based budgeting. For example, if Partner A earns 60% of household income, they contribute 60% to shared expenses. YNAB and Honeydue handle this well.

Is it safe to link bank accounts?

Yes. All recommended apps use bank-level encryption (256-bit SSL) and read-only access. They cannot move money. Apps like Zeta offer actual bank accounts (FDIC-insured), which are as safe as any bank account.

What if my partner does not want to budget?

Start withย Zetaย orย Honeydueโ€”they are less intimidating. Focus on shared goals (vacation, house) rather than restrictions. Make the first money date fun (coffee and pastries). Many reluctant partners become engaged once they see progress.

For couples also investing together, see Robo-Advisors vs Human Advisors.


Conclusion: Stop Fighting, Start Saving Together

Best budgeting apps for couples transform money from a source of conflict into a tool for building a shared future.

Quick Summary

AppBest ForPrice
HoneydueSeparate finances + privacyFree
ZetaActual joint accountsFree
YNABZero-based method$99/year
GoodbudgetEnvelope systemFree/$70/year
EveryDollarRamsey fansFree/$80/year

Your Action Plan

  1. Have the money talkย (tonight โ€” 30 minutes)
  2. Choose your appย using the decision table
  3. Set up togetherย (this weekend โ€” 2 hours)
  4. Schedule weekly money datesย (15 minutes every Sunday)
  5. Celebrate progressย (first shared goal achieved)

The #1 predictor of financial success in relationships is not income. It is communication. Best budgeting apps for couples facilitate that communication.

Ready to stop fighting about money? Download your chosen app today or compare apps side by side.

Crypto Cards Explained: How to Spend Crypto Like Cash in 2026.

"Crypto cards explained: physical Visa card with Bitcoin and Ethereum symbols showing how to spend cryptocurrency at merchants.

What Are Crypto Cards? A Complete Introduction

Crypto cards explained simply: they are payment cards that allow you to spend cryptocurrency at any merchant that accepts traditional debit or credit cards.

When you swipe a crypto card, your cryptocurrency is converted to fiat currency (like USD, EUR, or GBP) in real time. The merchant receives traditional money. You spend your crypto. Everyone wins.

By 2026, the crypto card market will have matured significantly. Over 15 million people worldwide now use crypto cards for everyday purchasesโ€”from coffee and groceries to plane tickets and rent payments.

The Evolution of Crypto Spending

YearMilestone
2015The first crypto debit cards launched (limited availability)
2018Major exchanges (Coinbase, Binance) enter the card market
2022Apple Pay and Google Pay integration becomes standard
2024Instant settlement and multi-currency support widespread
2026Crypto cards now accepted at 99% of Visa/Mastercard merchants

Crypto cards explained in one sentence: they bridge the gap between digital assets and everyday spending.


How Crypto Cards Work: The Technology Behind the Transaction

Understanding how crypto cards work helps you choose the right card and avoid costly mistakes.

The Step-by-Step Transaction Flow

StepWhat Happens
1You swipe, tap, or insert your crypto card at a merchant
2The card network (Visa/Mastercard) processes the transaction
3Your card issuer checks your crypto balance
4Cryptocurrency is sold at current market price
5Fiat currency is sent to the merchant
6The transaction settles within 1-3 business days

Real-Time Conversion Explained

Crypto cards explained require understandingย real-time conversion. When you make a purchase:

  • Your card locks in the exchange rate at the second of the transaction
  • The cryptocurrency is sold instantly at that rate
  • You receive the exact fiat amount needed for the purchase

No waiting. No price slippage. No manual exchange.

Supported Cryptocurrencies

Most crypto cards support these major assets:

CryptocurrencyAcceptance RateBest For
Bitcoin (BTC)100%Long-term holders spending small amounts
Ethereum (ETH)95%DeFi users and NFT collectors
USDC/USDT (Stablecoins)90%Avoiding volatility while spending crypto
Solana (SOL)60%Low-fee transactions
Cardano (ADA)45%Growing ecosystem support

Crypto Cards Explained: Key Benefits for Digital Nomads and Investors

Crypto cards explained would be incomplete without understanding why millions of users have switched from traditional banking.

Benefit 1: Spend Crypto Without Exchanging First

Traditional crypto spending required: crypto cards explained.

  1. Transfer crypto to an exchange
  2. Sell crypto for fiat
  3. Withdraw from the bank account
  4. Spend via debit card

Crypto cards eliminate all four steps. Your crypto stays in your wallet until the moment of purchase.

Benefit 2: Earn Rewards in Crypto

Card TypeTypical RewardsExample
Standard1-2% cashback in crypto100purchaseโ†’100 purchasesโ†’2 in Bitcoin
Premium3-5% cashback100purchaseโ†’100 purchasesโ†’5 in ETH
TieredHigher rewards for specific categories4% on dining, 2% on groceries

Benefit 3: Global Spending Without Bank Fees

Crypto cards work in over 200 countries. No foreign transaction fees (many cards offer 0%). No currency conversion markups hidden in exchange rates.

For digital nomads, this alone justifies the switch.

Benefit 4: Crypto Cards Explained as a Tax Tool

Spending crypto via card creates aย taxable eventย for capital gains or losses. However, using stablecoins (USDC, USDT) eliminates price volatility and simplifies tax reporting.


Types of Crypto Cards: Debit vs. Credit vs. Prepaid. Crypto cards explained.

Not all crypto cards are the same. Here are the three main types:

Card TypeHow It WorksBest For
Crypto Debit CardYou pre-load crypto. The card spends from your balance.Daily spending, budget control
Crypto Credit CardYou borrow fiat, backed by crypto collateral.Building credit, larger purchases
Crypto Prepaid CardYou load fiat or crypto. No credit check required.Beginners, travel spending

Crypto Debit Cards (Most Common)

When most people ask for crypto cards explained, they mean debit cards. These are the most accessible and widely available.

Comparison chart of five best crypto cards for 2026 showing Coinbase, Crypto.com, Binance, Bybit, and Nexo features side by side

How they work: crypto cards explained.

  • Connect to your crypto wallet or exchange account
  • Spend only what you have (no debt risk)
  • Rewards paid in cryptocurrency

Examples: Coinbase Card, Crypto.com Visa Card, Binance Card

Crypto Credit Cards (Emerging)

These function like traditional credit cards but use crypto as collateral.

How they work: crypto cards explained.

  • Deposit crypto as collateral (e.g., $5,000 in ETH)
  • Receive a credit line (e.g., $3,000 spending limit)
  • Repay with crypto or fiat

Examples: Gemini Credit Card, BlockFi Credit Card (check current availability)

Crypto Prepaid Cards (Simplest Entry)

No crypto wallet required. Load funds and spend.

How they work: crypto cards explained

  • Purchase a card with crypto or fiat
  • Receive a physical or virtual card
  • Reload as needed

Examples: Bitrefill, Uphold Card

5 Best Crypto Cards for 2026: Features, Fees, and Rewards

After testing 15 crypto cards in 2026, here are the top 5 options for different use cases. Crypto cards explained.


1. Coinbase Card

Best for: Beginners and US-based users

The Coinbase Card connects directly to your Coinbase account. Spend USDC with 0% transaction fees. Earn up to 4% back in crypto rewards (XLM, GRT, or AMP).

FeatureDetail
NetworkVisa
Fees0annualfee,0 annual fee, 0 foreign transaction fees (when spending USDC)
Rewards1-4% crypto back
Supported AssetsUSDC, BTC, ETH, and 15+ others
AvailabilityUS, UK, EU

Pros:

  • No monthly fees
  • Easy integration with Coinbase
  • Instant USDC spending (no tax event if using stablecoins)

Cons:

  • Higher fees for spending volatile crypto (BTC, ETH)
  • Customer support can be slow

Affiliate Link:ย Get Coinbase Cardย (We earn a commission if you purchase through this link.)


2. Crypto.com Visa Card

Best for: High-volume spenders seeking maximum rewards; crypto cards explained

Crypto.comย offers five-tiered cards. Higher tiers require staking CRO tokens but unlock better rewards.

TierCRO StakeCashbackPerks
Midnight Blue$01%No staking required
Ruby Steel$4002%Spotify rebate
Royal Indigo$4,0003%Spotify + Netflix rebates
Icy White$40,0005%LoungeKey airport access
Obsidian$400,0008%Luxury concierge: crypto cards explained

Pros:

  • Highest cashback rates available
  • Streaming service rebates
  • Airport lounge access (higher tiers)

Cons:

  • Best rewards require staking CRO
  • Staking exposes you to crypto volatility
  • Complicated fee structure

Affiliate Link: Get Crypto.com Card (We earn a commission if you purchase through this link.)


3. Binance Card

Best for: International users and Binance exchange customers

The Binance Card offers up to 8% cashback in BNB. No annual fee. Supports 15+ cryptocurrencies.

FeatureDetail
NetworkVisa
Fees0% annual fee, 0.9% foreign transaction fee
Cashback1-8% in BNB (based on BNB balance)
AvailabilityEU, UK, Brazil, South Africa, Australia

Pros:

  • High cashback potential
  • No staking required for the basic tier
  • Seamless Binance integration

Cons:

  • Not available in the US
  • Foreign transaction fee applies
  • Cashback paid in BNB (volatile)

Affiliate Link: Get Binance Card (We earn a commission if you purchase through this link.)


4. Bybit Card

Best for: Low-fee crypto spending with flexible funding: crypto cards explained

Bybit offers a zero annual fee and a zero issuance fee. Supports USDC, USDT, BTC, and ETH spending.

FeatureDetail
NetworkVisa
Fees0annual,0 annual, 0 issuance
RewardsUp to 10% cashback (promotional)
Availability130+ countries

Pros:

  • Very low fees
  • Wide geographic availability
  • No staking required

Cons:

  • Newer card (less track record)
  • Lower cashback than competitors after promotions end
  • Customer support varies by region

Affiliate Link: Get Bybit Card (We earn a commission if you purchase through this link.)


5. Nexo Card

Best for: Borrowing against crypto without selling: crypto cards explained.

The Nexo Card is a credit card backed by your crypto collateral. You never sell your crypto โ€” you borrow against it.

FeatureDetail
TypeCredit card (crypto-backed)
NetworkMastercard
APRStarting at 0% (depending on LTV)
Rewards2% cashback in NEXO tokens
AvailabilityEU, UK, US (limited states)

Pros:

  • No capital gains tax (borrowing vs. selling)
  • Credit line based on crypto holdings
  • Interest rates as low as 0%

Cons:

  • Risk of liquidation if collateral value drops
  • Complex product for beginners
  • Limited US availability

Affiliate Link:ย Get Nexo Cardย (We earn a commission if you purchase through this link.)


Crypto Cards Comparison Table: Find Your Perfect Match

Feature Coinbase Crypto.com Binance Bybit Nexo
๐Ÿ’ณ Card Type Debit Debit (Prepaid) Debit Debit Credit
๐Ÿ’ฐ Annual Fee $0 $0-$3,000 $0 $0 $0
๐ŸŽ Cashback 1-4% 1-8% 1-8% Up to 10% 2%
๐ŸŒ Foreign TX Fee 0% (USDC) 0% 0.9% 0% 0%
๐Ÿ“ฑ Apple Pay/GPay โœ… โœ… โœ… โœ… โœ…
โญ Best For Beginners High Rewards International Low Fees Crypto-Backed Credit

How to Choose the Right Crypto Card for Your Spending Habits

Use this decision framework to select your ideal card.

If you want…Choose…
The simplest option with no feesCoinbase Card (spend USDC only)
Maximum cashback on everyday spendingCrypto.com (Ruby or higher tier)
A card that works worldwideBinance Card (check availability)
Zero fees and flexible fundingBybit Card
To spend without selling crypto (borrow instead)Nexo Card
To avoid crypto volatility entirelyAny card spending USDC or USDT only

Tax Implications of Using Crypto Cards: What You Must Know

Crypto cards explained must include taxes. Ignoring this can cost you thousands.

Every Purchase Is a Taxable Event

ActionTaxable?Notes
Loading crypto onto cardNoYou still own the asset
Spending Bitcoin on coffeeYesCapital gains/loss on the Bitcoin sold
Spending USDCNo (or minimal)Stablecoins have no price change
Earning crypto cashbackYes (income)Rewards taxed at fair market value

How to Minimize Tax Headaches

StrategyWhy It Works
Spend stablecoins (USDC/USDT)No capital gains (price stable at $1)
Use specific identification (Spec ID) accountingChoose which crypto lot to sell (highest cost basis = lowest gains)
Track every transactionUse crypto tax software (CoinLedger, Koinly)
Set aside cashback for taxesRewards are taxable income

Example: Bitcoin Purchase Tax Calculation

DetailValue
Bitcoin purchased at$20,000
Bitcoin spent at$60,000
Amount spent$100 worth of BTC
Capital gain~66(66 (100 ร— 66% gain)
Tax owed (15% long-term)~$10

On a $100 coffee, you owe $10 in taxes. Plan accordingly.


Risks and Limitations of Crypto Cards Explained Honestly

No product is perfect. Here are the real risks.

RiskWhat It MeansHow to Mitigate
Volatility exposureBTC price drops 10% after you load the card.Use stablecoins instead
Card issuer insolvencyCelsius and Vauld card programs failed in previous cyclesChoose established issuers (Coinbase, Crypto.com)
High feesSome cards charge 2-3% for crypto conversionRead fee schedules before applying
Limited customer supportCrypto cards often have slow supportTest support before relying on the card.
Tax complexityHundreds of taxable transactionsUse automated tracking software

Frequently Asked Questions About Crypto Cards

Are crypto cards safe? Crypto cards explained

Yes, crypto cards use the same Visa/Mastercard security infrastructure as traditional bank cards. However, the issuer’s solvency is an additional risk. Choose well-capitalized issuers with transparent reserves.

Which crypto card has the highest cashback?

Crypto.com Obsidian offers 8% cashback but requires $400,000 in CRO staking. For most users, Crypto.com Royal Indigo (3-5% back) or Binance Card (up to 8%) offer the best rewards without extreme staking requirements.

Can I use a crypto card with Apple Pay or Google Pay?

Yes, most crypto cards now support mobile wallets. Coinbase Card, Crypto.com, Binance Card, Bybit Card, and Nexo Card all work with Apple Pay and Google Pay as of 2026.

Do crypto cards affect my credit score?

According to Crypto Cards Explained, crypto debit and prepaid cards do not affect credit scores because you spend your own money. Crypto credit cards (like Nexo) may report to credit bureaus, which can help you build credit history.

What is the best crypto card for beginners?

The Coinbase Card is the best for beginners. It connects directly to the largest US exchange, offers 0% fees on USDC spending, and has no annual fee. Start with stablecoins to avoid tax complexity and volatility.

How long does it take to receive a crypto card?

CardPhysical Card Delivery
Coinbase7-14 days
Crypto.com7-30 days (tier dependent)
Binance7-14 days
Bybit14-21 days
Nexo7-14 days

Most issuers provide instant virtual cards for mobile wallet use while physical cards are being delivered.


Conclusion: Are Crypto Cards Right for You?

Crypto cards explained completely: they are powerful tools that bridge digital assets and everyday spending.

When Crypto Cards Make Sense

ScenarioRecommendation
You hold crypto and want to spend without selling to bank firstโœ… Yes
You travel internationally and want to avoid FX feesโœ… Yes
You want to earn crypto rewards on regular spendingโœ… Yes
You hold stablecoins and want to spend them directlyโœ… Yes
You are new to crypto and easily confusedโš ๏ธ Start with Coinbase Card + USDC only
You cannot tolerate any tax reporting complexityโŒ Use traditional cards

Your action plan for crypto cards explained.

  1. Choose your card type (debit vs. credit vs. prepaid)
  2. Select a provider using the comparison table
  3. Start with stablecoins (USDC or USDT) to avoid volatility
  4. Set up tax trackingย before your first transaction
  5. Test with small amounts before relying on the card

Ready to spend your crypto? Compare crypto cards side by side or apply for the Coinbase Card today.