Category Economic Analysis

Nvidia Buyback Meets 5.2% Treasury Yields: What the AI Debt Dilemma Means for Investors
Nvidia buyback and bond yields

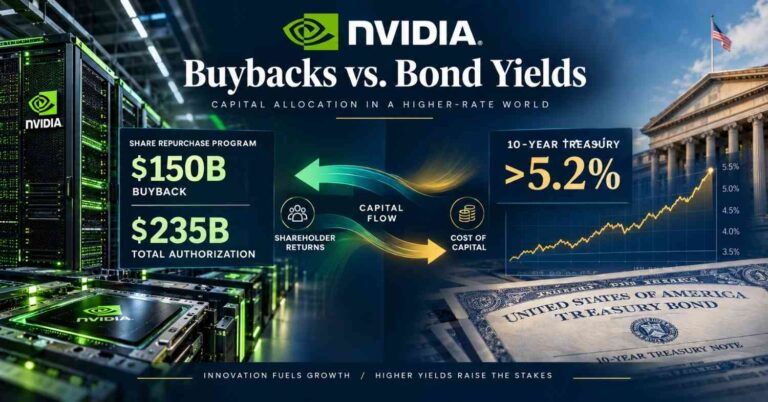
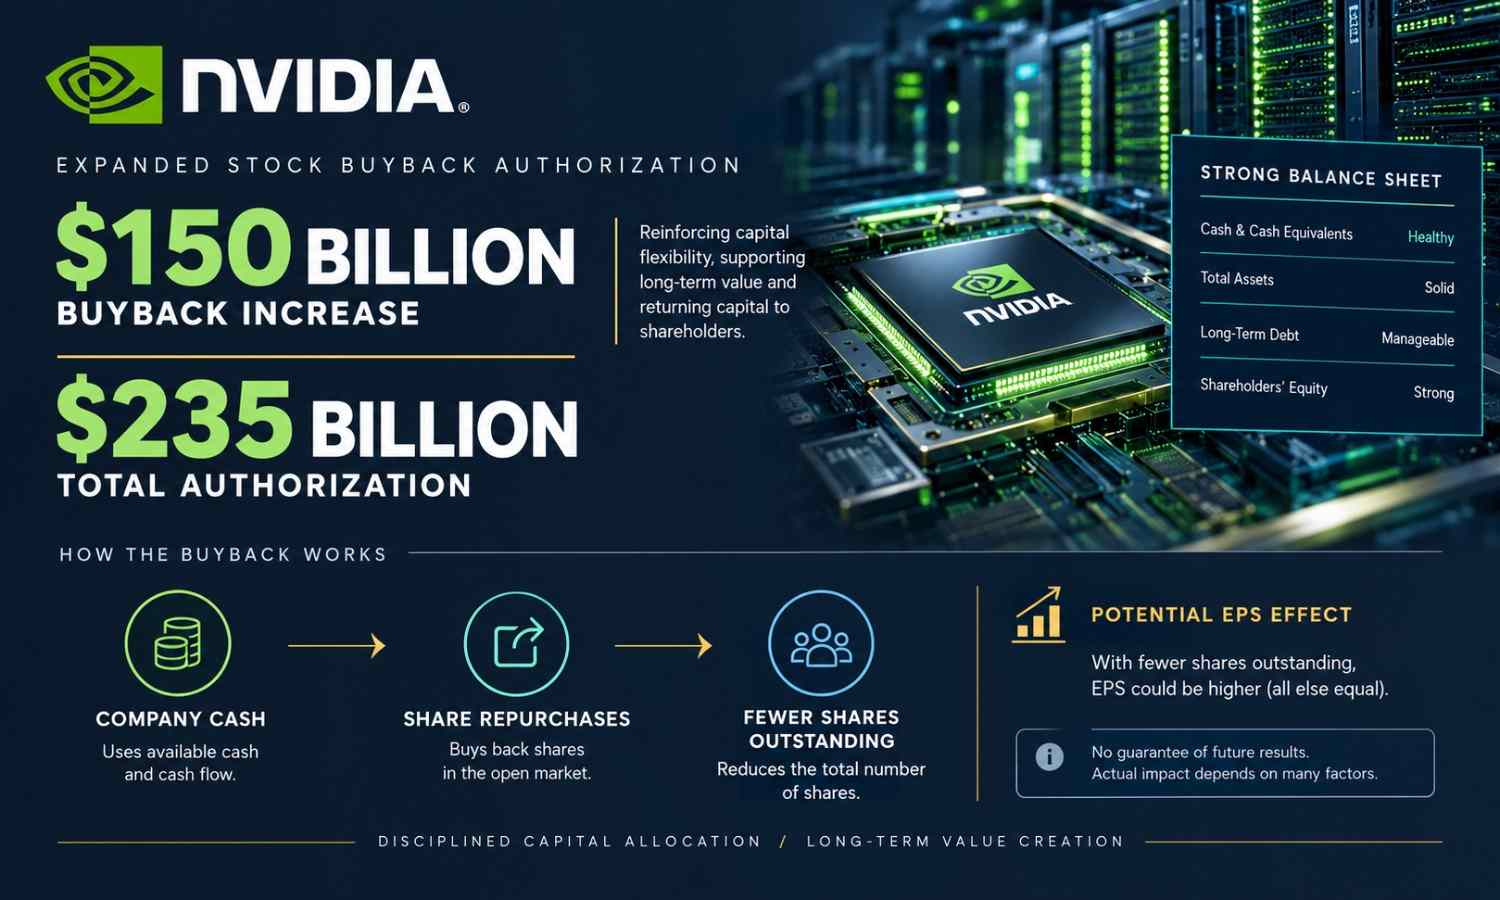
Nvidia has just sent one of the strongest signals yet that it believes the artificial-intelligence boom still has a long runway. On September 28, 2026, the chipmaker announced a $150 billion increase to its share repurchase authorization, taking its total available authorization to $235 billion.

The announcement arrived at an uncomfortable moment for the broader AI investment story.

U.S. Treasury yields have been climbing sharply, with the 10-year yield moving above 5.2% and later reaching approximately 5.27%, while oil prices have added to inflation concerns. At the same time, major technology companies are borrowing heavily to finance data centers, computing infrastructure and other AI-related capital expenditures.

That creates an important distinction for investors.

Nvidia is not borrowing $150 billion to fund its stock buyback. Instead, the company’s enormous cash-generation capacity allows it to return capital to shareholders while continuing to invest in its business. The bigger question is whether the companies building the infrastructure required to support the AI boom can continue financing that expansion at increasingly higher interest rates.

This is the emerging AI debt dilemma: can the revenue and productivity created by artificial intelligence grow quickly enough to justify a dramatically higher cost of capital?

The answer matters not only for Nvidia but also for semiconductor stocks, cloud companies, corporate bonds and portfolios exposed to the broader AI trade.

Key Takeaways

  • Nvidia increased its share repurchase authorization by $150 billion, taking total authorization to $235 billion.
  • The move signals management’s confidence, but a buyback does not eliminate valuation, competitive, or industry risks.
  • The U.S. 10-year Treasury yield has moved above 5.2%, increasing the opportunity cost of owning riskier assets and raising corporate financing costs.
  • AI-related companies are increasingly relying on debt to finance data-center expansion, making interest rates and credit spreads increasingly important.
  • The critical investment question is shifting from simply โ€œHow fast is AI growing?โ€ to โ€œWhat return will companies generate on the enormous capital being deployed?โ€

Nvidia’s $150 Billion Buyback Is a Major Signal

What Nvidia’s Buyback Really Signals to Wall Street

Nvidia’s latest capital-return decision is extraordinary by historical standards.

The company announced an additional $150 billion share repurchase authorization, lifting its total authorization to $235 billion. Reuters reported that the new authorization exceeds Apple’s previous $110 billion record announced in 2024. Nvidia intends to use the expanded authorization through fiscal 2028, subject to market conditions and other considerations.

The significance goes beyond the headline number.

A stock buyback allows a company to use cash to purchase its own shares. When shares are retired, the number of shares outstanding falls. If earnings remain constant, earnings per share can increase because those earnings are distributed across fewer shares.

But investors should avoid treating buybacks as automatic evidence that a stock is undervalued.

The more meaningful signal from Nvidia is its confidence in its cash-generation capacity.

Nvidia’s fiscal 2026 results already showed substantial shareholder returns. The company repurchased approximately $40.4 billion of stock during that fiscal year. Its subsequent quarterly filing showed another $39.8 billion of repurchases during the first half of fiscal 2027.

The September authorization therefore represents a substantial escalation in the amount of capital potentially available for future repurchases.

Management has also continued to emphasize that AI and accelerated computing represent a major long-term platform shift.

That creates two possible interpretations for investors.

The bullish interpretation is straightforward: Nvidia believes demand for AI computing will remain strong enough to generate substantial free cash flow, even while the company continues investing heavily in future technologies.

The more cautious interpretation is that the market should focus on cash flow per share, earnings growth, and valuation, rather than the headline size of the authorization.

A company can repurchase billions of dollars of stock and still deliver disappointing shareholder returns if its future earnings growth slows dramatically or the shares are purchased at an excessive valuation.
Nvidia $150 billion stock buyback authorization

In other words, a stock buyback can amplify shareholder value when the underlying business is performing well, but it cannot replace fundamental business growth.

Why 5.2% Treasury Yields Change the AI Investment Equation

The other side of this story is the bond market.

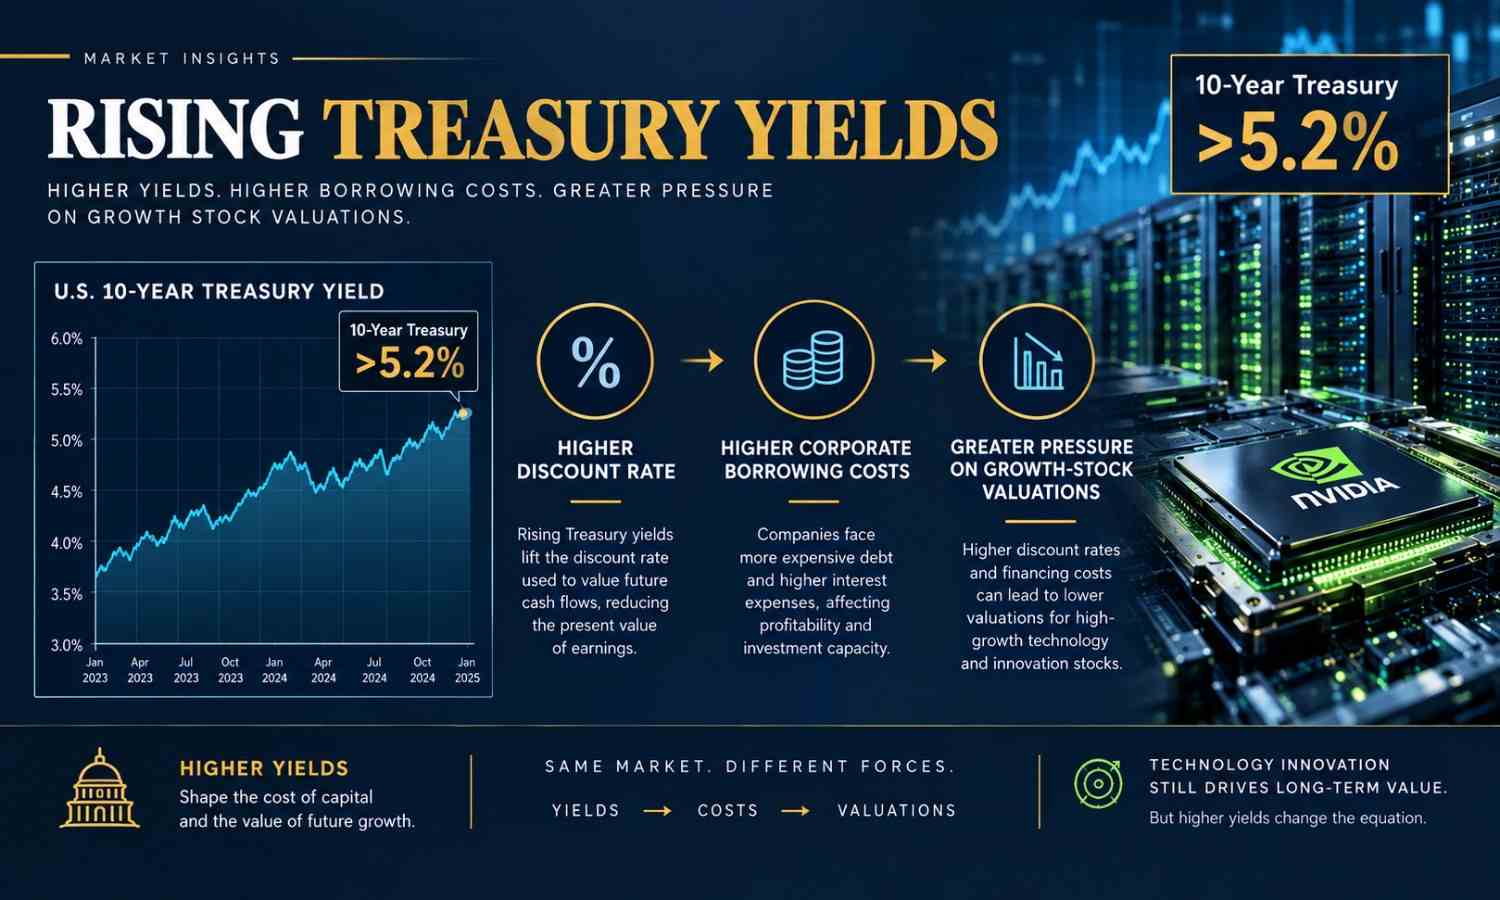
The U.S. 10-year Treasury yield has moved above 5.2%, reaching roughly 5.27% in the latest market reporting. Reuters described the move as part of a broader bond-market selloff, with long-term yields reaching multi-year highs.

The combination matters because Treasury yields influence the cost of money throughout the financial system.
U.S. Treasury yields and AI stock valuations

When government bond yields rise, investors can demand higher returns from corporate bonds and other risk assets. Companies issuing new debt may therefore need to pay higher coupons or offer investors greater compensation for taking credit risk.

That is particularly important for businesses undertaking enormous capital projects.

AI data centers require land, electricity, cooling systems, networking equipment, GPUs, CPUs, memory and other infrastructure. The spending can be enormous, and companies do not necessarily fund all of it from current operating cash flow.

Some of the financing therefore comes from debt.

And this is where the AI debt dilemma becomes more important.

The Feedback Loop: How AI Debt Can Pressure the Market

Consider a simplified chain:

More AI investment โ†’ more corporate borrowing โ†’ greater bond supply โ†’ higher required financing costs โ†’ higher capital expenditure โ†’ greater pressure to generate returns.

This does not mean every new AI bond is dangerous.

Large technology companies can have significant cash flows, valuable intellectual property and strong balance sheets. Reuters reported, for example, that AI-related corporate bond issuance has become large enough for investors to become more selective, with major issuers including Alphabet and Meta facing greater scrutiny over the scale and predictability of their borrowing needs.

Reuters has estimated that AI-related bond issuance could reach approximately $420 billion in 2027.

That is a critical development for investors.

The AI investment story is increasingly becoming a capital-allocation story.

The question is no longer only whether companies can sell more AI services. Investors must also ask how much capital those companies must deploy to produce each additional dollar of revenue and how much that capital costs.

Rising oil prices complicate the equation further because higher energy costs can reinforce inflation pressures and make it harder for central banks to reduce interest rates quickly.

For technology stocks whose valuations depend heavily on future earnings, that combination can matter enormously.

The AI Debt Dilemma: Can Growth Outrun the Cost of Capital?

This is where the Nvidia story becomes more interesting than a simple buyback headline.

Nvidia itself is not the obvious example of an AI company being squeezed by debt financing.

The bigger concern is the ecosystem around Nvidia.

Hyperscalers and other infrastructure providers are spending enormous amounts to construct the computing capacity needed for AI. Reuters reported that hyperscalers had issued approximately $220 billion of bonds during the year, while concerns over financing costs and credit spreads were beginning to appear in the corporate debt market.

Oracle and Meta are among the companies attracting attention because of their capital requirements and financing activity.

The fundamental issue is return on invested capital.
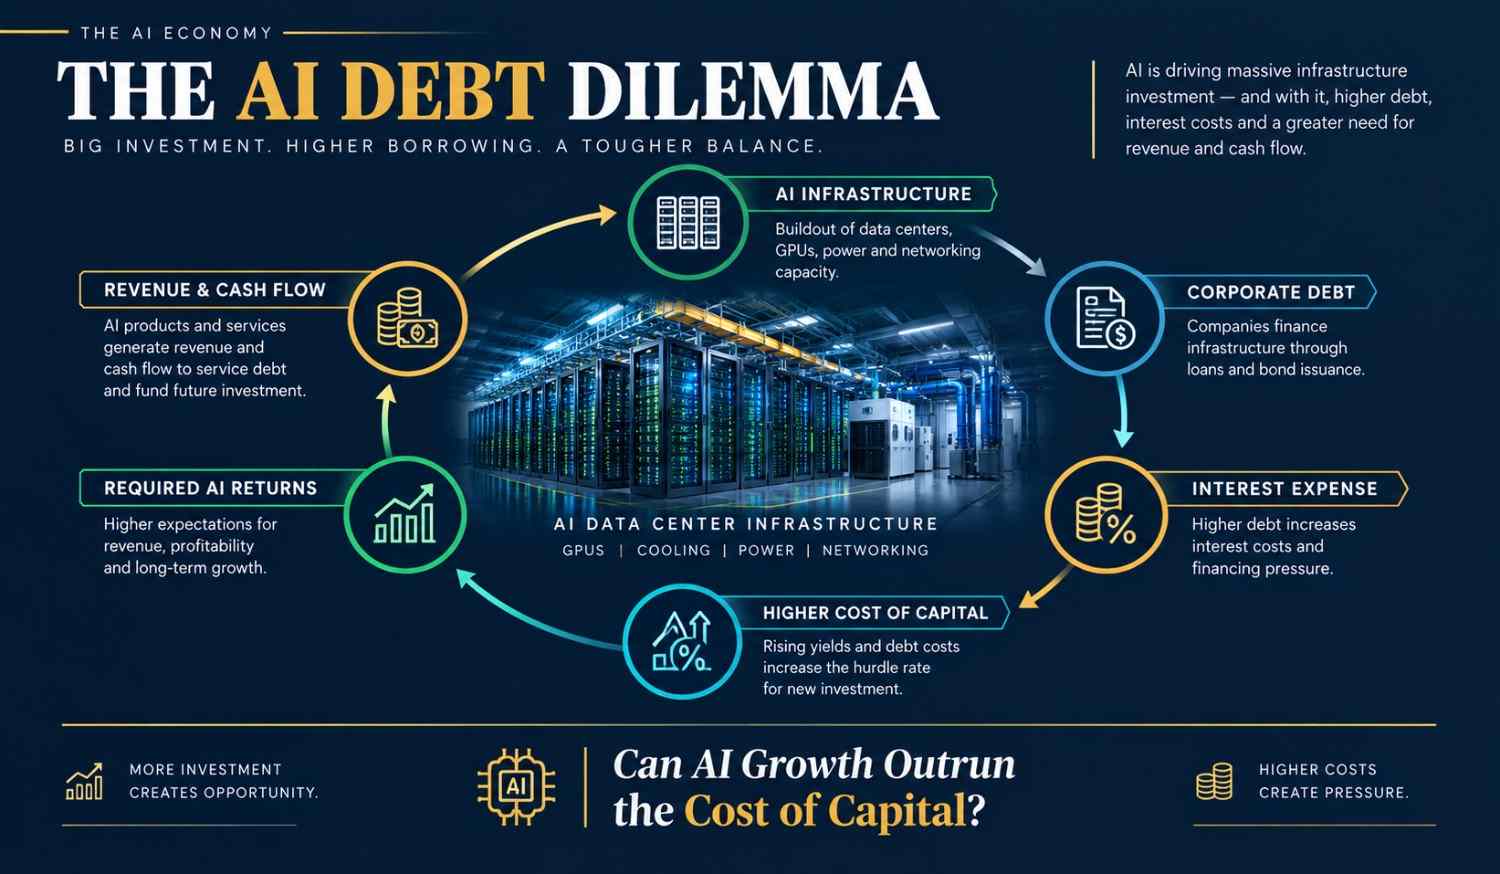
AI debt dilemma and data center financing

Suppose a company spends $100 billion building AI infrastructure. Investors ultimately need to know whether that infrastructure can produce returns sufficiently above the company’s cost of capital.

If interest rates rise, the hurdle becomes higher.

If revenue grows rapidly enough, the investment can still work.

However, if revenue growth disappoints while borrowing costs rise, the economics become less attractive.

This is why investors should distinguish between AI demand and AI investment returns.

The first can be extremely strong while the second remains uncertain.

Intel and AMD Show That AI Demand Is Still Real

The semiconductor market provides another important piece of the puzzle.

Intel CEO Lip-Bu Tan recently said the company could supply only about half of what customers were requesting, highlighting how strong processor demand has become.

That shortage is particularly interesting because AI infrastructure requires more than GPUs.

Modern AI systems also depend on CPUs, memory, networking, and other components. The expansion of agentic AI and inference workloads is increasing the importance of general-purpose computing.

AMD is benefiting from this broader demand.

Mercury Research data cited in recent reporting showed AMD’s server CPU unit share reaching 34.5% in the second quarter of 2026, compared with 27.3% a year earlier.

AMD has also projected that its server CPU total addressable market could grow at more than 50% annually through 2030 and reach approximately $220 billion.

Its data center revenue increased 107% year over year in the second quarter, according to reporting surrounding the Intel development.

These numbers illustrate an important point:

The AI infrastructure boom is not imaginary.
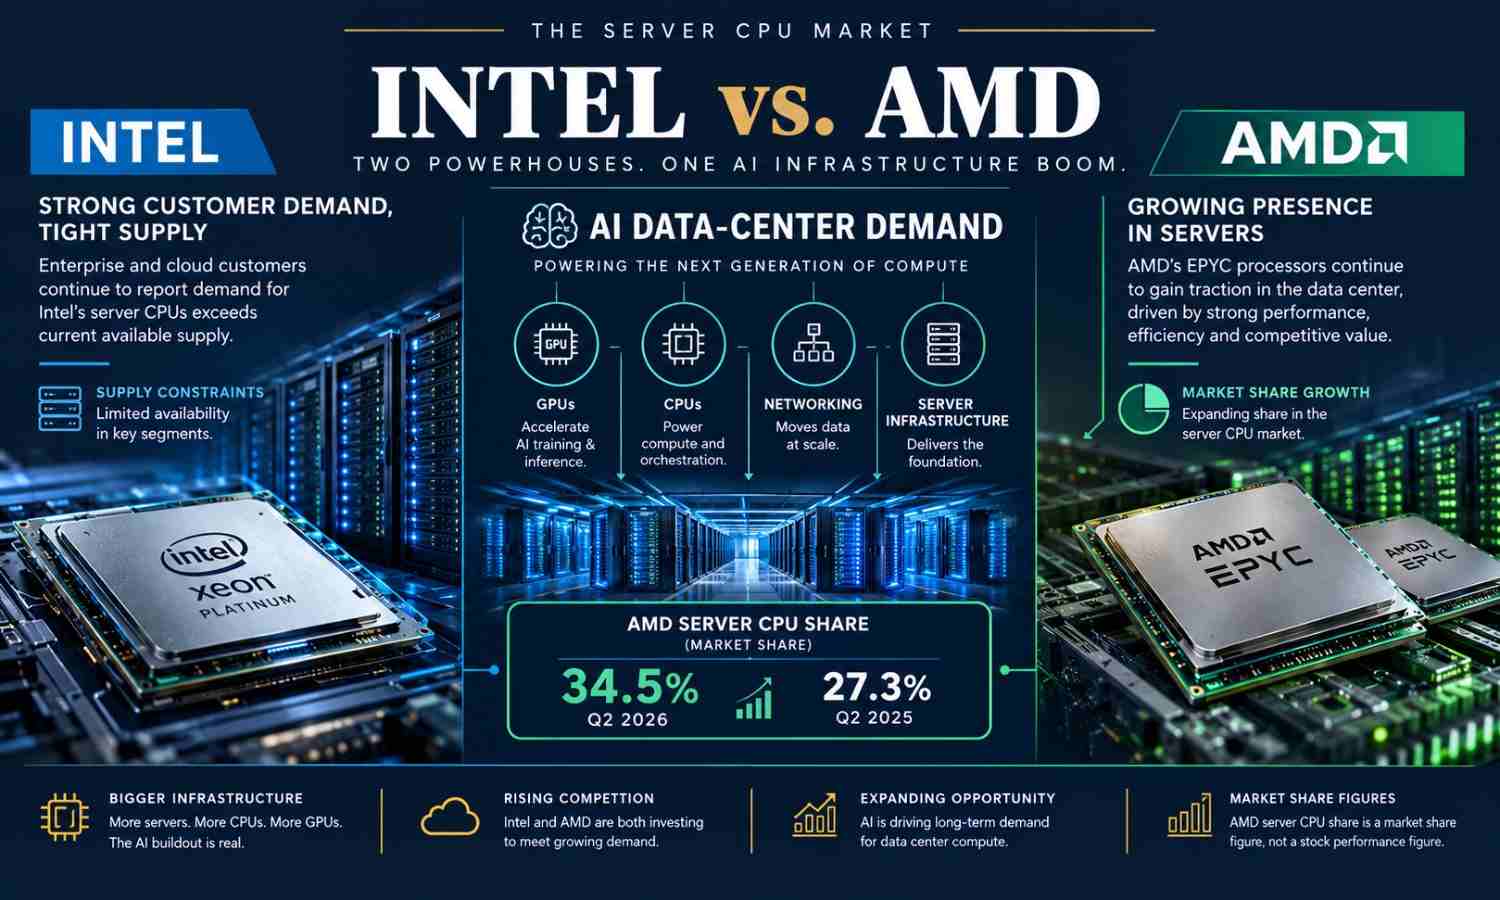
AMD and Intel server CPU demand in AI infrastructure

There is real demand for processors and data-center capacity.

But genuine demand does not automatically mean every infrastructure investment will generate attractive returns.

That distinction could become one of the defining investment themes of the next phase of the AI cycle.

What Nvidia’s Buyback Means for Different Investors

Growth Investors: Watch Earnings, Not Just Buybacks

For growth investors, Nvidia’s buyback may reinforce confidence in management’s long-term expectations.

However, the most important metrics remain:

  • Data-center revenue growth
  • Gross and operating margins
  • Free cash flow
  • AI accelerator demand
  • Customer concentration
  • Competitive developments
  • Capital expenditure across major AI customers
  • Forward earnings expectations

A large buyback should be treated as additional information, not as a substitute for fundamental analysis.

Investors following AI stocks should also monitor whether hyperscalers continue increasing capital expenditure and whether that spending translates into profitable AI services.

Income Investors: Rising Yields Change the Competition

For income-oriented investors, higher Treasury yields create a different opportunity set.

When government bonds offer materially higher yields, investors have an alternative to dividend-paying equities and lower-rated corporate debt.

That can influence valuations.

A technology company with a relatively low dividend yield may need stronger earnings growth to justify its valuation when investors can earn substantially more from high-quality government bonds.

This is one reason bond yields matter to stock-market valuation even when the company itself has little debt.

Conservative Investors: Diversification Matters More

For conservative portfolios, the current environment highlights the importance of diversification.

A portfolio concentrated entirely in high-growth technology stocks can become particularly sensitive to changes in interest rates and valuation multiples.

Investors may therefore consider how stocks, Treasury securities, corporate bonds, cash equivalents, and other assets interact within their broader portfolio management strategy.

The objective is not necessarily to abandon AI.

It is to understand the different risks attached to each part of the market.

How to Position a Portfolio in a High-Rate, AI-Driven Market

Rather than asking whether Nvidia is automatically a buy or sell because of the announcement, investors can monitor several measurable signals.

1. Follow the 10-Year Treasury Yield

A sustained move higher would generally increase the discount rate applied to future corporate earnings.

A meaningful decline could have the opposite effect.

2. Track Corporate Bond Spreads

Treasury yields show the risk-free benchmark.

Credit spreads show how much additional compensation investors demand for lending to corporations.

If AI-related spreads continue widening, that could indicate growing concern about the amount of capital being deployed.

3. Watch AI Capital Expenditure

The next question is not simply whether companies are spending more.

Investors should examine whether companies are generating enough revenue and operating cash flow to justify that spending.

4. Monitor Nvidia’s Free Cash Flow

The buyback is supported by Nvidia’s ability to generate cash.

That makes free cash flow particularly important.

If cash generation continues to grow alongside AI demand, the capital-return argument becomes stronger. If cash flow growth slows sharply, investors may reassess the pace and sustainability of repurchases.

5. Watch Semiconductor Competition

Nvidia is not operating in isolation.

AMD, Intel, and other semiconductor companies are competing for different portions of the AI computing market.

The server CPU shortage reported by Intel is evidence of strong underlying infrastructure demand, while AMD’s market-share gains demonstrate that the competitive landscape continues to evolve.

What Investors Should Watch Next

The AI investment narrative could change quickly as new economic and corporate data arrive.
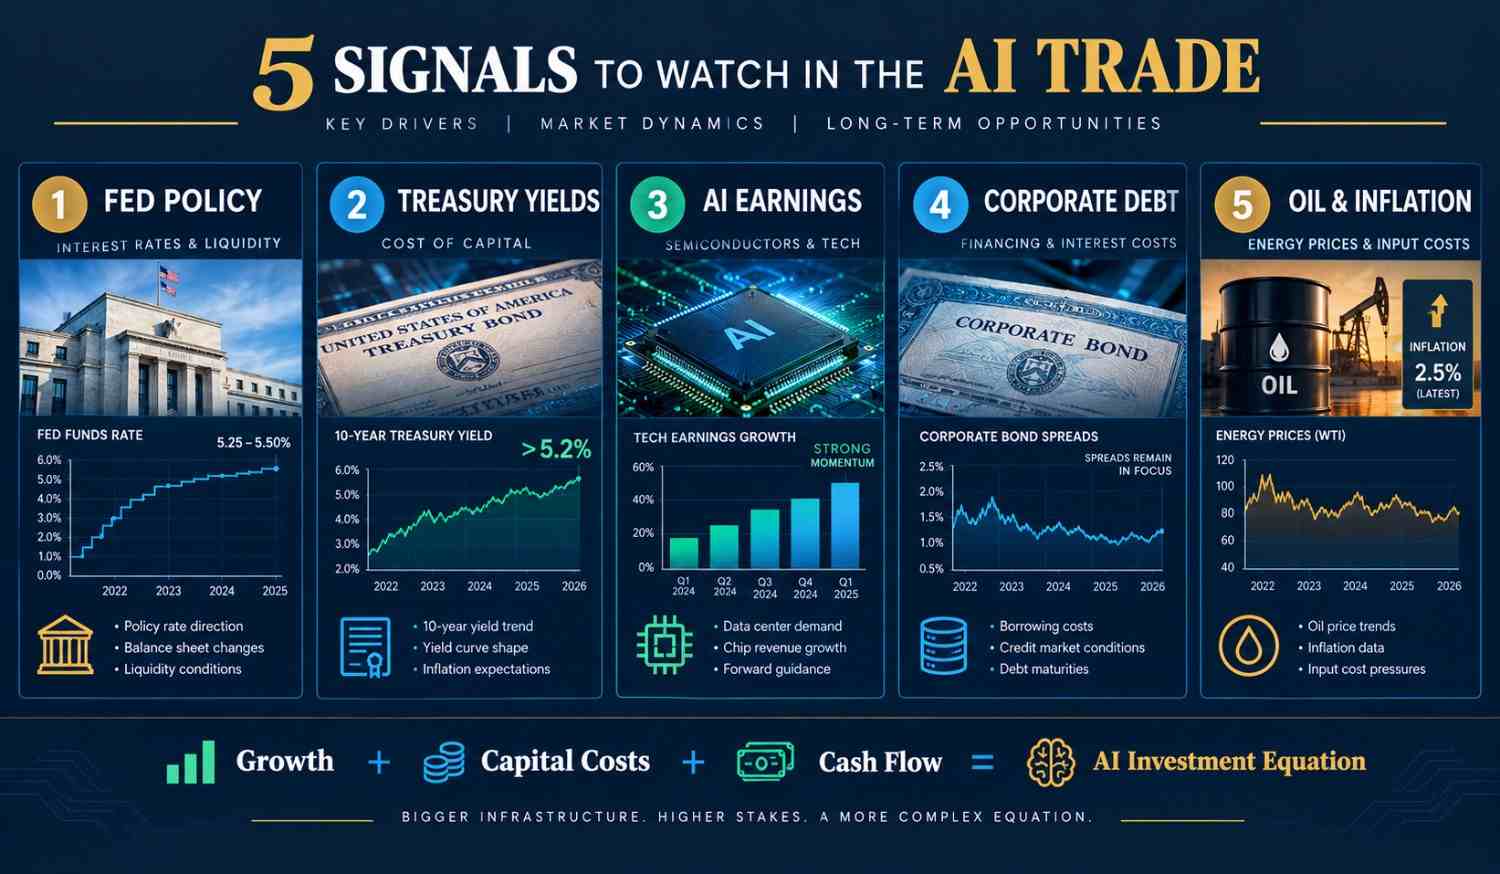
AI investment market outlook and investor dashboard

Federal Reserve policy

The September rate increase puts additional focus on future inflation and employment data.

If inflation remains elevated, investors may need to price in higher rates for longer.

If inflation falls substantially, pressure on long-term yields could ease.

Treasury yields

The 10-year Treasury is now one of the most important variables for technology-stock valuations.

Investors should watch whether yields stabilize, continue rising, or reverse lower.

Nvidia, AMD and Intel earnings

Quarterly results will provide direct evidence about whether AI demand is translating into revenue and profit.

For Nvidia, investors should pay particular attention to data-center growth, margins and free cash flow.

For AMD and Intel, server CPU demand and supply constraints will remain important.

Corporate debt issuance

Investors should monitor how much additional debt major technology companies issue and at what cost.

A rising volume of issuance is not automatically negative. The key question is whether the returns generated by the underlying AI infrastructure justify the financing cost.

Oil and inflation

Higher energy prices can complicate the Federal Reserve’s inflation fight.

That makes oil another variable investors should monitor alongside Treasury yields and corporate credit spreads.

The Bottom Line: Nvidia’s Buyback Is a Confidence Signal, Not a Shield

Nvidia’s $150 billion buyback expansion is one of the most significant corporate capital-return announcements of 2026. It demonstrates that management believes the company can continue generating enough cash to invest in AI while returning substantial capital to shareholders.

But investors should not confuse that confidence with immunity from macroeconomic risk.

The more important story is happening across the broader AI financing ecosystem.

Nvidia can have exceptional cash generation while other companies building AI infrastructure face increasingly expensive financing.

That is the heart of the AI debt dilemma.

The AI boom may continue to produce enormous demand for GPUs, CPUs, networking equipment, and data centers. Intel’s supply constraints and AMD’s rising server CPU share provide evidence that the infrastructure cycle remains powerful.

At the same time, a 5%+ Treasury environment changes the mathematics of investment.

The hurdle for capital-intensive projects becomes higher. Corporate borrowers may have to pay more to finance expansion. Investors have more attractive alternatives in fixed income. And technology valuations become more sensitive to the discount rate applied to future earnings.

For investors, the most useful question is therefore not simply โ€œIs AI still growing?โ€

It is:

โ€œAre AI companies generating returns that justify the capital being committed to the AI buildout?โ€

That question will increasingly connect Nvidia’s buyback, Treasury yields, corporate debt, semiconductor competition, and the future direction of the stock market.

For more evidence-based analysis of investing, technology, and financial markets, subscribe to FinWireStack and follow the next developments in the AI investment cycle.

Key Takeaways

  1. Nvidia’s $150 billion buyback expansion takes its total authorization to $235 billion and represents a major capital-return commitment.
  2. Nvidia is not borrowing $150 billion to fund the buyback. The debt concern is primarily about the wider AI infrastructure financing cycle.
  3. Treasury yields above 5.2% raise the opportunity cost of equities and increase financing costs across the corporate market.
  4. AI demand remains strong, with Intel reporting severe server CPU supply constraints and AMD continuing to gain server CPU market share.
  5. The next phase of the AI investment story will increasingly depend on return on invested capital, free cash flow, debt costs, and sustainable revenue growth rather than AI spending alone.

FinWireStack provides educational and informational market commentary and does not provide individualized investment advice. Market conditions can change rapidly. Investors should consider their objectives, time horizon, and risk tolerance and conduct independent research before making investment decisions.
The Future of Housing in California: Trends, Predictions, and What They Mean for Your Wallet

Future of housing in California - person looking at city skyline with data overlay

Expert Analysis | July 24, 2026 | *Reading Time: 22 min


The future of housing in California is at a critical crossroads. With median home prices exceeding $800,000, a homeownership rate of just 55% (compared to 65% nationally), and only 17% of households able to afford a median-priced home, the state’s housing crisis has reached a tipping point.

This comprehensive guide examines the future of housing in California through a personal finance lens. We analyze the unprecedented $11.25 billion housing bond heading to voters, the growing impact of construction technology (Contech) on housing supply, shifting demographics reshaping demand, and what these trends mean for your wallet. Understanding the future of housing in California is essential for anyone looking to build wealth, secure their financial future, and make informed decisions in today’s economy. Whether you are a renter, prospective homebuyer, or investor, the future of housing in California will directly impact your financial trajectory.


The Current State of California Housing: A Crisis in Numbers.

To understand the future of housing in California, we must first understand where we stand today. The numbers paint a stark picture of a state in the grip of a severe housing crisis.

The Supply Gap

California faces a chronic housing shortage. Current estimates suggest the state needs to build 300,000 to 500,000 homes annually to meet demand and stabilize prices, yet it is producing closer to 100,000 homes per year. Even as California built approximately 100,000 new units last year, the state simultaneously lost 16,000 homes in the January 2025 wildfires, illustrating how fragile progress can be.

California is approximately 1.2 million units short of the affordable housing needed to meet demand. This supply gap has been decades in the making, with underbuilding following the Great Recession setting the stage for today’s shortages.

The Affordability Crisis

A massive affordability gap defines the future of housing in California:

MetricCalifornia ValueNational Value
Median Home Price$812,000-$823,000$420,000
Homeownership Rate55%65%
Households Affording Median Home17%~45%
Housing Cost as % of Income50%+~30%

While U.S. households spend roughly 30% of their income on housing, Californians spend more than 50% on average. This means the future of housing in California will continue to strain household budgets unless significant changes occur.

The Rent Burden

More than half of California renters are “rent burdened,” spending more than 30% of their income on housing. Two-thirds of lower-income renters are rent-burdened, and approximately 170,000 people are unsheltered.

The Homeownership Gap

California has the second-lowest homeownership rate in the nation. The average age of a first-time homebuyer is approaching 40. Young adults aged 25-34 make up only 11% of homeowners in the Los Angeles metro area, the lowest percentage for that demographic in the U.S. In Los Angeles County specifically, it’s just 9.8%.

help. “Help.” Edward Coulson, an economics professor at UC Irvine, attributes these low numbers to “the region’s expensive home prices and down payment challenges. It takes a lot to be able to put together a down payment, and that’s increasingly difficult for young people who don’t have a third party able to help.”


The $11.25 Billion Housing Bond: What Voters Need to Know.

A historic ballot measure will significantly shape the future of housing in California. In June 2026, Governor Newsom, the Assembly, and the Senate agreed to place the Veterans and Affordable Housing Bond Act of 2026 on the November ballot.

California housing bond 2026 - $11.25 billion investment visualization

What the Bond Includes

The $11.25 billion bond includes:

ComponentAmountPurpose
CalVet Home Loan Program$1.25 billionSelf-supporting revenue bonds to help veterans and military families achieve homeownership
General Obligation Bonds$10 billionConstruction, rehabilitation, acquisition, and preservation of affordable housing

What the Bond Will Achieve

If approved by voters, the bond is expected to:

  • Help more than 40,000 Californians purchase a home through down payment assistance, affordable mortgage financing, and other homeownership support 
  • Support the creation or preservation of tens of thousands of affordable homes for lower-income Californians, including seniors, farmworkers, veterans, and people experiencing or at risk of homelessness 
  • Support tens of thousands of high-paying construction jobs 

The Leverage Factor

For every $1 invested by the state, an estimated $4 in federal tax credits, local funding, private financing, and resident rents will help finance these developments. This leverage means California can build substantially more housing than state dollars alone could support.

Why This Bond Matters for the Future of Housing in California

Senator Dave Cortese (D-San Jose) emphasized the urgency: “The housing crisis is driving working families out of our communities, pushing more Californians into homelessness, and threatening our state’s economic competitiveness. We know what needs to be done. Today, there are approximatelyย 40,000 affordable housing units across California that are shovel-ready but stalledย because financing has dried up and construction costs have soared. What’s missing is the capital needed to get shovels in the ground.”

heads. “heads.” Assemblymember Buffy Wicks (D-Oakland) added, “We all know the stats in Californiaโ€”two-thirds of lower-income renters are rent-burdened, 170,000 people are unsheltered, and we are 1.2 million units short of the affordable housing we need. But what gets lost when we’re counting housing units and debating dollars and cents is that we’re really talking about families who need a roof over their heads.”

The Refinancing Challenge

The future of housing in California also faces a significant refinancing hurdle. Approximately $860 million in commercial mortgages on fully affordable properties will mature in 2026, rising to $6.9 billion by 2030 and $13.3 billion over the next decade. These maturities are concentrated in major markets: Los Angeles ($390.3 million), the Bay Area ($223.1 million), Orange County ($64.1 million), and the San Fernando Valley ($76 million).

Despite these looming maturities, the sector is not facing widespread distress. Affordable housing benefits from government-backed financing, subsidized revenue streams, and longer loan terms, which have historically limited defaults.


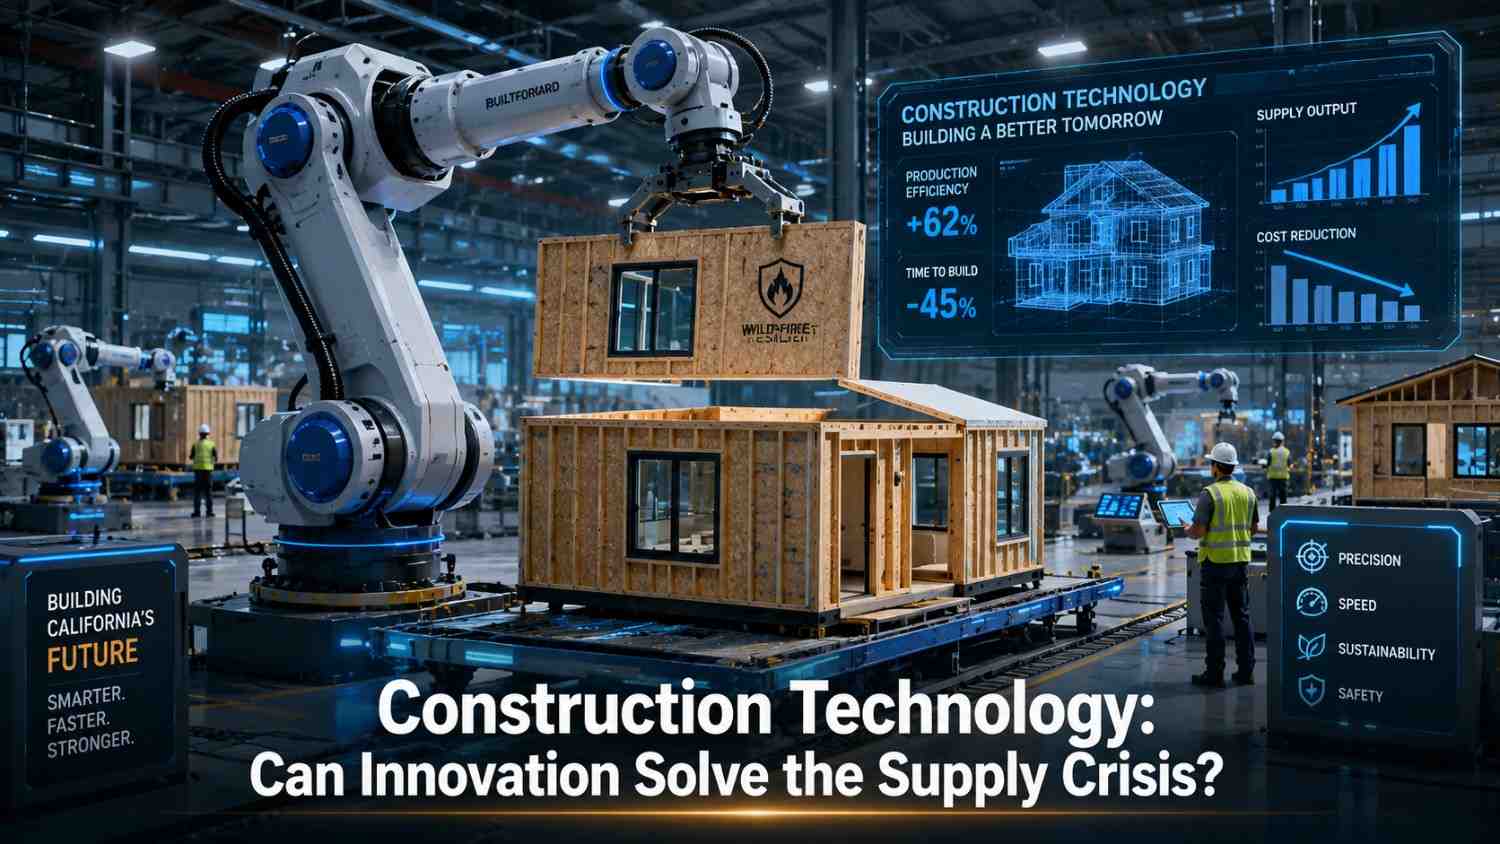
Construction Technology: Can Innovation Solve the Supply Crisis?

One of the most promising developments in the future of housing in California is the rise of construction technology (Contech). The US housing crisis has become structural: the country is short of more than five million dwellings, while the price of new homes has climbed by nearly a third in five years.

The Labor Shortage

About 40% of the construction workforce is expected to retire within the decade, leaving an industry trying to build more with fewer hands and under the growing stress of wildfires, floods, and rising temperatures. This labor shortage is a critical constraint on the future of housing in California.

The Contech Revolution

A new generation of firms is using robotics, data, and design automation to rethink how we make buildings. Key innovations include the following:

TechnologyApplicationImpact
AI-Optimized Micro-FactoriesCompact, robotic workshops producing energy-efficient homesCan be deployed in under 100 days
AI-Powered Work InstructionsEnabling apprentices to perform complex tasks with precisionAugments labor, doesn’t displace it
Digital Construction ManagementReal-time tracking of construction progressImproves coordination and reduces delays
	Construction technology Contech shaping the future of housing in California

Real-World Examples

Reframe Systems, a venture founded by former Amazon roboticists, is deploying AI-optimized micro-factories. Its first micro-factory is in Massachusetts, with the second set to open in Los Angeles to support post-wildfire rebuilding. “We want to act as co-developers,” says its CEO, Vikas Enti. “We’re working with communities to make resilience accessible, not aspirational.”

Versatile, a California-based firm, uses data about building sites to improve processes. Model Z in Los Angeles provides prefab infill homes.

The Wildfire-Resilience Factor

In California, the future of housing must also account for wildfire risk. Innovative construction methods are emerging that offer:

  • Fire Code Compliance: 90-120-minute fire ratings (vs. 30 minutes for traditional ones) 
  • Lower Build Costs: Up to 20-30% lower than traditional construction 
  • Improved Insurability: Engineered to wildfire-certified standards 
  • Lower Operating Costs: 100% lower electricity costs and 15% lower insurance 

The Permitting Bottleneck

Despite technological advances, permitting bottlenecks remain a significant obstacle. In post-wildfire reconstruction around Los Angeles, approval timelines of 10 to 18 months remain common despite policy efforts to accelerate rebuilding. These delays are contributing to the pronounced housing shortage.

A Word of Caution

While Contech offers promise, the sector has seen failures. Katerra, the Silicon Valley darling that tried to reinvent everything, raised $2 billion but collapsed in 2021. Today’s innovators are learning to “play smaller and smarter, treating the housing shortage not as a mass-production problem but as one of mass customization.”


Political Shifts: How the 2026 Election Could Reshape Housing Policy.

The future of housing in California will be significantly influenced by the 2026 gubernatorial election and ongoing legislative action.

The Gubernatorial Forum

At the “Homeownership Matters: Gubernatorial Forum” in Sacramento, six candidates discussed their ideas for housing policy. One theme dominated: California must address its housing shortage. Across party lines, candidates acknowledged that the state is simply not building enough homes to meet demand.

Areas of Agreement

There was broad consensus around several key ideas:

  1. Increase housing supply
  2. Streamline permitting and approvals
  3. Support first-time homebuyers
  4. Improve housing affordability
  5. Address the growing insurance challenge 

The Insurance Crisis

One issue receiving significant attention is the California homeowners insurance crisis. Rising wildfire risk, insurers leaving the market, and higher construction costs have created new challenges. Insurance availability is critical because lenders require homeowners insurance to close a mortgage.

Potential policy solutions discussed included:

  • Increasing wildfire prevention investments
  • Reforming insurance regulations
  • Expanding catastrophe reinsurance programs
  • Incentivizing fire-resistant construction 

Legislative Momentum

The Assembly has made housing a central pillar of its affordability agenda. Recent reforms include:

ReformImpact on Future of Housing in California
CEQA Exemptions (Jan 2026)Sweeping legislation to fast-track housing construction by reducing regulatory barriers
$500M for LIHTCLow-Income Housing Tax Credits to expand affordable housing development
$1.5B for HHAPHomeless Housing, Assistance, and Prevention program
30-Day Review WindowsEmpowering homeowners to use licensed third-party professionals when local agencies exceed review windows
Moratorium on Cost-Increasing Standards (2025-2031)Preventing new residential building standards from increasing construction costs

New Legislation on the Horizon

Just last month, Assembly Democrats advanced more housing legislation:

BillPurpose
AB 1751Makes building townhomes easier and faster
AB 1815Speeds up housing production by providing more clarity for builders
AB 1406Updates deposit rules for new housing developments
AB 1786Expands best-value contracting options for local governments
AB 1899Prevents youth homelessness
AB 1903Lowers housing costs by allowing builders to fix problems before litigation
AB 1924Creates a statewide strategy to prevent homelessness
AB 1934Creates a voluntary home-hardening certification plan for fire safety
AB 2074Speeds up housing construction near major transit hubs
AB 2176Addresses student housing needs
AB 2518Connects affordable housing to power faster

Coastal Zone Reforms

The California Coastal Commission, historically a significant hurdle to coastal housing production, is shifting. Its newly adopted 2026-2030 Strategic Plan elevates housing affordability and supply as strategic priorities. Key changes include:

  • Five-Year Vesting for Affordable Projects: Standard vesting period extended from two to five years for 100% affordable housing permits 
  • Streamlined ADU Process: Guidance to simplify permitting for Accessory Dwelling Units in the Coastal Zone 
  • SB 963: Proposed hard statutory timelines for coastal permit appeals to avoid “appeal purgatory” 

Demographic Trends: Who Will Own Homes in 2030?

The future of housing in California is being shaped by profound demographic shifts.

The Millennial and Gen Z Challenge

California’s young adults are being locked out of homeownership at unprecedented rates. The future of housing in California will be defined by whether these generations can access the housing market.

California homeownership demographics: young adults and future trends
Metro AreaYoung Adult (25-34) Homeownership Rate
Los Angeles-OC11% (National Low)
San Francisco14%
San Jose14%
San Diego15%
Riverside19%
Sacramento23%

Source: ApartmentList study based on Census Bureau data 

The “K-Shaped” Economy

The housing market reflects a “K-shaped” economy, where higher-income households have benefited from tailwinds such as asset growth and AI-driven sectors, while lower-income households face persistent headwinds. However, even higher-income consumer sentiment has begun to contract in early 2026, influenced by rising health costs and labor uncertainty.

The Homeownership Rate Projection

California’s homeownership rate currently stands at 55%, compared to the national average of 65%. With the future of housing in California shaped by current affordability constraints, experts suggest this gap may persist or even widen unless significant policy changes occur.


The Affordability Gap: What $1 Million Homes Mean for Your Finances.

Experts predict that by 2030, California’s average home value will exceed $1 million. This projection has significant implications for your personal finances and understanding the future of housing in California.

The $1 Million Reality

California will lead the list of U.S. states’ highest average home values by 2030, driven by the state’s attractive climate, robust job market, and constrained supply.

The Down Payment Challenge

Even with a 10% down payment on a $1 million home, you would need $100,000 in cash. This is a significant barrier for most households and a key factor in the future of housing in California.

Monthly Payment Projections

Using a 6.5% mortgage rate, the monthly payment on an $800,000 home with a 20% down payment is approximately $4,000 before taxes and insurance. On a $1 million home, that rises to $5,000+.

Proposition 13 and the Wealth Gap

California’s property tax system creates a unique situation through Proposition 13. This 1978 law caps property taxes at 1% of assessed value and limits annual increases to just 2%, creating massive disparities between long-term owners and new buyers. A neighbor who bought in 1990 might pay $3,000 annually while you pay $9,000 on an identical house.

This disparity is a critical factor in the future of housing in California. Long-term homeowners benefit significantly, while new buyers face a much higher tax burden.

The Opportunity Cost of Waiting

In competitive California markets, waiting to buy often carries its own cost. If a home priced at $800,000 appreciates just 4% in one year, that equals $32,000 in added cost. Rent payments during the waiting period add another layer; paying $3,000 per month for two years equals $72,000 that does not build equity.


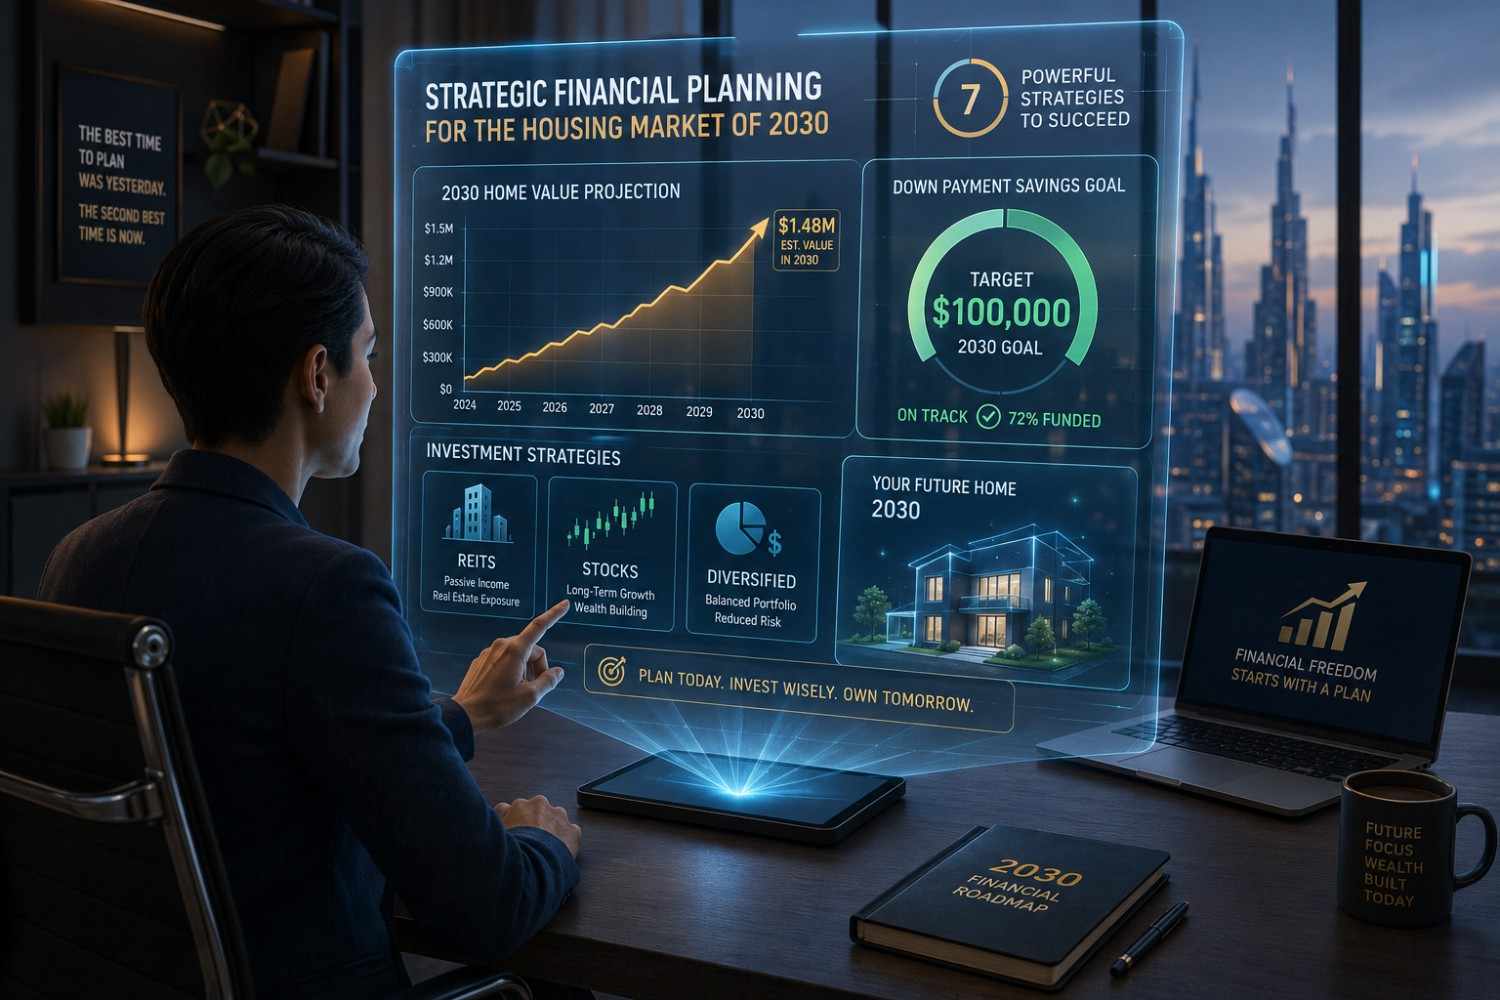
Strategic Financial Planning for the Housing Market of 2030.

Given the future of housing in California, here are 7 strategies to prepare your finances for the coming decade.

Strategic financial planning for the future of housing in California

Strategy 1: Start Saving Early

The down payment is the biggest hurdle. Start saving as early as possible; even small amounts add up over time. Consider automatic transfers to a dedicated savings account.

Strategy 2: Explore Down Payment Assistance

With the $11.25 billion housing bond, programs like California Dream For All (shared appreciation loans for down payments) are expected to expand. Explore existing programs as well.

Strategy 3: Understand Your Time Horizon

If you plan to stay in the same area for at least 5-7 years, buying often makes financial sense. Your time horizon is a critical factor in the future of housing in California.

Strategy 4: Consider Co-Owning a Home

Partnering with family or friends can make homeownership more accessible. This can be structured through a tenancy-in-common or a formal co-ownership agreement.

Strategy 5: Invest in Real Estate Investment Trusts (REITs)

If you want real estate exposure without buying a home, consider investing in REITs. These offer diversification and liquidity that direct property ownership cannot provide.

Strategy 6: Stay Informed on Housing Policy

Policy changes (like the housing bond, zoning reform, and funding for affordable housing) can create investment opportunities and affect your financial planning. Stay informed about local and state housing policy.

Strategy 7: Invest in Yourself

Consider education, skills training, or starting a side business to increase your earning potential. The best hedge against rising housing costs is increasing your own income.


Frequently Asked Questions About the Future of Housing in California

1. What is the future of housing in California?

The future of housing in California will be shaped by the $11.25 billion housing bond, construction technology innovations, political shifts, and ongoing demographic changes. Experts predict home values will exceed $1 million by 2030.

2. What is the $11.25 billion housing bond?

The Veterans and Affordable Housing Bond Act of 2026 is a ballot measure that, if approved, will provide $10 billion for affordable housing construction and preservation, plus $1.25 billion for the CalVet Home Loan Program.

3. When will the housing bond be on the ballot?

The bond will be placed on the November 2026 ballot.

4. How will the housing bond help homebuyers?

The bond is expected to help more than 40,000 Californians purchase a home through down payment assistance, affordable mortgage financing, and other homeownership support.

5. What is construction technology (Contech)?

“Contech” refers to the use of robotics, data, and design automation to rethink how buildings are made. Innovations include AI-optimized microfactories, digital construction management, and prefab infill homes.

6. How does the insurance crisis affect the future of housing in California?

Rising wildfire risk, insurers leaving the market, and higher construction costs have created new challenges. Lenders require insurance to close mortgages, making this a critical policy issue.

7. What is California’s homeownership rate?

California’s homeownership rate is 55%, compared to the national average of 65%.

8. What is the median home price in California?

The median home price in California is approximately $812,000-$823,000 as of Q1 2026.

9. What is the California affordability index?

Only 17% of California households can afford to purchase a median-priced single-family home.

10. What is the refinancing challenge for affordable housing?

Approximately $860 million in commercial mortgages on fully affordable properties will mature in 2026, rising to $6.9 billion by 2030 and $13.3 billion over the next decade.

11. How does Proposition 13 affect housing?

Proposition 13 caps property taxes at 1% of assessed value and limits annual increases to 2%, creating disparities between long-term owners and new buyers.

12. What is the young adult homeownership rate in Los Angeles?

Young adults aged 25-34 make up only 11% of homeowners in the Los Angeles metro area, the lowest percentage for that demographic in the U.S.

13. What are the most competitive housing markets?

Experts predict California will have the highest average home values, exceeding $1 million by 2030.

14. What is the “K-shaped” economy?

The “K-shaped” economy describes how higher-income households have benefited from asset growth while lower-income households face persistent headwinds. This pattern directly affects the future of housing in California.

15. What should I do to prepare for the future of housing in California?

Start saving early, explore down payment assistance programs, understand your time horizon, consider co-ownership, invest in REITs, stay informed on policy, and invest in yourself.


Key Takeaways & Next Steps

Key Takeaways

  1. The future of housing in California is at a critical crossroads, with the $11.25 billion housing bond, Contech innovations, and political shifts poised to reshape the market.
  2. California faces a severe supply shortage, needing 300,000-500,000 homes annually but building only 100,000.
  3. The homeownership rate is just 55%, among the lowest in the nation.
  4. Experts predict average home values will exceed $1 million by 2030.
  5. Construction technology offers promise but faces challenges, including labor shortages, permitting bottlenecks, and the need for mass customization.

Your Next Steps

  1. Stay informed: Follow the future of housing in California and housing policy developments and the progress of the $11.25 billion housing bond.
  2. Start saving: Begin building your down payment fund as early as possible.
  3. Explore programs: Research down payment assistance programs like California Dream For All.
  4. Invest wisely: Consider REITs and other real estate investments as part of a diversified portfolio.
  5. Plan for the long term: Understand that the future of housing in California requires a 5-10 year perspective.

What to Read Next on FinWireStack


Sources

  1. [^1] Brett Caviness. “What California’s Next Governor Could Mean for Homeowners.” Lifestyle Silicon Valley, March 2026. https://lifestylesiliconvalley.com/blog/what-californias-next-governor-could-mean-for-homeowners
  2. [^2] “California’s affordable housing sector faces a refinancing hurdle.” The Real Deal, December 2025. https://therealdeal.com/la/2025/12/31/california-affordable-housing-faces-refinancing-hurdle/
  3. [^3] Governor of California. “California leaders announce historic Veterans and Affordable Housing Bond Act of 2026.” June 2026. https://www.gov.ca.gov/2026/06/22/california-leaders-announce-historic-veterans-and-affordable-housing-bond-act-of-2026/
  4. [^4] “Can the rise of Contech mitigate the US housing crisis?” Monocle, November 2025. https://monocle.com/business/property/can-contech-mitigate-the-us-housing-crisis/
  5. [^5] “Young adults own just 11% of Los Angeles-OC homes, a national low.” Daily Breeze, May 2026. https://www.dailybreeze.com/2026/05/14/young-adults-own-just-11-of-los-angeles-oc-homes-a-national-low/
  6. [^6] Center for California Real Estate. “2026 California Housing Outlook from CCRE Panelists.” March 2026. https://www.ccre.us/post/2026-california-housing-outlook
  7. [^7] “CA Affordable Housing Challenged With Refinancing.” Globest, December 2025. https://www.globest.com/2025/12/29/ca-affordable-housing-challenged-with-refinancing/
  8. [^8] Assembly Speaker Robert Rivas. “This One Goes to $11 Billion.” June 2026. https://speaker.asmdc.org/press-releases/20260624-one-goes-11-billion-affordable-housing-bond-continues-assembly-democrats
  9. [^9] “GreenFi โ€“ Weekly Recap.” TipRanks, January 2026. https://www.tipranks.com/news/private-companies/greenfi-weekly-recap-2 . The future of housing in California
  10. [^10] “Is Owning a Home in California Worth It?” Tax Shark, January 2026. https://taxsharkinc.com/is-owning-a-home-in-california-worth-it/ . The future of housing in California
  11. [^11] Allen Matkins. “Navigating the New Coastal Zone: Key Housing Reforms for 2026.” May 2026. https://www.allenmatkins.com/real-ideas/navigating-the-new-coastal-zone-key-housing-reforms-for-2026.html . The future of housing in California
  12. [^12] “Predictions rank 2030’s most competitive housing markets. ” Fortune, October 2024. https://fortune.com/2024/10/29/average-housing-price-united-states-2030-real-estate-value-predictions/ . The future of housing in California
  13. [^13] Senator Dave Cortese. “CA Legislative Leaders Deliver on Promise to Keep California Affordable.” June 2026. https://sd15.senate.ca.gov/news/ca-legislative-leaders-deliver-promise-keep-california-affordable-securing-passage-historic . The future of housing in California
  14. [^14] ETCC. “Webinar Presentation on Wildfire-Resilient Construction.” June 2025. https://etcc-ca.com/sites/default/files/2025-06/etcc_webinar_presentation-kumar-final_0.pdf
  15. [^15] BD Nationwide Mortgage. “California First-Time Home Buyer Guide 2026. “June 2026. https://www.bdnationwidemortgage.com/california-first-time-home-buyer-guide/

The Housing Crisis Impact on Personal Finance: 7 Key Lessons for Your Financial Future

Housing crisis impact on personal finance - rising costs and financial stress

Expert Analysis | July 23, 2026 | Reading Time: 23 min


Executive Summary

The housing crisis impact on personal finance is one of the most pressing economic challenges facing Americans today. With rents up 40% since 2000 and wages barely budging, the housing crisis impact on personal finance has become a defining feature of the modern economic landscape.

This comprehensive guide explores the housing crisis impact on personal finance by examining whether it is driven by a shortage of homes, stagnant wages, or both. More importantly, it provides 7 actionable financial strategies for navigating this challenging environment, whether you are a renter, a prospective homebuyer, or an investor seeking to understand the broader economic landscape.

Understanding theย housing crisis’s impact on personal financeย is essential for anyone looking to build wealth, secure their financial future, and make informed decisions in today’s economy.


The Housing Crisis Explained: Supply, Demand, and Costs.

To understand the housing crisis impact on personal finance, we must first understand its root causes. The crisis is fundamentally a supply and demand problem that has been decades in the making.

The Supply Shortage

California is facing a chronic undersupply of housing. According to recent analysis, the state needs roughly 180,000 new homes annually, yet it delivers under 80,000 [^1]. This massive gap between demand and supply is the primary driver of rising housing costs.

Key Supply-Side Issues:

IssueImpact
Restrictive ZoningLimits density and increases land costs
High Construction CostsLabor, materials, and regulations drive prices to $400Kโ€“$500K per unit [^9]
NIMBY OppositionSlows or blocks new development
Slow Approval ProcessesDelays construction and increases carrying costs
Housing supply shortage driving up costs and affecting personal finances.

The Affordability Gap

The gap between what people earn and what housing costs has become a chasm. Rents have risen 40% since 2000, while renter incomes have grown just 9% [^1]. This means families are falling further behind each year.

A renter in California would need to earn nearly three times the minimum wage to afford the average rent [^1]. For households making the minimum wage, the monthly rent they can afford is far below market rates.

The Ripple Effects of High Housing Costs

Housing affordability doesn’t just affect where people liveโ€”it affects every aspect of their financial lives:

  • Reduced Savings:ย Families spending more than 30% or even 50% of their income on housing have little left for savings or emergencies [^3]
  • Increased Debt:ย Credit cards and loans become necessary to cover basic needs
  • Delayed Life Milestones:ย Marriage, children, and retirement are postponed
  • Longer Commutes:ย Families move further from job centers, increasing transportation costs and reducing family time

These ripple effects demonstrate why the housing crisis impact on personal finance extends far beyond monthly rent payments.


The Wage Crisis Explained: Stagnation and the Cost of Living.

Real Wages Have Barely Budged

While housing costs have skyrocketed, wages have remained stubbornly flat. Wages have barely budged since the 1970s, while the cost of livingโ€”especially housingโ€”has increased dramatically [^7].

This wage stagnation is a key driver of the housing crisis impact on personal finance. When wages don’t keep pace with housing costs, families are forced to make impossible choices between paying for housing, food, and healthcare.

The Minimum Wage Mismatch

The gap between what workers earn and what they need to afford housing is stark. In California, a worker needs to earn three times the minimum wage to afford a modest rental unit [^1]. This mismatch directly contributes to the housing crisis impact on personal finance by keeping families trapped in a cycle of housing insecurity.

Cost-Burdened Households

A household is considered cost-burdened when it spends more than 30% of its income on housing. Severely cost-burdened households spend more than 50% [^3]. Data shows that:

  • 79% of extremely low-income rentersย spend more than half of their income on housing [^3]
  • 47.3% of rentersย in some areas are cost-burdened [^12]
  • 1.5 million renter householdsย spend over 50% of their income on housing [^3]

This cost burden is the most direct and measurable housing crisis impact on personal finance.

Cost-burdened households spending more than 30% of income on housing

The Health Impact of Housing Insecurity

The stress of housing insecurity has measurable health impacts. A recent survey found that:

  • Two-thirds of respondentsย reported increased stress and worry due to rising rents [^11]
  • 40%ย reported negative mental health impacts such as anxiety and depression [^11]
  • Nearly 30%ย reported physical health impacts, including sickness, disability, and hypertension [^11]

These health impacts further compound the housing crisis impact on personal finance, as medical expenses add to financial strain.


The Intersection: How Housing and Wages Impact Your Savings and Investments

The Savings Drain

High housing costs are a direct drain on savings. When a family spends 50% of its income on rent, there is little left for:

  • Emergency fundsย (essential for financial stability)
  • Retirement savingsย (compounding lost over decades)
  • Investment capitalย (opportunity cost for building wealth)
  • Home down paymentย (trapping families in the rental cycle)

This savings drain is perhaps the most significant housing crisis impact on personal finance, as it prevents families from building the financial cushion needed to weather economic storms.

The Wealth Gap

Homeownership remains one of the primary ways Americans build generational wealth. Yet California has one of the nation’s lowest homeownership rates among Latino residents compared to white households [^7]. This gap is widening as affordability continues deteriorating.

The wealth gap is a long-term housing crisis impact on personal finance that affects generations. When families cannot build equity through homeownership, they miss out on the primary vehicle for wealth accumulation in America.

The Investment Landscape

Understanding the housing crisis impact on personal finance is essential for investors because:

  • The housing market affectsย mortgage-backed securitiesย and financial markets [^8]
  • Real estate values are influenced byย supply and demand dynamics
  • Companies faceย labor shortagesย when workers can’t afford to live near job centers
  • The crisis createsย opportunitiesย in sectors like affordable housing development, property technology, and construction

Data Deep Dive: California Statistics and Trends.

Homelessness in California

The housing crisis impact on personal finance is perhaps most visible in the homelessness statistics:

MetricStatistic
Total Homeless Population187,000+ people [^1]
Share of U.S. Homeless Population24% [^4]
Share of Unsheltered Homeless45% [^4]
Unsheltered in California65% (vs. 35% nationally) [^4]

Los Angeles County: The Epicenter

Los Angeles County accounts for:

  • 10% of the nation’s total homelessnessย [^10]
  • 19% of unsheltered homelessnessย [^10]
  • More homeless individuals per capita than all but a few U.S. cities

The number of unsheltered homeless per capita in Los Angeles is more than six times greater than the national average [^10].

The “First-Time Homeless” Trend

A troubling new trend is the increase in first-time homelessness. In Napa County, 44% of those experiencing homelessness were counted for the first time, up from 33% in 2025 [^2]. This reflects broader economic pressures affecting a wide swath of the population and demonstrates the widespread housing crisis impact on personal finance.

Regional Disparities

According to the Stanford Institute for Economic Policy Research, homelessness varies dramatically by region [^10]:

RegionTotal Homeless% Unsheltered
Los Angeles County75,30869.5%
Santa Clara County10,39471.2%
Alameda County9,45067.1%
San Francisco8,32352.3%
San Diego County10,60557.6%

What This Means for Your Investments

Understanding the housing crisis impact on personal finance is essential for making informed investment decisions.

Real Estate Investment Trusts (REITs)

The housing crisis presents both risks and opportunities for investors:

  • Multifamily REITs:ย High rental demand could drive returns, but rent control and affordability constraints may limit growth. [^9]
  • Affordable Housing Developers:ย Public-private partnerships and government incentives create opportunities. [^9]
  • Construction Sector:ย Increased focus on housing production could benefit construction companies and materials suppliers. [^9]
Housing crisis impact on personal financeโ€”investment strategies and opportunities

Mortgage-Backed Securities (MBS)

The housing market affects the broader financial system through mortgage-backed securities. While not directly tied to the affordable housing crisis, the health of the housing market has systemic implications [^8].

Labor Markets and Corporate Performance

Companies are facing challenges attracting and retaining talent in high-cost areas. This affects:

  • Labor costsย (higher wages needed to attract workers)
  • Productivityย (long commutes and housing stress reduce output)
  • Talent poolsย (younger workers moving to lower-cost regions)

Emerging Investment Opportunities

The crisis is also creating new opportunities:

  • Proptechย (technology for real estate and construction)
  • Affordable housing investment funds
  • Rent-to-own programsย and innovative housing finance models
  • Factory-built housingย and modular construction

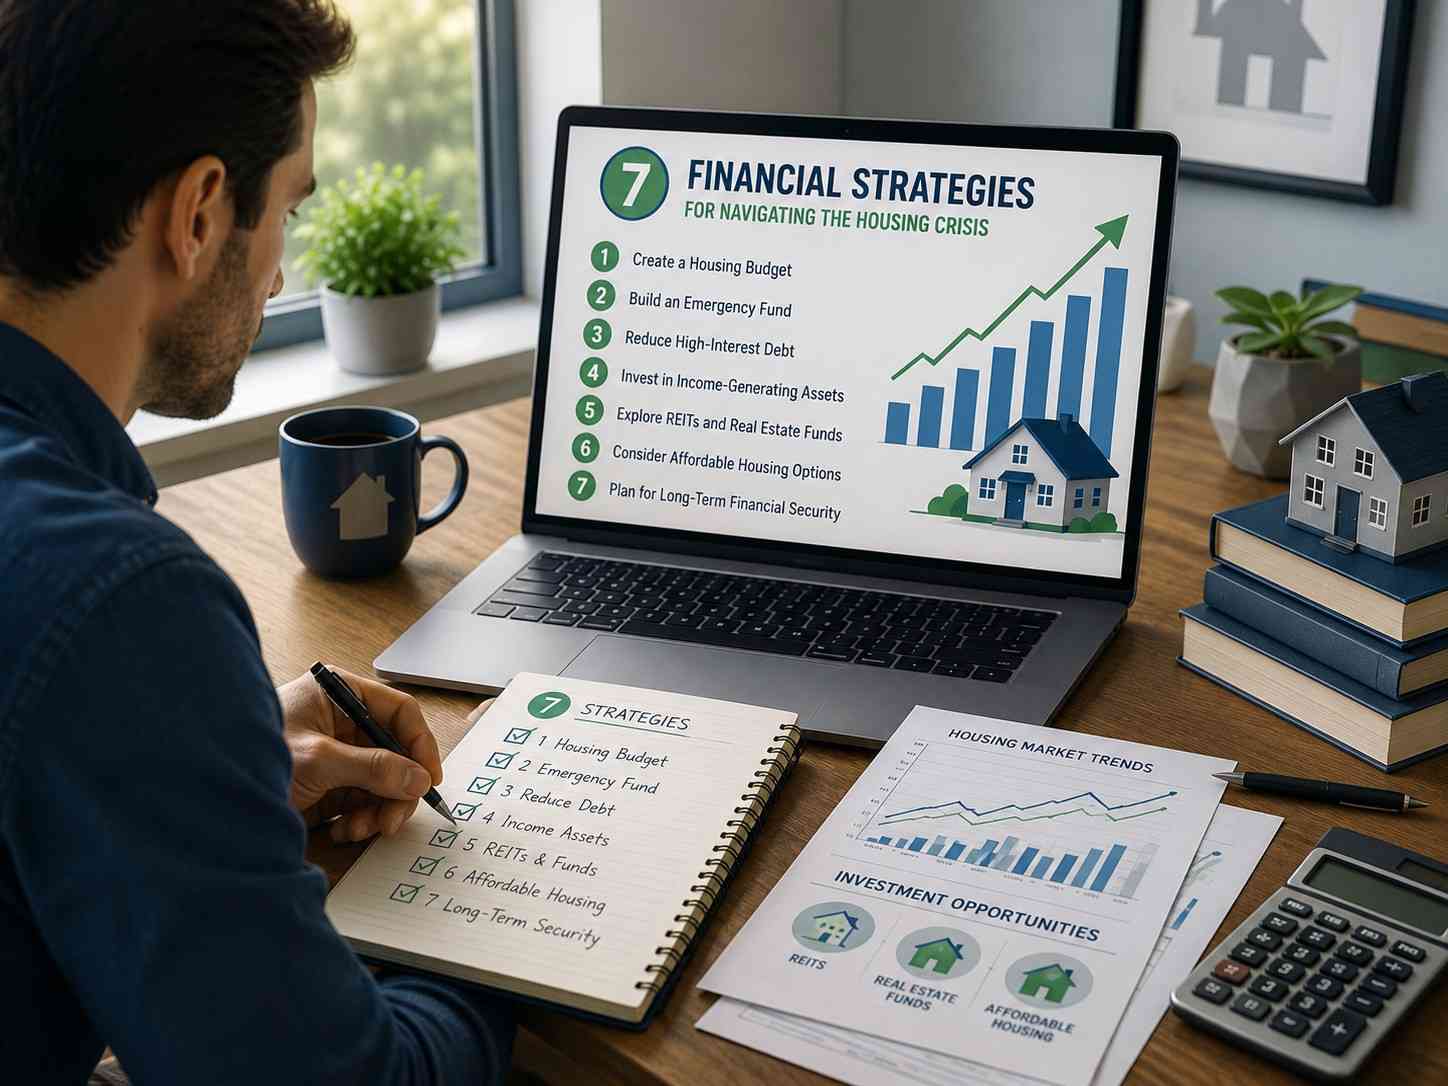
7 Financial Strategies for Navigating the Housing Crisis.

Given the significant housing crisis impact on personal finance, here are 7 actionable strategies to protect and grow your wealth.

7 financial strategies to navigate the housing crisis impact on personal finance

Strategy 1: Create a Housing Budget

Ensure your rent does not exceed 30% of your income. If you’re spending more than 30% on housing, consider the following:

  • Moving to a more affordable neighborhood
  • Getting a roommate to split costs
  • Negotiating your rent
  • Exploring rent-controlled units

Strategy 2: Build an Emergency Fund

High housing costs make emergency savings even more critical. Aim to save at least 3-6 months of living expenses in an easily accessible account.

Strategy 3: Explore Down Payment Assistance

If you’re a prospective homebuyer, look into down payment assistance programs. Many exist for first-time buyers and can significantly reduce the upfront costs of homeownership.

Strategy 4: Consider Co-Owning a Home

Partnering with family or friends can make homeownership more accessible. This can be structured through a tenancy-in-common or a formal co-ownership agreement.

Strategy 5: Invest in Real Estate Investment Trusts (REITs)

If you want real estate exposure without buying a home, consider investing in REITs. These offer diversification and liquidity that direct property ownership cannot provide.

Strategy 6: Stay Informed on Housing Policy

Policy changes (like rent control, zoning reform, and funding for affordable housing) can create investment opportunities. Stay informed about local and state housing policy.

Strategy 7: Invest in Yourself

Consider education, skills training, or starting a side business to increase your earning potential. The best hedge against the housing crisis impact on personal finance is increasing your own income.


Frequently Asked Questions About the Housing Crisis Impact on Personal Finance.

1. What exactly is the housing crisis impact on personal finance?

The housing crisis impact on personal finance refers to the ways in which rising housing costs affect an individual’s or family’s financial health, including reduced savings, increased debt, delayed life milestones, and long-term wealth inequality.

2. How does the housing crisis affect my savings?

High housing costs directly reduce your ability to save. When you spend more on housing, you have less to put toward emergency funds, retirement, and other financial goals.

3. What is the connection between housing and the wealth gap?

Homeownership is a primary way Americans build generational wealth. The housing crisis makes it harder to buy a home, widening the wealth gap between homeowners and renters.

4. What is the difference between a cost-burdened and severely cost-burdened household?

A cost-burdened household spends more than 30% of its income on housing. A severely cost-burdened household spends more than 50%. Both situations reflect a negative housing crisis impact on personal finance.

5. How does housing insecurity affect health?

Housing insecurity causes significant stress, which can lead to anxiety, depression, and physical health issues. It also forces families to cut back on essential needs like food, medical care, and health insurance [^11].

6. What is the supply shortage in housing?

California needs roughly 180,000 new homes annually but builds under 80,000 [^1]. This supply shortage drives up prices and is a primary cause of the housing crisis impact on personal finance.

7. How does wage stagnation contribute to the housing crisis?

While housing costs have risen dramatically, wages have barely budged since the 1970s [^7]. This means families have less purchasing power to afford housing, exacerbating theย impact of the housing crisis on personal finances.

8. What is a housing voucher?

A housing voucher (like Section 8) provides rental subsidies for low-income individuals by paying landlords directly. However, vouchers are available to far too few eligible households [^1].

9. What is the Roadmap Home?

The Roadmap Home is a policy agenda released by Housing California and the California Housing Partnership. It includes policies designed to end the state’s housing and homelessness crisis [^1].

10. How does the housing crisis affect investors?

The crisis affects real estate markets, construction costs, labor availability, and economic stabilityโ€”all of which have implications for investment strategies.

11. What is workforce housing?

Workforce housing is housing affordable to households earning between 60 and 120 percent of area median income. This includes teachers, nurses, and emergency responders [^9].

12. How are Latino families affected by the housing crisis?

Latino families are disproportionately rent-burdened and live in overcrowded homes due to cost pressures [^7]. They are also facing displacement from historically Latino neighborhoods.

13. What is the impact of the housing crisis on the broader economy?

The crisis affects labor markets, productivity, consumer spending, and financial system stability. It’s also a driver of economic inequality.

14. What are the most effective solutions to the housing crisis?

Research shows that a combination of approaches is needed: building more affordable housing, protecting renters through policies like rent control, providing rental vouchers, and pairing housing with supportive services [^1].

15. What can I do as an individual to address the housing crisis?

You can support affordable housing in your community, stay informed about local housing policy, vote for candidates who prioritize housing solutions, and educate yourself about the root causes of the crisis.


Key Takeaways & Next Steps

Key Takeaways

  1. The housing crisis’s impact on personal financeย is a defining economic challenge of our time, affecting savings, investments, and long-term wealth
  2. Rents have risen 40% since 2000, while renter incomes have grown just 9%, creating an unsustainable gap [^1]
  3. California has 187,000+ unhoused residents, 24% of the national total, reflecting the severity of the crisis. [^4]
  4. The crisis is driven by a severe supply shortage, with the state needing 180,000 new homes annually but building under 80,000. [^1]
  5. Housing insecurity has significant health impacts, including increased stress, anxiety, and physical illness [^11]

Your Next Steps

  1. Assess your housing budget:ย Ensure you’re not spending more than 30% of your income on housing
  2. Build an emergency fund:ย Aim for 3-6 months of living expenses
  3. Explore all options:ย Look into down payment assistance, renter protection programs, and housing counseling services
  4. Stay informed:ย Follow housing policy developments at the state and local level
  5. Invest wisely:ย Consider REITs and other real estate investments as part of a diversified portfolio

What to Read Next on FinWireStack


Sources

  1. [^1] Housing California & California Housing Partnership. “Roadmap Home,” 2026.ย https://housingca.org/news-media/statements/housing-leaders-in-california-release-a-roadmap-home-to-protect-renters/
  2. [^2] The Press Democrat. “Napa County’s homeless population increases,” July 2026. (Cited in KSRO article:ย https://www.ksro.com/2026/07/08/north-bay-homelessness-up-as-first-time-cases-surge/)
  3. [^3] National Low Income Housing Coalition. “Out of Reach: The High Cost of Housing,” 2025.ย https://nlihc.org/news/nlihc-releases-out-reach-2025-high-cost-housing
  4. [^4] Center for California Real Estate. “Shelter to Stability: Four Insights from CCRE’s Expert Panel on Homelessness,” December 2025.ย https://www.ccre.us/post/shelter-to-stability-four-insights-from-ccre-s-expert-panel-on-homelessness
  5. [^5] Morningstar. “Should you invest in shares or save for a house deposit?” October 2025.ย https://dfd.dr.morningstar.com.au/personal-finance/young-invested-should-you-invest-in-shares-or-save-for-a-house-deposit
  6. [^6] Hartford Funds. “Should You Invest in the Stock Market or Real Estate?”ย https://www.hartfordfunds.com/dam/en/docs/pub/whitepapers/CCWP152.pdf
  7. [^7] Parriva. “California’s Budget Still Doesn’t Solve the Latino Housing Crisis,” May 2026.ย https://parriva.com/news/californias-budget-still-doesnt-solve-the-latino-housing-crisis/
  8. [^8] Advisor Perspectives. “Then and Now: Mortgage-Backed Securities Post-Financial Crisis,” 2025.ย https://www.advisorperspectives.com/articles/2025/09/22/then-and-now-mortgage-backed-securities
  9. [^9] Multifamily & Affordable Housing Business. “Affordable Housing Remains Key to Homelessness Prevention,” 2025.ย https://www.multifamilyaffordablehousing.com/news/affordable-housing-remains-key-to-homelessness-prevention/
  10. [^10] Stanford Institute for Economic Policy Research. “Homelessness in L.A.: Evidence from temporary shelter,” 2024.ย https://siepr.stanford.edu/publications/policy-brief/homelessness-la-evidence-temporary-shelter
  11. [^11] Health in Partnership. “California Renter Health Survey,” January 2026.ย https://healthinpartnership.org/california-renter-health-survey/
  12. [^12] CityWatch LA. “Some Housing Prices Are Falling In LA, But Homelessness And Overcrowding Are Increasing,” May 2026.ย https://citywatchla.com/some-housing-prices-are-falling-in-la-but-homelessness-and-overcrowding-are-increasing/