Category Stock Investing Education

Nvidia Buyback Meets 5.2% Treasury Yields: What the AI Debt Dilemma Means for Investors
Nvidia buyback and bond yields

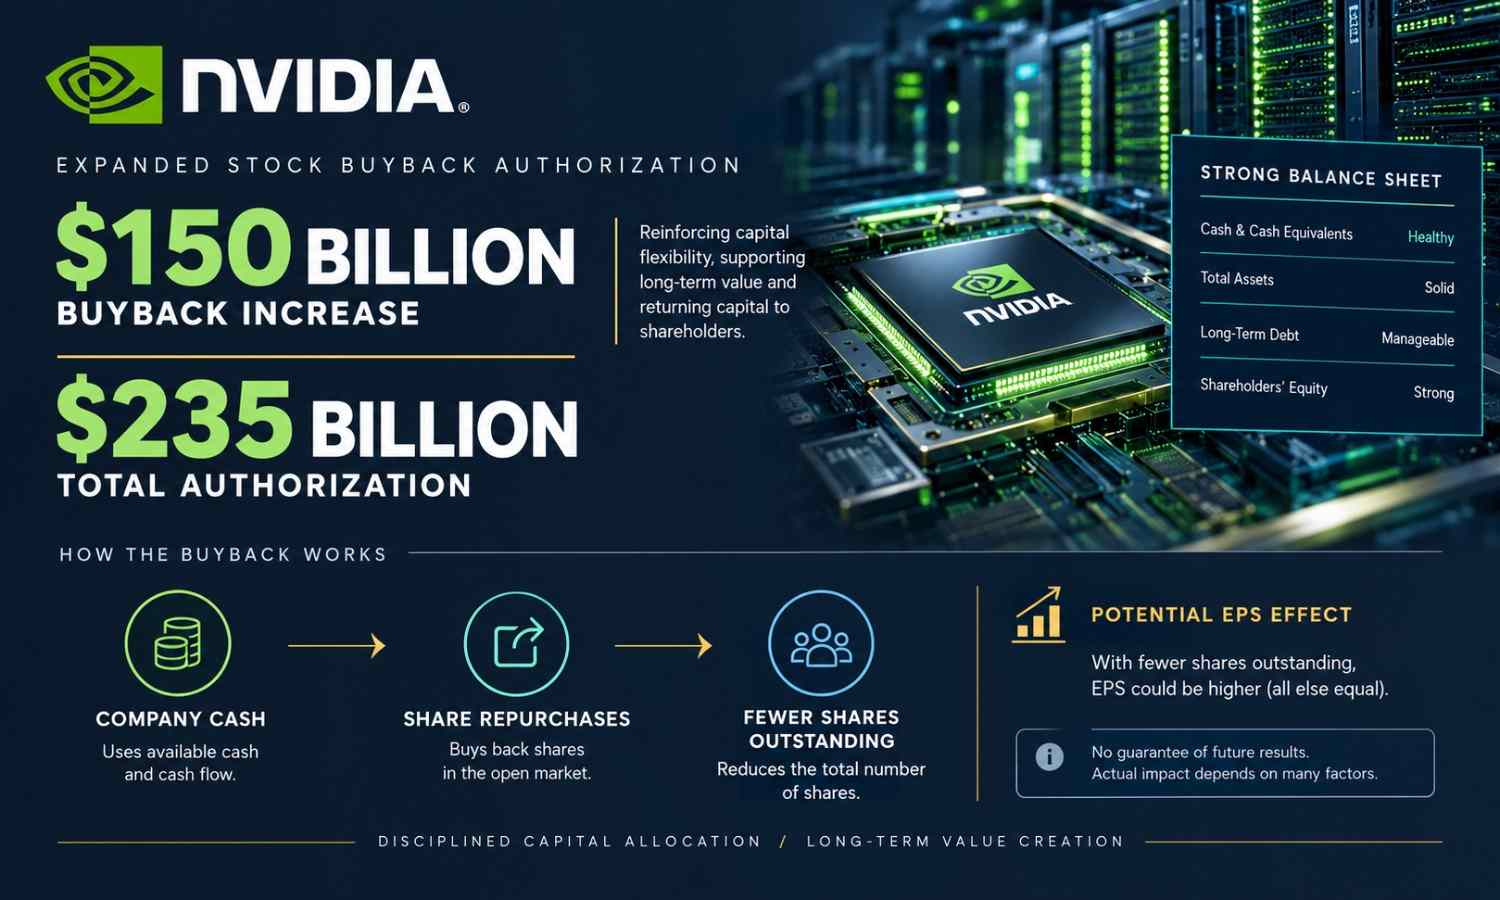
Nvidia has just sent one of the strongest signals yet that it believes the artificial-intelligence boom still has a long runway. On September 28, 2026, the chipmaker announced a $150 billion increase to its share repurchase authorization, taking its total available authorization to $235 billion.

The announcement arrived at an uncomfortable moment for the broader AI investment story.

U.S. Treasury yields have been climbing sharply, with the 10-year yield moving above 5.2% and later reaching approximately 5.27%, while oil prices have added to inflation concerns. At the same time, major technology companies are borrowing heavily to finance data centers, computing infrastructure and other AI-related capital expenditures.

That creates an important distinction for investors.

Nvidia is not borrowing $150 billion to fund its stock buyback. Instead, the company’s enormous cash-generation capacity allows it to return capital to shareholders while continuing to invest in its business. The bigger question is whether the companies building the infrastructure required to support the AI boom can continue financing that expansion at increasingly higher interest rates.

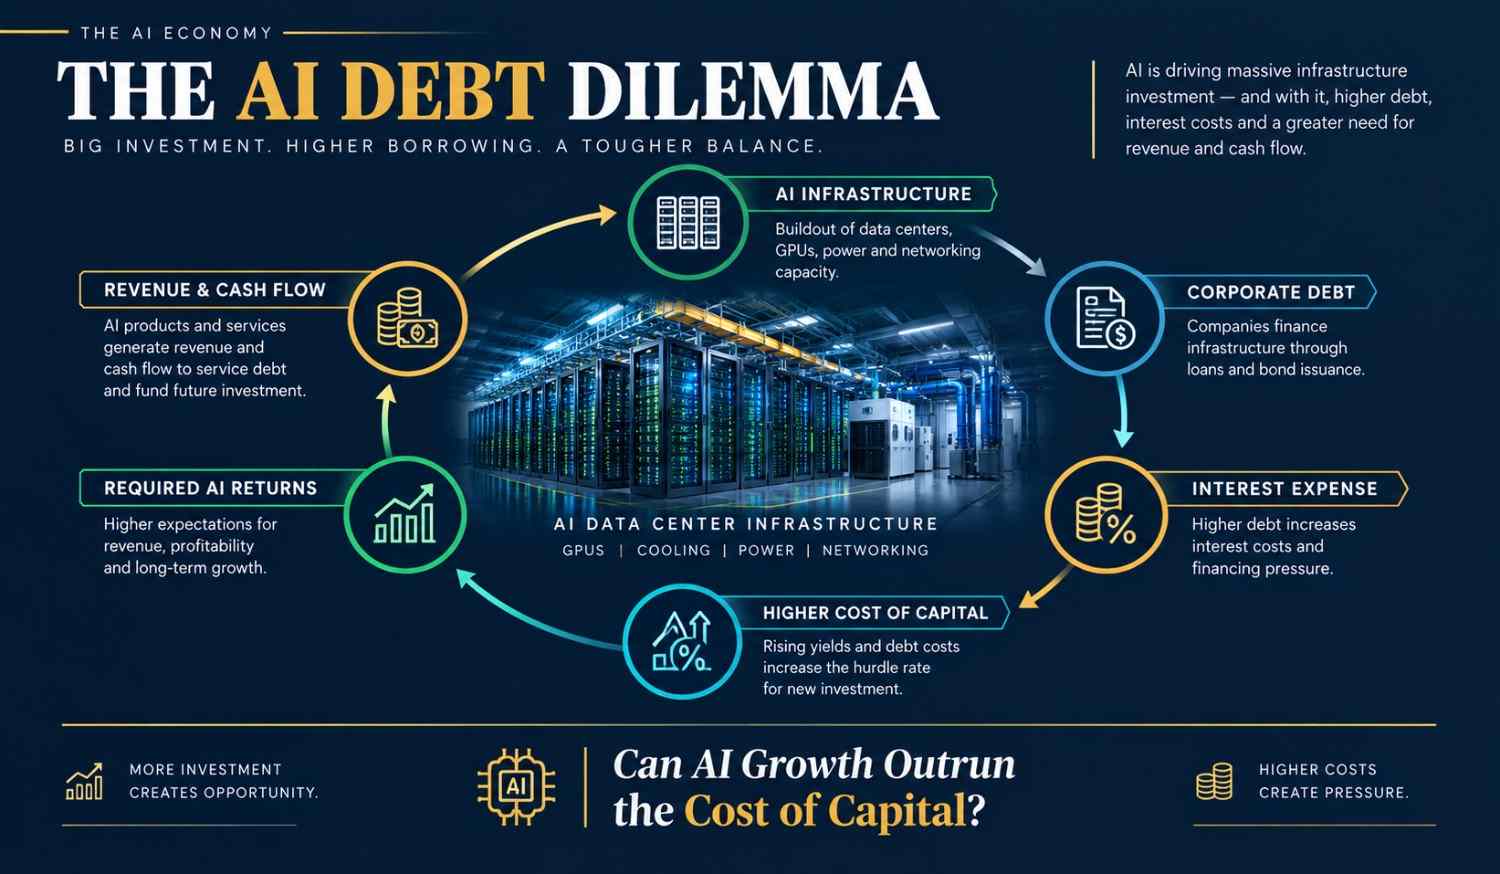
This is the emerging AI debt dilemma: can the revenue and productivity created by artificial intelligence grow quickly enough to justify a dramatically higher cost of capital?

The answer matters not only for Nvidia but also for semiconductor stocks, cloud companies, corporate bonds and portfolios exposed to the broader AI trade.

Key Takeaways

  • Nvidia increased its share repurchase authorization by $150 billion, taking total authorization to $235 billion.
  • The move signals management’s confidence, but a buyback does not eliminate valuation, competitive, or industry risks.
  • The U.S. 10-year Treasury yield has moved above 5.2%, increasing the opportunity cost of owning riskier assets and raising corporate financing costs.
  • AI-related companies are increasingly relying on debt to finance data-center expansion, making interest rates and credit spreads increasingly important.
  • The critical investment question is shifting from simply โ€œHow fast is AI growing?โ€ to โ€œWhat return will companies generate on the enormous capital being deployed?โ€

Nvidia’s $150 Billion Buyback Is a Major Signal

What Nvidia’s Buyback Really Signals to Wall Street

Nvidia’s latest capital-return decision is extraordinary by historical standards.

The company announced an additional $150 billion share repurchase authorization, lifting its total authorization to $235 billion. Reuters reported that the new authorization exceeds Apple’s previous $110 billion record announced in 2024. Nvidia intends to use the expanded authorization through fiscal 2028, subject to market conditions and other considerations.

The significance goes beyond the headline number.

A stock buyback allows a company to use cash to purchase its own shares. When shares are retired, the number of shares outstanding falls. If earnings remain constant, earnings per share can increase because those earnings are distributed across fewer shares.

But investors should avoid treating buybacks as automatic evidence that a stock is undervalued.

The more meaningful signal from Nvidia is its confidence in its cash-generation capacity.

Nvidia’s fiscal 2026 results already showed substantial shareholder returns. The company repurchased approximately $40.4 billion of stock during that fiscal year. Its subsequent quarterly filing showed another $39.8 billion of repurchases during the first half of fiscal 2027.

The September authorization therefore represents a substantial escalation in the amount of capital potentially available for future repurchases.

Management has also continued to emphasize that AI and accelerated computing represent a major long-term platform shift.

That creates two possible interpretations for investors.

The bullish interpretation is straightforward: Nvidia believes demand for AI computing will remain strong enough to generate substantial free cash flow, even while the company continues investing heavily in future technologies.

The more cautious interpretation is that the market should focus on cash flow per share, earnings growth, and valuation, rather than the headline size of the authorization.

A company can repurchase billions of dollars of stock and still deliver disappointing shareholder returns if its future earnings growth slows dramatically or the shares are purchased at an excessive valuation.
Nvidia $150 billion stock buyback authorization

In other words, a stock buyback can amplify shareholder value when the underlying business is performing well, but it cannot replace fundamental business growth.

Why 5.2% Treasury Yields Change the AI Investment Equation

The other side of this story is the bond market.

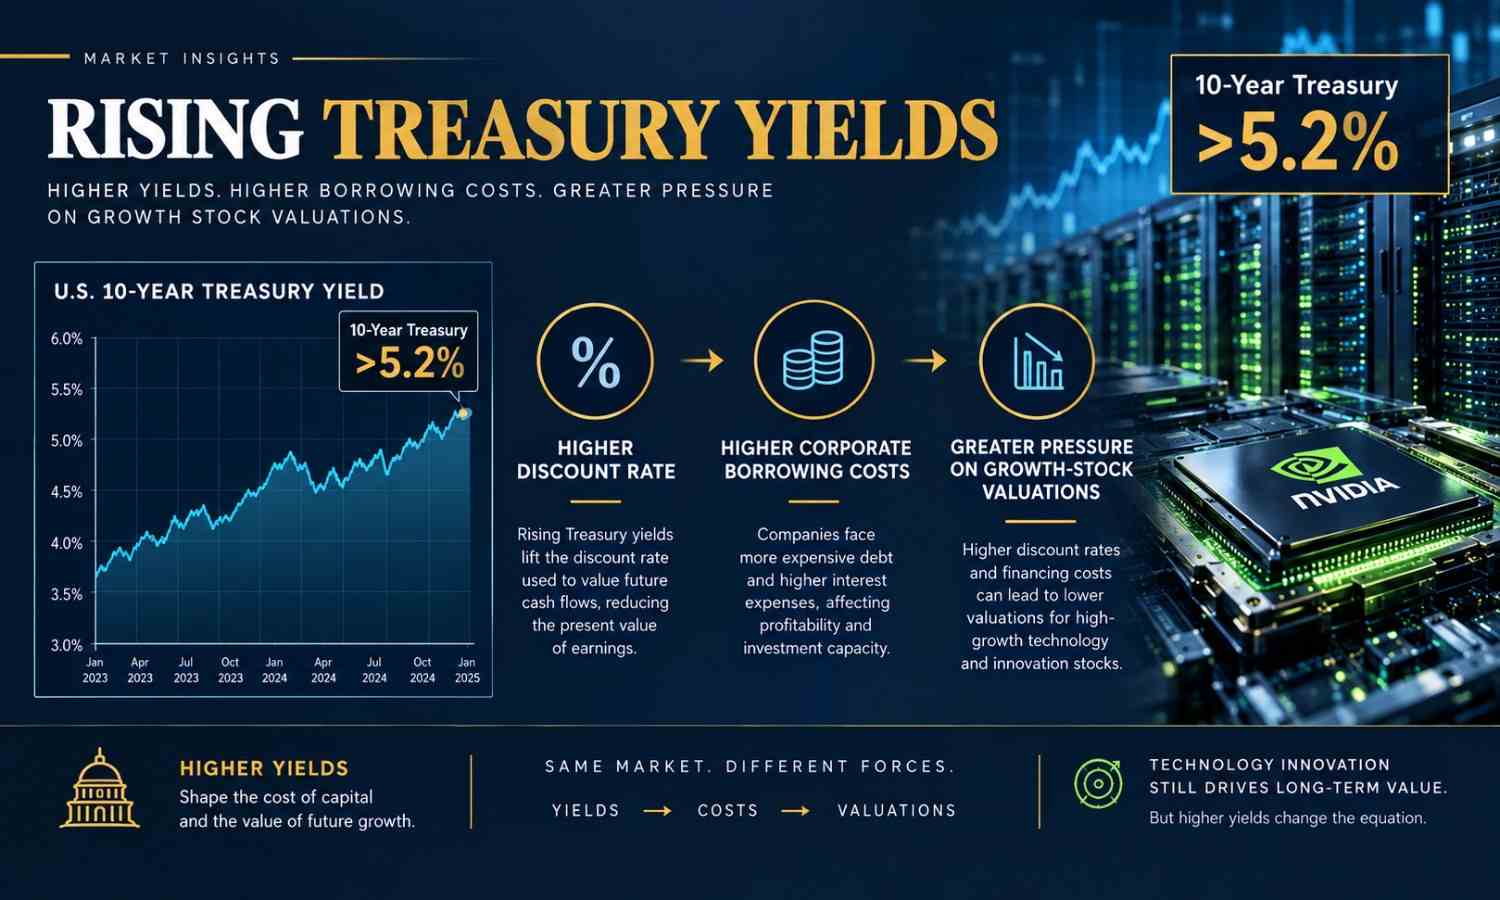
The U.S. 10-year Treasury yield has moved above 5.2%, reaching roughly 5.27% in the latest market reporting. Reuters described the move as part of a broader bond-market selloff, with long-term yields reaching multi-year highs.

The combination matters because Treasury yields influence the cost of money throughout the financial system.
U.S. Treasury yields and AI stock valuations

When government bond yields rise, investors can demand higher returns from corporate bonds and other risk assets. Companies issuing new debt may therefore need to pay higher coupons or offer investors greater compensation for taking credit risk.

That is particularly important for businesses undertaking enormous capital projects.

AI data centers require land, electricity, cooling systems, networking equipment, GPUs, CPUs, memory and other infrastructure. The spending can be enormous, and companies do not necessarily fund all of it from current operating cash flow.

Some of the financing therefore comes from debt.

And this is where the AI debt dilemma becomes more important.

The Feedback Loop: How AI Debt Can Pressure the Market

Consider a simplified chain:

More AI investment โ†’ more corporate borrowing โ†’ greater bond supply โ†’ higher required financing costs โ†’ higher capital expenditure โ†’ greater pressure to generate returns.

This does not mean every new AI bond is dangerous.

Large technology companies can have significant cash flows, valuable intellectual property and strong balance sheets. Reuters reported, for example, that AI-related corporate bond issuance has become large enough for investors to become more selective, with major issuers including Alphabet and Meta facing greater scrutiny over the scale and predictability of their borrowing needs.

Reuters has estimated that AI-related bond issuance could reach approximately $420 billion in 2027.

That is a critical development for investors.

The AI investment story is increasingly becoming a capital-allocation story.

The question is no longer only whether companies can sell more AI services. Investors must also ask how much capital those companies must deploy to produce each additional dollar of revenue and how much that capital costs.

Rising oil prices complicate the equation further because higher energy costs can reinforce inflation pressures and make it harder for central banks to reduce interest rates quickly.

For technology stocks whose valuations depend heavily on future earnings, that combination can matter enormously.

The AI Debt Dilemma: Can Growth Outrun the Cost of Capital?

This is where the Nvidia story becomes more interesting than a simple buyback headline.

Nvidia itself is not the obvious example of an AI company being squeezed by debt financing.

The bigger concern is the ecosystem around Nvidia.

Hyperscalers and other infrastructure providers are spending enormous amounts to construct the computing capacity needed for AI. Reuters reported that hyperscalers had issued approximately $220 billion of bonds during the year, while concerns over financing costs and credit spreads were beginning to appear in the corporate debt market.

Oracle and Meta are among the companies attracting attention because of their capital requirements and financing activity.

The fundamental issue is return on invested capital.
AI debt dilemma and data center financing

Suppose a company spends $100 billion building AI infrastructure. Investors ultimately need to know whether that infrastructure can produce returns sufficiently above the company’s cost of capital.

If interest rates rise, the hurdle becomes higher.

If revenue grows rapidly enough, the investment can still work.

However, if revenue growth disappoints while borrowing costs rise, the economics become less attractive.

This is why investors should distinguish between AI demand and AI investment returns.

The first can be extremely strong while the second remains uncertain.

Intel and AMD Show That AI Demand Is Still Real

The semiconductor market provides another important piece of the puzzle.

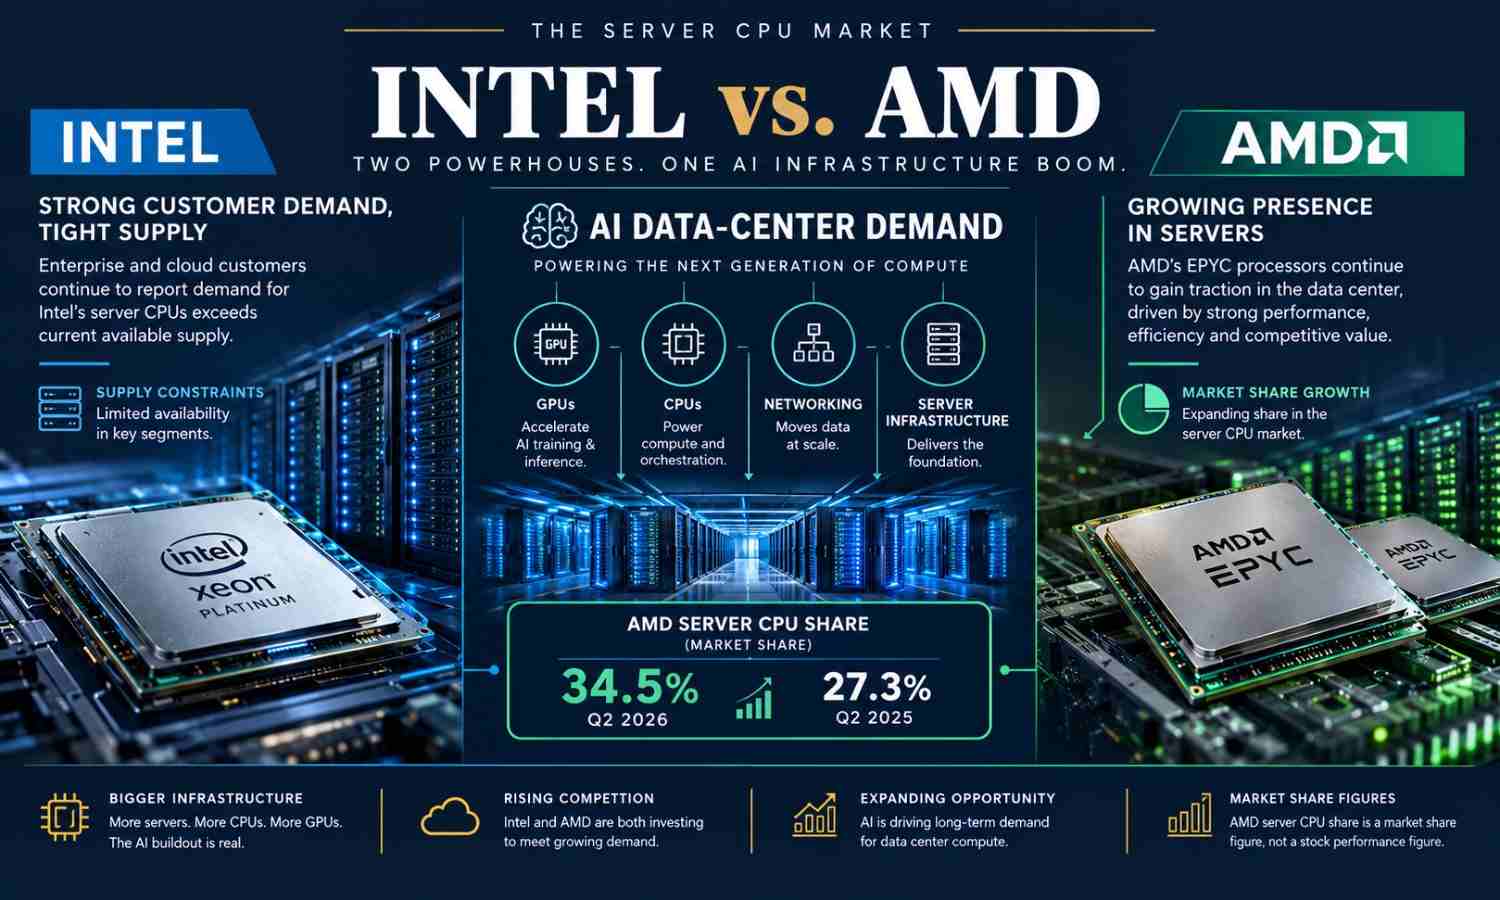
Intel CEO Lip-Bu Tan recently said the company could supply only about half of what customers were requesting, highlighting how strong processor demand has become.

That shortage is particularly interesting because AI infrastructure requires more than GPUs.

Modern AI systems also depend on CPUs, memory, networking, and other components. The expansion of agentic AI and inference workloads is increasing the importance of general-purpose computing.

AMD is benefiting from this broader demand.

Mercury Research data cited in recent reporting showed AMD’s server CPU unit share reaching 34.5% in the second quarter of 2026, compared with 27.3% a year earlier.

AMD has also projected that its server CPU total addressable market could grow at more than 50% annually through 2030 and reach approximately $220 billion.

Its data center revenue increased 107% year over year in the second quarter, according to reporting surrounding the Intel development.

These numbers illustrate an important point:

The AI infrastructure boom is not imaginary.
AMD and Intel server CPU demand in AI infrastructure

There is real demand for processors and data-center capacity.

But genuine demand does not automatically mean every infrastructure investment will generate attractive returns.

That distinction could become one of the defining investment themes of the next phase of the AI cycle.

What Nvidia’s Buyback Means for Different Investors

Growth Investors: Watch Earnings, Not Just Buybacks

For growth investors, Nvidia’s buyback may reinforce confidence in management’s long-term expectations.

However, the most important metrics remain:

  • Data-center revenue growth
  • Gross and operating margins
  • Free cash flow
  • AI accelerator demand
  • Customer concentration
  • Competitive developments
  • Capital expenditure across major AI customers
  • Forward earnings expectations

A large buyback should be treated as additional information, not as a substitute for fundamental analysis.

Investors following AI stocks should also monitor whether hyperscalers continue increasing capital expenditure and whether that spending translates into profitable AI services.

Income Investors: Rising Yields Change the Competition

For income-oriented investors, higher Treasury yields create a different opportunity set.

When government bonds offer materially higher yields, investors have an alternative to dividend-paying equities and lower-rated corporate debt.

That can influence valuations.

A technology company with a relatively low dividend yield may need stronger earnings growth to justify its valuation when investors can earn substantially more from high-quality government bonds.

This is one reason bond yields matter to stock-market valuation even when the company itself has little debt.

Conservative Investors: Diversification Matters More

For conservative portfolios, the current environment highlights the importance of diversification.

A portfolio concentrated entirely in high-growth technology stocks can become particularly sensitive to changes in interest rates and valuation multiples.

Investors may therefore consider how stocks, Treasury securities, corporate bonds, cash equivalents, and other assets interact within their broader portfolio management strategy.

The objective is not necessarily to abandon AI.

It is to understand the different risks attached to each part of the market.

How to Position a Portfolio in a High-Rate, AI-Driven Market

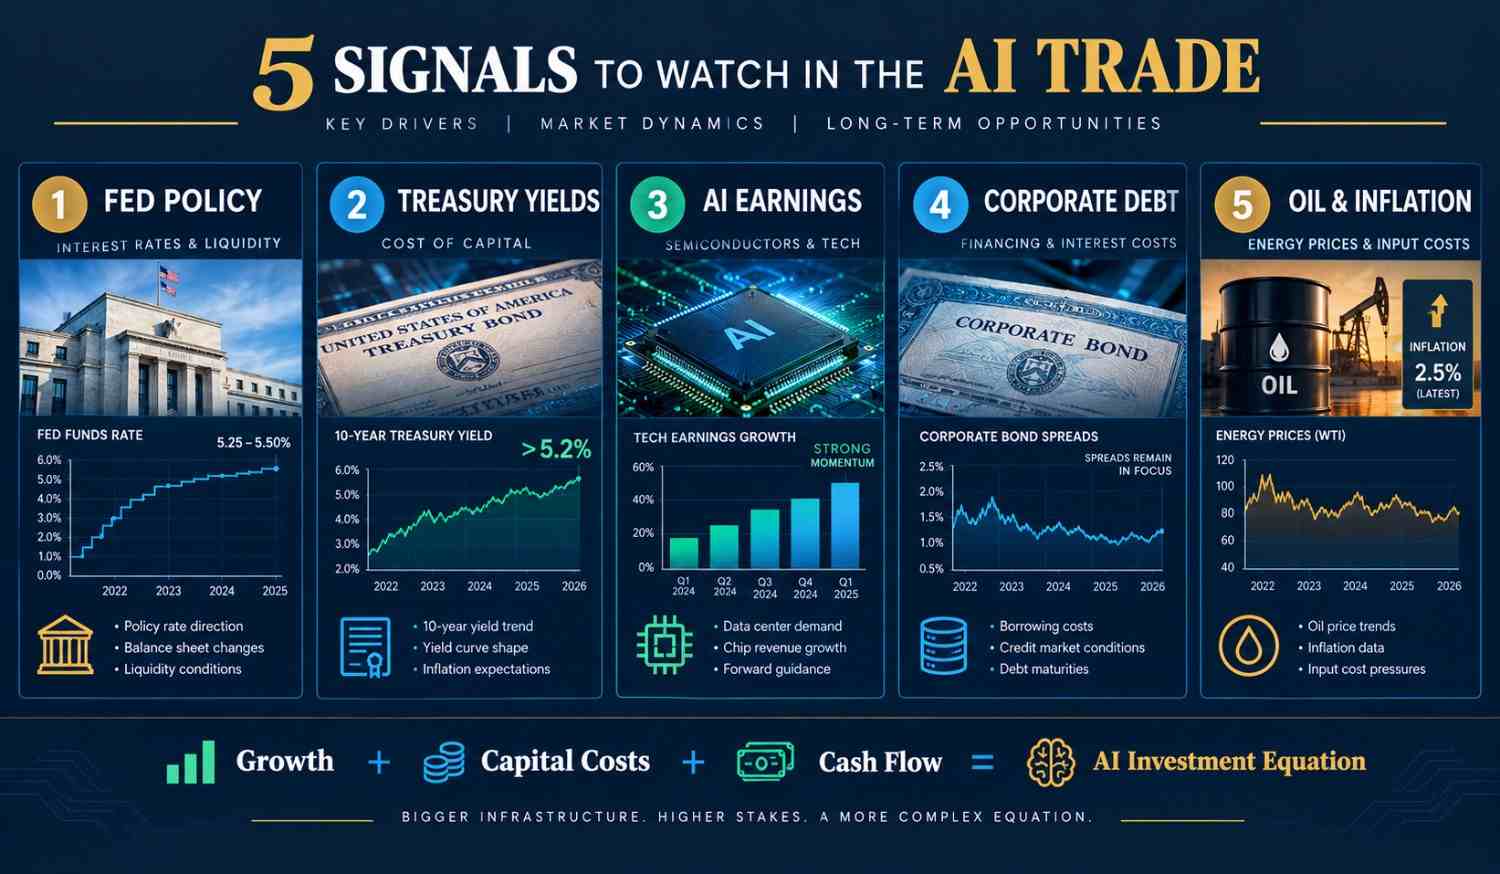
Rather than asking whether Nvidia is automatically a buy or sell because of the announcement, investors can monitor several measurable signals.

1. Follow the 10-Year Treasury Yield

A sustained move higher would generally increase the discount rate applied to future corporate earnings.

A meaningful decline could have the opposite effect.

2. Track Corporate Bond Spreads

Treasury yields show the risk-free benchmark.

Credit spreads show how much additional compensation investors demand for lending to corporations.

If AI-related spreads continue widening, that could indicate growing concern about the amount of capital being deployed.

3. Watch AI Capital Expenditure

The next question is not simply whether companies are spending more.

Investors should examine whether companies are generating enough revenue and operating cash flow to justify that spending.

4. Monitor Nvidia’s Free Cash Flow

The buyback is supported by Nvidia’s ability to generate cash.

That makes free cash flow particularly important.

If cash generation continues to grow alongside AI demand, the capital-return argument becomes stronger. If cash flow growth slows sharply, investors may reassess the pace and sustainability of repurchases.

5. Watch Semiconductor Competition

Nvidia is not operating in isolation.

AMD, Intel, and other semiconductor companies are competing for different portions of the AI computing market.

The server CPU shortage reported by Intel is evidence of strong underlying infrastructure demand, while AMD’s market-share gains demonstrate that the competitive landscape continues to evolve.

What Investors Should Watch Next

The AI investment narrative could change quickly as new economic and corporate data arrive.
AI investment market outlook and investor dashboard

Federal Reserve policy

The September rate increase puts additional focus on future inflation and employment data.

If inflation remains elevated, investors may need to price in higher rates for longer.

If inflation falls substantially, pressure on long-term yields could ease.

Treasury yields

The 10-year Treasury is now one of the most important variables for technology-stock valuations.

Investors should watch whether yields stabilize, continue rising, or reverse lower.

Nvidia, AMD and Intel earnings

Quarterly results will provide direct evidence about whether AI demand is translating into revenue and profit.

For Nvidia, investors should pay particular attention to data-center growth, margins and free cash flow.

For AMD and Intel, server CPU demand and supply constraints will remain important.

Corporate debt issuance

Investors should monitor how much additional debt major technology companies issue and at what cost.

A rising volume of issuance is not automatically negative. The key question is whether the returns generated by the underlying AI infrastructure justify the financing cost.

Oil and inflation

Higher energy prices can complicate the Federal Reserve’s inflation fight.

That makes oil another variable investors should monitor alongside Treasury yields and corporate credit spreads.

The Bottom Line: Nvidia’s Buyback Is a Confidence Signal, Not a Shield

Nvidia’s $150 billion buyback expansion is one of the most significant corporate capital-return announcements of 2026. It demonstrates that management believes the company can continue generating enough cash to invest in AI while returning substantial capital to shareholders.

But investors should not confuse that confidence with immunity from macroeconomic risk.

The more important story is happening across the broader AI financing ecosystem.

Nvidia can have exceptional cash generation while other companies building AI infrastructure face increasingly expensive financing.

That is the heart of the AI debt dilemma.

The AI boom may continue to produce enormous demand for GPUs, CPUs, networking equipment, and data centers. Intel’s supply constraints and AMD’s rising server CPU share provide evidence that the infrastructure cycle remains powerful.

At the same time, a 5%+ Treasury environment changes the mathematics of investment.

The hurdle for capital-intensive projects becomes higher. Corporate borrowers may have to pay more to finance expansion. Investors have more attractive alternatives in fixed income. And technology valuations become more sensitive to the discount rate applied to future earnings.

For investors, the most useful question is therefore not simply โ€œIs AI still growing?โ€

It is:

โ€œAre AI companies generating returns that justify the capital being committed to the AI buildout?โ€

That question will increasingly connect Nvidia’s buyback, Treasury yields, corporate debt, semiconductor competition, and the future direction of the stock market.

For more evidence-based analysis of investing, technology, and financial markets, subscribe to FinWireStack and follow the next developments in the AI investment cycle.

Key Takeaways

  1. Nvidia’s $150 billion buyback expansion takes its total authorization to $235 billion and represents a major capital-return commitment.
  2. Nvidia is not borrowing $150 billion to fund the buyback. The debt concern is primarily about the wider AI infrastructure financing cycle.
  3. Treasury yields above 5.2% raise the opportunity cost of equities and increase financing costs across the corporate market.
  4. AI demand remains strong, with Intel reporting severe server CPU supply constraints and AMD continuing to gain server CPU market share.
  5. The next phase of the AI investment story will increasingly depend on return on invested capital, free cash flow, debt costs, and sustainable revenue growth rather than AI spending alone.

FinWireStack provides educational and informational market commentary and does not provide individualized investment advice. Market conditions can change rapidly. Investors should consider their objectives, time horizon, and risk tolerance and conduct independent research before making investment decisions.

Fidelity Investments Explained: A Complete Beginner’s Guide to Investing in the U.S. in 2026

Fidelity Investments beginner guide to investing in the United States

If you have never invested before, the financial world can feel intimidating.

You hear people talking about stocks, ETFs, index funds, 401(k)s, Roth IRAs, mutual funds, dividends, capital gains, and compound interest.

Then you hear another name repeatedly:

Fidelity Investments.

But what exactly is Fidelity?

Is Fidelity a bank?

Is Fidelity a stock?

Is Fidelity an investment fund?

Can you buy stocks through Fidelity?

How much money do you need?

And, most importantly, how does a complete beginner actually use Fidelity Investments to start building wealth?

This guide answers those questions from the ground up.

By the end, you should understand what Fidelity is, what it offers, how the different accounts work, what you can invest in, what the major risks are, and what a sensible beginner investing journey could look like.

Important: Fidelity is not an investment itself. Fidelity is a financial-services company and investment platform through which eligible customers can access different financial products.


What Is Fidelity Investments?

Fidelity Investments is one of the major financial services companies serving U.S. investors.

Through its platforms, Fidelity provides access to investment accounts, stocks, ETFs, mutual funds, bonds, retirement accounts, managed investing, and other financial services. Fidelity’s current account lineup includes brokerage accounts, retirement accounts, managed solutions, cash-management products, crypto offerings, and accounts for children and education.

Think of Fidelity as a financial supermarket.

You do not go to Fidelity simply to “buy Fidelity.”

Instead, you open an appropriate account and then decide which investments belong inside that account.

For example:

Fidelity account โ†’ ETF โ†’ stocks inside the ETF

or

Fidelity IRA โ†’ mutual fund โ†’ diversified portfolio

or

Fidelity brokerage account โ†’ individual stocks

This distinction is fundamental for beginners.


Fidelity Investments in Simple Terms

Imagine you want to build a house.

You need:

  • A place to build
  • Building materials
  • Tools
  • A construction plan

Your Fidelity account is similar to the place where your investments are held.

Your stocks, ETFs, bonds and mutual funds are the building materials.

Your investment strategy is the construction plan.

Fidelity provides the platform and tools.

You still need to decide what you are building.


Why Is Fidelity Investments Getting So Much Attention?

The interest surrounding Fidelity fits into several major changes happening in U.S. investing.

AI and Technology

Artificial intelligence has become a major investment theme.

Fidelity’s own 2026 research identifies AI infrastructure as a major economic force and points to potential opportunities across semiconductor companies, utilities, energy, and other businesses supporting AI infrastructure.

Low-Cost Investing

Investors increasingly focus on fees because even small recurring costs can significantly affect long-term returns.

Fidelity currently advertises $0 online commissions for U.S. stocks and ETFs and offers zero-expense-ratio index mutual funds.

Fractional Investing

Fidelity allows eligible investors to purchase fractional shares, with its brokerage materials stating that investors can start with as little as $1.

Retirement Investing

Americans continue to use retirement accounts such as 401(k)s and IRAs to build long-term wealth.

For 2026, the IRS says the annual IRA contribution limit is $7,500, with an additional $1,100 catch-up contribution for eligible investors aged 50 and above.

Crypto

Fidelity has also expanded into digital assets.

Its current crypto offerings includes Bitcoin, Ethereum, Fidelity Digital Dollar, Litecoin, and Solana, and Fidelity also offers crypto-related exchange-traded products.

These trends help explain why understanding Fidelity Investments is increasingly relevant to people learning about modern U.S. investing.


How Does Fidelity Investments Actually Work?

The process is surprisingly simple.

Step 1: Choose an Account

You first decide what type of account you need.

Step 2: Deposit Money

You transfer money into the account.

Step 3: Select Investments

You choose stocks, ETFs, mutual funds, bonds or another eligible investment.

Step 4: Place the Investment

You purchase the investment.

Step 5: Monitor and Rebalance

You review your portfolio periodically and make adjustments when appropriate.

The biggest beginner mistake is believing that depositing money into Fidelity automatically means you are invested.

It does not.

Cash sitting inside an account is different from money invested in a security.


The Most Important Fidelity Accounts Beginners Should Understand

Fidelity Investments account types including brokerage, IRA, and Fidelity Go
1. Fidelity Brokerage Account

The standard brokerage account is one of the easiest places to start learning.

Fidelity describes its brokerage account as a multi-feature account that can provide access to stocks, ETFs, options, bonds, mutual funds, and other investments. It currently has no account minimum and allows investing from $1 through fractional shares.

Best For

A brokerage account can make sense for someone who wants:

  • Flexible investing
  • No retirement-account restrictions
  • Stock investing
  • ETF investing
  • Long-term wealth building
  • Access to taxable investments

The major disadvantage is taxation.

Investment income and realized capital gains can create tax obligations.


2. Traditional IRA

A Traditional IRA is designed primarily for retirement investing.

Depending on your circumstances, contributions may qualify for tax deductions, and investments generally grow tax-deferred.

However, withdrawal rules and tax consequences apply.

2026 IRA Contribution Limit

For 2026, the combined IRA contribution limit is:

$7,500 if under age 50

$8,600 if age 50 or older

The additional amount represents the catch-up contribution.

Always check the current IRS rules before making retirement contributions.


3. Roth IRA

A Roth IRA is another important retirement account.

The major attraction is the potential for tax-free qualified withdrawals.

However, eligibility and contribution rules apply.

For 2026, the IRS rules allow eligible individuals to contribute up to the applicable IRA limit, but higher-income taxpayers may face reduced or eliminated direct Roth IRA contribution eligibility. Fidelity’s current 2026 guidance lists income thresholds for Roth IRA eligibility.

Why Beginners Should Understand Roth IRAs

Suppose a young investor contributes consistently for decades.

The combination of:

contributions + investment growth + compounding + tax advantages

can become extremely powerful.

The right choice depends on your income, tax situation, retirement expectations, and eligibility.

But a Roth IRA is not automatically “better” than a Traditional IRA.


4. 401(k)

A 401(k) is generally an employer-sponsored retirement plan.

If your employer offers a 401(k), this deserves attention before opening additional investment accounts.

Why?

Because some employers provide a matching contribution.

For example, if an employer matches part of your contribution, not taking advantage of the available match can mean leaving part of your compensation unused.

Fidelity provides retirement-plan services to employers and employees, although the exact investments and rules available depend on the particular employer plan.


5. Fidelity Go

Not everyone wants to choose investments manually.

That is where a robo-advisor can become useful.

Fidelity Go is Fidelity’s automated investing service.

Fidelity states that Fidelity Go is available to U.S. residents aged 18 and above, and there is no minimum initial investment; once the account reaches $10, Fidelity begins investing according to the selected strategy.

This can be attractive to someone who says:

“I want to invest, but I don’t know which investments to select.”

Instead of manually selecting every security, the investor provides information about their goals and risk preferences, and the automated service manages the portfolio within its framework.


What Can You Buy Through Fidelity?

Fidelity Investments stocks ETFs index funds mutual funds bonds and crypt

This is where things become interesting.

Stocks

You can purchase shares of individual publicly traded companies.

For example, you might buy shares of companies operating in:

  • Technology
  • Healthcare
  • Financial services
  • Energy
  • Consumer products
  • Industrials

But individual stocks carry company-specific risk.

If the company performs poorly, the stock can fall significantly.


ETFs

An ETF is a basket of investments traded on an exchange.

Instead of purchasing 500 individual companies, you can buy an ETF designed to track a broad market index.

This can provide diversification with a single transaction.

Fidelity offers a broad range of ETFs and provides research tools for evaluating them.

Why Beginners Often Prefer ETFs

ETFs can provide:

Diversification

Convenience

Transparency

Low costs

Simple portfolio construction

But not every ETF is diversified.

Some ETFs concentrate heavily on one industry, theme, or asset.

Always investigate what is actually inside an ETF.


Fidelity Index Funds

Index funds attempt to track a particular market index.

One of Fidelity’s most well-known index funds is the Fidelity 500 Index Fund (FXAIX), which seeks to track the S&P 500.

The fund currently has an extremely low expense ratio, and current market reporting places its expense ratio at 0.015%.

This illustrates one reason index investing has become so popular.

Instead of trying to identify the next winning company, the investor obtains exposure to a broad group of companies.

Important

Low fees do not eliminate market risk.

An S&P 500 index fund can still decline substantially during a market downturn.


Fidelity Mutual Funds

Mutual funds pool money from multiple investors and invest according to a defined strategy.

Fidelity has a large mutual-fund lineup covering different objectives.

These can include:

  • U.S. equities
  • International equities
  • Bonds
  • Target-date funds
  • Sector funds
  • Growth funds
  • Income funds
  • Index funds

The important question is not

“Is this a Fidelity fund?”

The important questions are:

“What does this fund own?”

“What does it charge?”

“What is its objective?”

“What risks does it take?”


Fidelity Bonds and CDs

Investing does not have to mean buying stocks.

Fidelity also provides access to fixed-income investments such as bonds and CDs.

These can play a role in portfolios designed around:

  • Income
  • Capital preservation
  • Diversification
  • Retirement planning
  • Lower equity exposure

Fidelity currently lists $1 per bond or CD for secondary-market trading and free online trading for U.S. Treasuries, subject to applicable conditions and rules.


Fidelity Crypto

This is one of the most important modern developments to understand.

Fidelity now offers cryptocurrency exposure through multiple structures.

These include:

Fidelity Crypto

Crypto ETPs

Crypto IRA options

Its current direct crypto offering includes Bitcoin, Ethereum, Fidelity Digital Dollar, Litecoin, and Solana.

Fidelity also offers crypto funds such as FBTC, FETH and FSOL, which provide exposure to Bitcoin, Ether, and Solana through exchange-traded products.

But Crypto Is Different

Fidelity itself warns that cryptocurrency is highly volatile and may become illiquid.

Investors can lose their entire investment.

Crypto should therefore not automatically become the foundation of a beginner’s portfolio.


Fidelity Fractional Shares Explained

Suppose a stock costs $500 per share.

You only have $50.

With fractional investing, you may be able to purchase a portion of that share rather than waiting until you have $500.

Fidelity states that its brokerage account supports fractional shares and allows investors to get started with as little as $1.

This is particularly important for younger investors.

You no longer necessarily need thousands of dollars to begin building a diversified investment habit.


How Much Money Do You Need to Start With Fidelity?

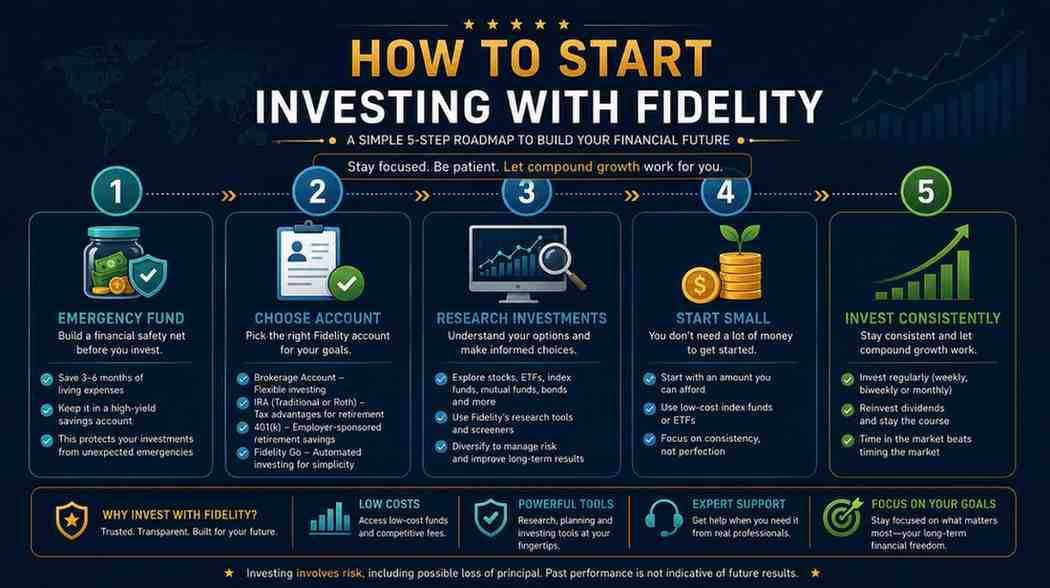
how to start investing with Fidelity Investments step by step

This is one of the most common questions for beginners.

The answer is

You do not necessarily need a large amount.

Fidelity’s standard brokerage account currently has no account minimum, and its fractional-share system allows eligible investors to start investing with $1.

But there is a difference between:

minimum required to start

and

amount needed to achieve a meaningful financial goal.

Starting with $1 teaches you how the platform works.

Building meaningful wealth requires consistent contributions over time.


Fidelity Fees: What Beginners Should Watch

One reason Fidelity attracts investors is its low-cost structure.

Fidelity currently advertises:

  • $0 online commissions for U.S. stocks
  • $0 online commissions for ETFs
  • $0 account fees for its standard brokerage account
  • Zero-expense-ratio index mutual funds

However, “$0 commission” does not mean every possible transaction is free.

Other costs can include:

  • Options contract fees
  • Certain mutual-fund transaction fees
  • Bond/CD charges
  • Advisory fees
  • Fund expense ratios
  • Margin interest
  • Other specialized service fees

Always examine the current fee schedule before investing.


The Difference Between Commission and Expense Ratio

Beginners often confuse these.

Commission

A commission is a charge associated with executing a transaction.

Expense Ratio

An expense ratio represents the annual operating expenses of a fund as a percentage of assets.

Imagine you invest $10,000 in a fund with a 0.10% expense ratio.

That is approximately

$10 per year

before considering changes in the investment value.

The lower the expense ratio, the less of the investment return is consumed by fund expenses, all else equal.

This is one reason low-cost index investing is such a major theme among long-term investors.


What Is the Best Fidelity Investment for a Beginner?

There is no universal “best Fidelity Investments.”

The right investment depends on:

  • Age
  • Income
  • Financial goals
  • Time horizon
  • Risk tolerance
  • Tax situation
  • Existing investments
  • Emergency savings
  • Debt

However, a beginner interested in long-term investing might investigate broad-market index funds or diversified ETFs before jumping into speculative individual stocks.

A Simple Beginner Framework

A hypothetical long-term investor might think in terms of:

Core portfolio

Broad-market diversified investments.

Growth allocation

Potentially higher-growth assets.

Defensive allocation

Bonds or cash-like investments depending on objectives.

Speculative allocation

Only money the investor can genuinely afford to lose.

The exact percentages should not be copied blindly from another investor.


Fidelity Investments and the AI Boom

AI is one of the biggest investment themes influencing U.S. markets in 2026.

Fidelity’s own research describes AI infrastructure spending as a major driver of U.S. economic activity and highlights potential opportunities in semiconductor companies, utilities, energy, and other infrastructure providers.

But there is an important lesson here.

Do Not Confuse a Trend With a Strategy

AI may be a powerful long-term technological transformation.

That does not mean every AI-related stock will rise.

Some companies may:

  • Become market leaders
  • Lose market share
  • Fail to monetize AI
  • Become overvalued
  • Face intense competition

A beginner should therefore investigate the business and valuation, not simply buy something because it contains the word “AI.”


Fidelity Investments and the U.S. Stock Market in 2026

Fidelity’s recent market analysis says U.S. information technology and growth stocks rebounded strongly during the second quarter of 2026, while international equities also showed broad strength.

That creates an important diversification lesson.

You do not necessarily need to put everything into U.S. technology stocks simply because they are performing strongly.

Markets rotate.

Leadership changes.

Economic conditions change.

Interest rates change.

Investor expectations change.

A diversified portfolio is designed around the possibility that you will be wrong about which asset class performs best next.


How a Beginner Could Start Investing With Fidelity

Let’s make this practical.

Step 1: Build an Emergency Fund

Before investing aggressively, consider whether you have sufficient emergency savings.

Do not invest money that you may need next month for rent, food, or an emergency.


Step 2: Eliminate Dangerous High-Interest Debt

Credit card debt with extremely high interest can work against your investment strategy.

Suppose your investment earns 8% over a particular period while your credit card balance costs you 25%.

The mathematics may not favor investing before dealing with the expensive debt.


Step 3: Define Your Goal

Ask:

Why am I investing?

Maybe your goal is:

  • Retirement
  • Buying a home
  • Children’s education
  • Financial independence
  • Long-term wealth
  • Building an investment portfolio

Your goal determines your time horizon.


Step 4: Choose the Correct Account

Consider whether you need:

Brokerage account

Traditional IRA

Roth IRA

401(k)

Fidelity Go

or another specialized account.


Step 5: Choose Your Investment

Do not buy anything until you understand:

  • What it owns
  • How it makes money
  • What it costs
  • How risky it is
  • How diversified it is
  • What your expected holding period is

Step 6: Start Small

You do not need to begin with $10,000.

The objective at the beginning is to build:

knowledge + discipline + consistency.


Step 7: Automate Contributions

Suppose someone invests $100 every month.

They are not attempting to predict every market movement.

They are building a habit.

Over years, the combination of regular contributions and compounding can become meaningful.


What Is Compound Growth?

Suppose you invest money and earn returns.

Those returns remain invested.

Then future returns can potentially be earned on:

your original money + previous investment gains.

That is compounding.

For illustration, if an investor contributed $200 per month and achieved a hypothetical 8% annual return compounded monthly, the account could grow to roughly $117,800 after 20 years.

The investor would have contributed:

$48,000

The remainder would represent investment growth.

But remember:

8% is a hypothetical assumption, not a guaranteed Fidelity return.

Real investment returns vary.


Fidelity Investments vs. Buying Stocks Directly

This is another misconception about Fidelity Investments.

When you use Fidelity, you are not necessarily buying “Fidelity stock.”

You are using Fidelity as the platform through which you can purchase investments.

For example:

Fidelity account

โ†“

Fidelity 500 Index Fund

โ†“

Portfolio of large U.S. companies

Or:

Fidelity account

โ†“

Individual company stock

โ†“

One company

The risk profile is very different.


Fidelity vs. a Bank Account

A bank account and investment account serve different purposes.

Bank/Savings Account

Usually designed for:

  • Cash storage
  • Spending
  • Emergency funds
  • Short-term goals

Investment Account

Designed for:

  • Long-term growth
  • Stocks
  • ETFs
  • Bonds
  • Mutual funds
  • Other investments

Investment values can rise and fall.

Cash accounts are generally much more stable.

Therefore, you should not treat an investment account as though it were a guaranteed savings account.


Can Someone in Africa Open a Fidelity Investments Account?

This is extremely important for FinWireStack’s international readership.

If you currently reside in Africa and do not already have a Fidelity relationship, you generally cannot open a new Fidelity account as an African resident.

Fidelity’s own international-customer guidance states that it does not open accounts for new customers residing outside the United States.

This means an African reader should not attempt to bypass Fidelity’s residency requirements using false information or another person’s U.S. address.

Instead, international investors should investigate brokers and investment platforms that legally accept residents of their country.

This distinction is critical because availability of U.S. investments and availability of a particular U.S. broker are two different things.


Who Is Fidelity Investments Best Suited For?

Fidelity can be particularly attractive for eligible U.S. investors who want:

  • Long-term investing
  • Retirement planning
  • Stocks
  • ETFs
  • Index funds
  • Mutual funds
  • Fractional shares
  • Automated investing
  • Research tools
  • Low-cost investing
  • One financial platform

It can serve both beginners and experienced investors.


Who Should Be Careful?

Fidelity may not be appropriate for someone who:

  • Wants guaranteed returns
  • Does not understand investment risk
  • Wants to day-trade without a strategy
  • Uses excessive margin
  • Buys stocks based entirely on social media hype
  • Does not understand taxes
  • Invests emergency savings
  • Cannot tolerate temporary losses

A reputable platform cannot protect you from a poor investment decision.


Common Fidelity Investing Mistakes Beginners Make

Mistake 1: Buying Whatever Is Trending

A stock appearing repeatedly on TikTok, YouTube, or Google Trends is not automatically a good investment.

Mistake 2: Confusing Fidelity With an Investment

Fidelity is the platform.

The investment is what you purchase through it.

Mistake 3: Investing Without an Emergency Fund

A market downturn can become devastating if you are forced to sell investments to pay an unexpected bill.

Mistake 4: Chasing AI Stocks

AI is a powerful trend, but not every AI company will succeed.

Mistake 5: Ignoring Fees

Small costs can compound over decades.

Mistake 6: Using Margin Too Early

Borrowing money to invest can magnify losses.

Mistake 7: Checking Your Portfolio Every Five Minutes

Long-term investing is generally different from short-term trading.


Fidelity Investments vs. Trading

This distinction deserves special attention for FinWireStack readers.

Investing generally focuses on building wealth over years or decades.

Trading focuses more heavily on shorter-term price movements.

Someone can use Fidelity for both investing and trading, but the mindset is different.

Investing

Goal: Long-term wealth

Typical holding period: Years/decades

Focus: Fundamentals, diversification, asset allocation

Trading

Goal: Profit from price movements

Typical holding period: Minutes to months

Focus: Market behavior, execution, risk management

If you are interested in trading automation, see Algorithmic Trading in 2027.


What About Fidelity Investments Crypto?

Crypto is becoming increasingly integrated into mainstream investment platforms.

Fidelity now allows eligible U.S. customers to access direct cryptocurrency through Fidelity Crypto and crypto exposure through exchange-traded products.

However, crypto should not be confused with traditional diversified investing.

Fidelity explicitly warns that crypto is highly volatile and investors can lose their entire investment.

A beginner should therefore understand the difference between:

Diversified index exposure

and

single-asset cryptocurrency exposure.


A Beginner’s Fidelity Investments Checklist

Before making your first investment, ask yourself:

Financial Preparation

โ˜ Do I have emergency savings?

โ˜ Have I addressed high-interest debt?

โ˜ Do I know my investment objective?

Account Selection

โ˜ Do I need a brokerage account?

โ˜ Should I investigate an IRA?

โ˜ Do I have access to an employer 401(k)?

Investment Selection

โ˜ Do I understand what I am buying?

โ˜ Is it diversified?

โ˜ What does it cost?

โ˜ What are the risks?

Long-Term Plan

โ˜ How much can I invest monthly?

โ˜ How long will I invest?

โ˜ What will I do during a market crash?

โ˜ Will I continue investing consistently?


The 2026 Fidelity Investments Trends Beginners Should Watch

Fidelity Investments trends in 2026: AI ETFs retirement crypto and fractional investing

Based on Fidelity’s current research and product direction, several themes deserve attention.

AI Infrastructure

AI is expanding demand for computing power, data centers, semiconductors, and electricity infrastructure. Fidelity identifies these areas as potential investment opportunities while also emphasizing the importance of valuation and risk.

Low-Cost Index Investing

Index funds and ETFs remain central to many long-term portfolios.

Fractional Investing

The ability to invest with smaller amounts makes market access easier for beginners.

Automated Investing

Robo-advisors such as Fidelity Go can help investors who prefer an automated approach.

Crypto Integration

Fidelity’s expansion into direct crypto and crypto ETPs shows how digital assets are increasingly being integrated into mainstream investment platforms.

Retirement Tax Planning

IRA contribution limits and tax rules remain important considerations for American investors.


Is Fidelity Investments Safe?

Fidelity is an established U.S. financial-services company, but “safe platform” does not mean “your investments cannot lose money.”

Your investment can decline.

A stock can go to zero.

An ETF can fall.

A cryptocurrency can experience extreme losses.

Safety therefore has two dimensions:

Platform and custody protections

versus

Investment risk.

Never confuse the two.

Fidelity Investments’ brokerage entities identify their applicable regulatory and SIPC membership information, but investors should understand exactly which product they own and what protections apply to it.

This becomes particularly important with cryptocurrency because Fidelity states that crypto investments do not receive the same regulatory protections applicable to registered securities.


The Beginner’s Best Way to Think About Fidelity Investments

Don’t ask:

“Which Fidelity Investments will make me rich?”

Ask:

“Which Fidelity Investments account and investment structure best fit my financial goal, risk tolerance, and time horizon?”

That single change in mindset can dramatically improve the quality of your investment decisions.


Final Takeaway

Fidelity Investments is not a single investment.

It is a large financial-services platform that gives eligible investors access to a wide range of accounts and investments.

A beginner can use Fidelity Investments to access:

  • Stocks
  • ETFs
  • Index funds
  • Mutual funds
  • Bonds
  • CDs
  • Retirement accounts
  • Fractional shares
  • Automated investing
  • Cryptocurrency

Its current direction also reflects some of the biggest themes shaping U.S. investing in 2026: AI, technology, low-cost investing, automation, retirement planning, and digital assets.

But the platform does not determine whether you make money.

Your financial plan, strategy, risk management, time horizon, and behavior matter far more.

For a beginner, the most sensible progression in Fidelity Investments is:

Learn โ†’ Build an emergency fund โ†’ Understand accounts โ†’ Choose diversified investments โ†’ Invest consistently โ†’ Control costs โ†’ Avoid unnecessary speculation โ†’ Review periodically.

And if you are outside the United States, remember the crucial eligibility issue: Fidelity currently says it does not open accounts for new customers who reside outside the U.S.

So for a Kenyan investor, the educational lesson is still highly valuableโ€”but the practical next step is to identify a regulated investment platform that legally accepts Kenyan residents rather than attempting to circumvent Fidelity’s eligibility requirements.


Frequently Asked Questions on Fidelity Investments.

Is Fidelity Investments a bank?

Fidelity Investments is primarily a financial services and investment company. It provides brokerage, retirement, investment-management, cash-management, and other financial products.

Is Fidelity good for beginners?

It can be. Fidelity provides educational resources, fractional shares, low-cost investment options, and both self-directed and automated investing services.

How much money do I need to start investing with Fidelity Investments?

Fidelity’s standard brokerage account currently has no account minimum, and eligible investors can use fractional shares to invest with as little as $1.

Can I buy ETFs through Fidelity?

Yes. Fidelity provides access to ETFs and offers its own ETF lineup as well as other investment choices.

Can I buy Bitcoin through Fidelity?

Eligible U.S. customers can access Bitcoin and other cryptocurrencies through Fidelity Crypto. Fidelity also offers crypto ETPs through brokerage accounts.

Can Africans open an account in Fidelity Investments?

Fidelity states that it does not open accounts for new customers residing outside the United States.

What is the difference between Fidelity and an ETF?

Fidelity is a financial-services platform. An ETF is an investment product that you can potentially purchase through Fidelity.

What is FXAIX?

FXAIX is the Fidelity 500 Index Fund, which seeks to track the S&P 500. It is one of Fidelity’s best-known index funds.

Does Fidelity guarantee investment returns?

No. Investments can lose value, and past performance does not guarantee future results.


Recommended Official Resources on Fidelity Investments

Fidelity Investments: Fidelity Investments official website

Fidelity Brokerage Account: The Fidelity Account

Fidelity Investment Accounts: Fidelity account and product directory

Fidelity Fees: Fidelity pricing and fees

Fidelity ETFs: Investing in ETFs at Fidelity

IRS: 2026 IRA and retirement contribution information


Learn more about investments here:

Algorithmic Trading in 2027 in Relation to Fidelity Investments.

AI Trading Bots: Real vs Scams in Relation to Fidelity Investments.

AI vs Human Traders 2030 in Relation to Fidelity Investments.

Copy Trading in 2027 in Relation to Fidelity Investments.

AI Investment Platforms in 2027 in Relation to Fidelity Investments.

How to Start Stock Investing in 2026: Warren Buffett’s Simple Strategy

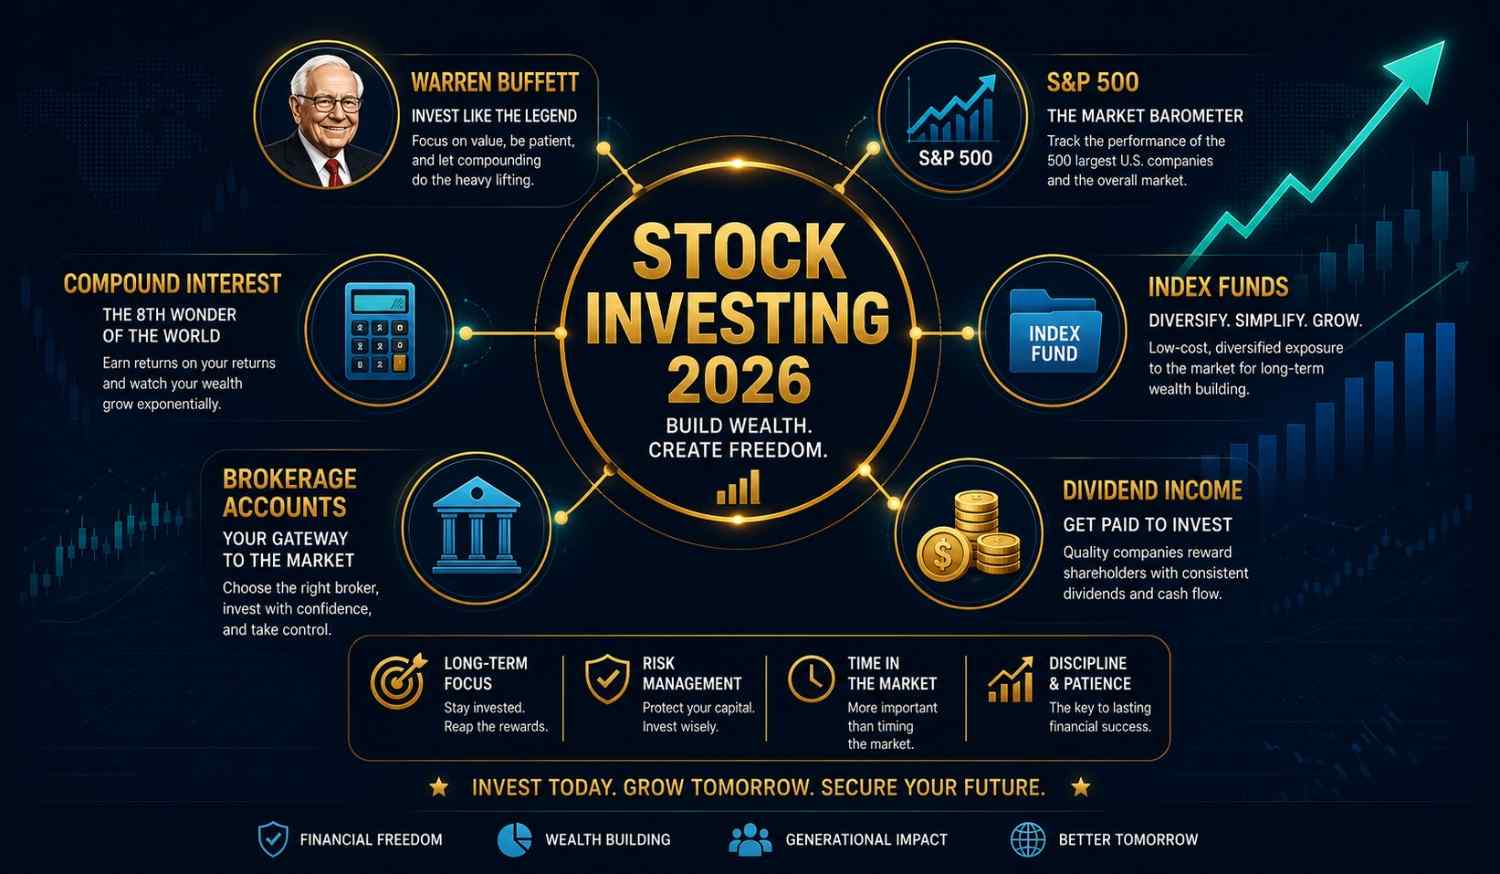
Stock investing for beginners 2026 featured image showing Warren Buffett S&P 500 index funds and compound interest strategy for building wealth

Stock investing for beginners in 2026ย starts with a simple truth that most people overlook: you don’t need to be a Wall Street expert to build wealth. In fact, the world’s most successful investor, Warren Buffett, has repeatedly said that the best strategy for most people is remarkably simple.

The year 2026 presents a unique moment for new investors. The S&P 500 has delivered a 1,770% return over the past 30 years, turning $10,000 into $187,000. Meanwhile, global markets are adjusting to new realitiesโ€”from AI’s transformative impact to shifting central bank policiesโ€”creating both uncertainty and opportunity.

This comprehensive guide will teach youย stock investing for beginners in 2026ย from the ground up. You will learn:

  • Why stocks are the most powerful wealth-building tool available
  • Warren Buffett’s simple, proven investment philosophy
  • How to understand the stock market without getting overwhelmed
  • Step-by-step instructions for opening a brokerage account
  • Which index funds to buy and how to automate your investments
  • The psychology of successful long-term investing

By the end, you will understand stock investing for beginners 2026 well enough to take action with confidence.


Stock investing for beginners 2026 overview showing Warren Buffett S&P 500 index funds and compound growth strategies for building wealth

Stock investing for beginners 2026 โ€” understanding the basics of building long-term wealth


Why Stocks Are the Ultimate Wealth-Building Tool

Understanding stock investing for beginners 2026 starts with one powerful concept: compound interest. Albert Einstein reportedly called it the eighth wonder of the world. Here is why.

The Power of Compound Interest

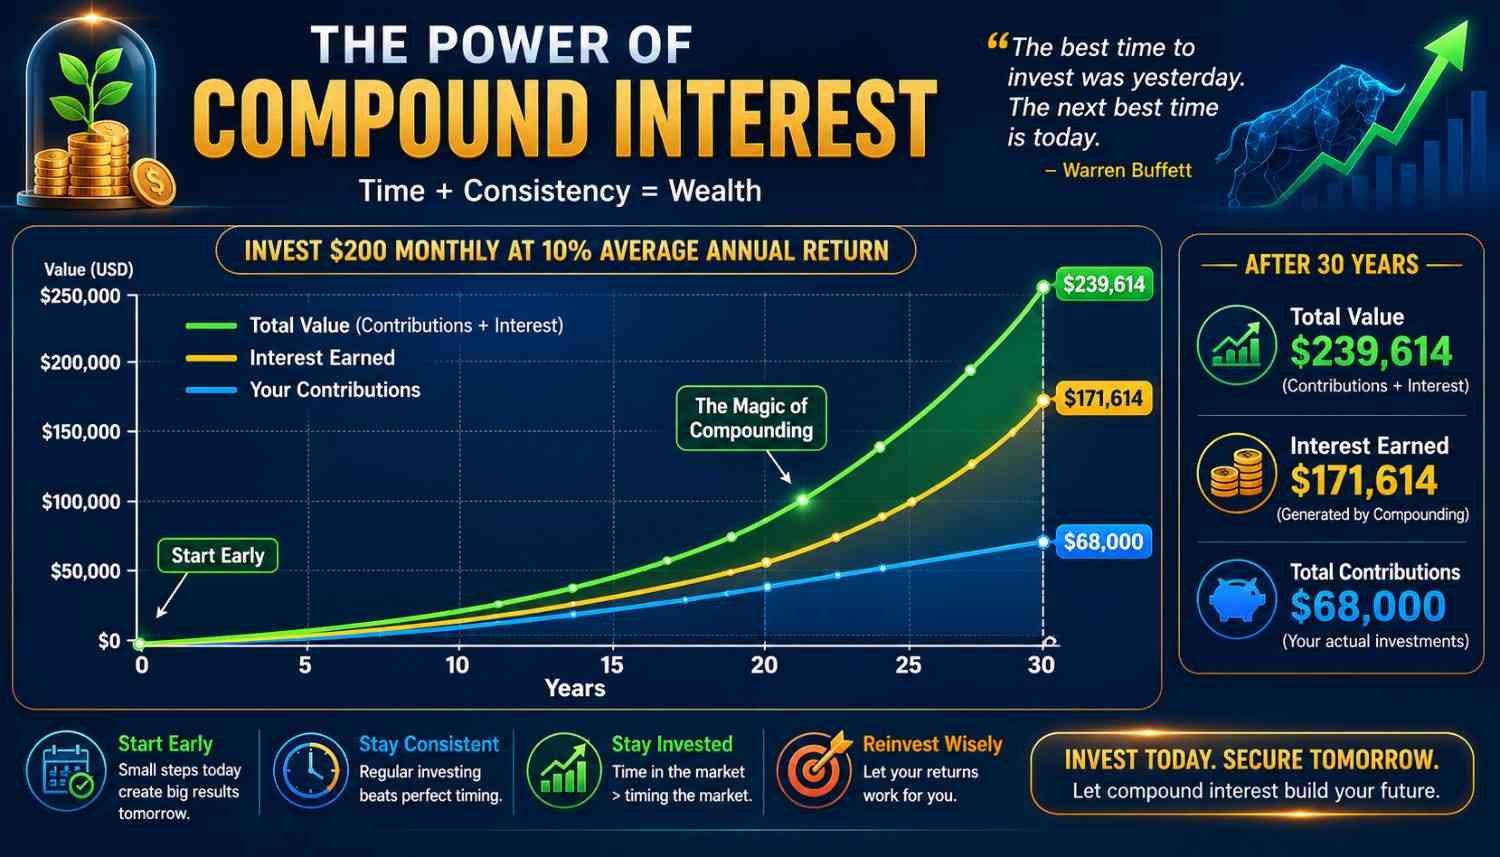
Imagine you invest $100 per month for 30 years. At a 10% average annual return (the historical average of the S&P 500), here is what happens:

Investment PeriodMonthly ContributionTotal ContributionsEstimated ValueGrowth from Interest
10 Years$100$12,000$20,655$8,655
20 Years$100$24,000$75,936$51,936
30 Years$100$36,000$226,049$190,049

๐ŸŽฏ Real-World Example:ย A 25-year-old who invests $500 per month in an S&P 500 index fund could accumulate over $1 million by age 65, assuming a 10% historical average return. This is the power ofย stock investing for beginners in 2026โ€”small, consistent actions lead to massive results.

Why Stocks Outperform Other Assets

Asset ClassHistorical Average ReturnRisk Level
Stocks (S&P 500)9-10%Moderate-High
Bonds4-5%Low-Moderate
Savings Accounts0.5-3%Very Low
Real Estate4-6%Moderate
Gold2-4%Moderate

๐Ÿ”ด Red Highlight: Inflation is the silent wealth killer. If you keep all your money in a savings account earning 1% while inflation runs at 3%, you are losing purchasing power every year. Stocks are one of the few assets that have consistently outpaced inflation over long periods.


Stock investing for beginners 2026 compound interest chart showing how $100 monthly contributions grow to $226,000 over 30 years

The power of compound interestโ€”why starting early is the secret to stock investing for beginners 2026


Warren Buffett’s Simple Investment Philosophy

When learningย stock investing for beginners in 2026, there is no better teacher than Warren Buffett. The CEO of Berkshire Hathaway is one of the wealthiest people in the world, and his advice for average investors is remarkably simple.

Buffett’s Core Advice

“The best thing to do is buy a low-cost S&P 500 index fund. By regularly investing in an index fund, the know-nothing investor can actually outperform most investment professionals.” โ€” Warren Buffett

Why This Works:

  1. Low Cost:ย Index funds have expense ratios as low as 0.03%, meaning you keep almost all of your returns
  2. Instant Diversification:ย The S&P 500 gives you exposure to 500 of America’s largest companies
  3. Proven Track Record:ย The S&P 500 has returned approximately 10% annually over the long term
  4. No Stock Picking Required:ย You don’t need to research individual companies
  5. Less Emotion:ย You buy the whole market, not a single stock

Buffett’s $1 Million Bet

In 2008, Buffett bet $1 million that a low-cost S&P 500 index fund would outperform a collection of hedge funds over 10 years. By 2018, the index fund had returned 125%, while the hedge funds averaged just 36%. The index fund won by a landslide.

๐ŸŸฆ Blue Highlight: This bet proves that for most people, stock investing for beginners 2026 is not about finding the next Apple or Tesla. It is about owning the entire market and letting compound interest do the work.


Stock investing for beginners 2026 Warren Buffett strategy showing S&P 500 index funds low-cost investing and the million-dollar bet for beginners

Warren Buffett’s simple stock investing strategy for beginners


Understanding the Stock Market

Before diving intoย stock investing for beginners in 2026, it helps to understand what the stock market is.

What Is a Stock?

A stock represents ownership in a company. When you buy a share of stock, you are buying a tiny piece of that company. If the company grows and becomes more profitable, the value of your share typically increases.

What Is the Stock Market?

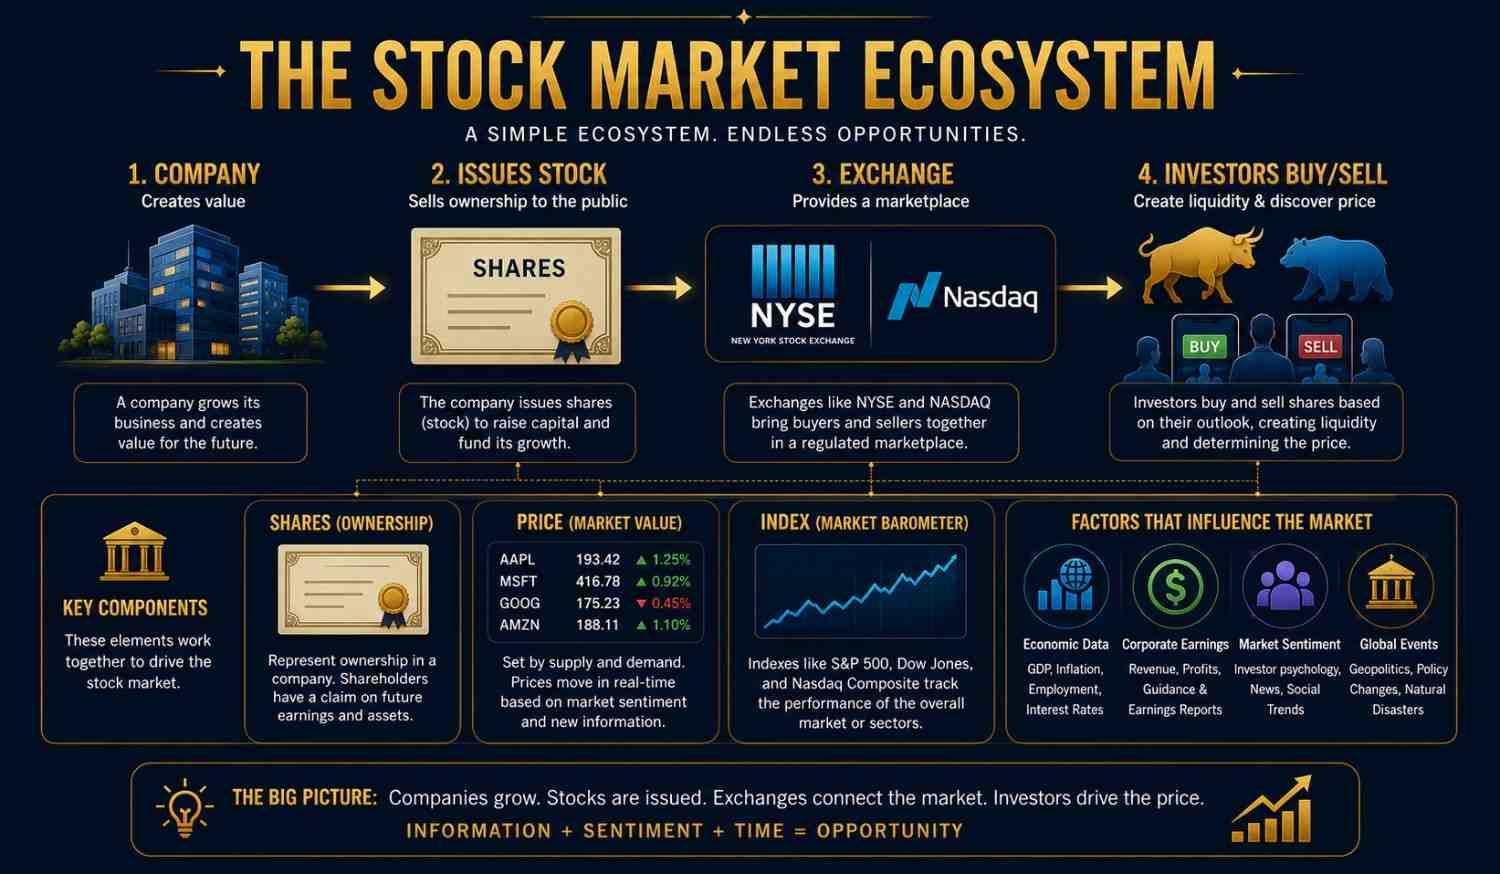
The stock market is where buyers and sellers trade stocks. The most famous stock market is the New York Stock Exchange (NYSE), which has been around since 1792. It operates Monday through Friday, 9:30 AM to 4:00 PM Eastern Time.

What Is an Index?

An index is a collection of stocks grouped together to represent a specific segment of the market. Think of it like a basket of stocks.

IndexWhat It TracksNumber of Companies
S&P 500500 largest U.S. companies500
Dow Jones30 large, established companies30
NASDAQTechnology-focused companies3,000+
Russell 2000Smaller companies2,000

What Is an Index Fund?

An index fund is a type of mutual fund or ETF that tracks a specific index. When you buy an S&P 500 index fund, your money is spread across all 500 companies in that index. This gives you instant diversification.

What Moves Stock Prices?

Stock prices change based on supply and demand. If more people want to buy a stock than sell it, the price goes up. If more people want to sell than buy, the price goes down. Factors that influence supply and demand include:

  • Company Earnings:ย If a company reports strong profits, investors want to buy
  • Economic Data:ย Strong jobs reports or GDP growth often boost markets
  • Interest Rates:ย When rates are low, stocks become more attractive
  • Investor Sentiment:ย Fear and greed drive prices in the short term

Stock investing for beginners 2026 how the stock market works showing stock exchanges, indexes, and price drivers for beginners

How the stock market worksโ€”essential knowledge for stock investing for beginners 2026


How to Start Investing: A Step-by-Step Guide

Here is a simple, actionable plan forย stock investing for beginners in 2026.

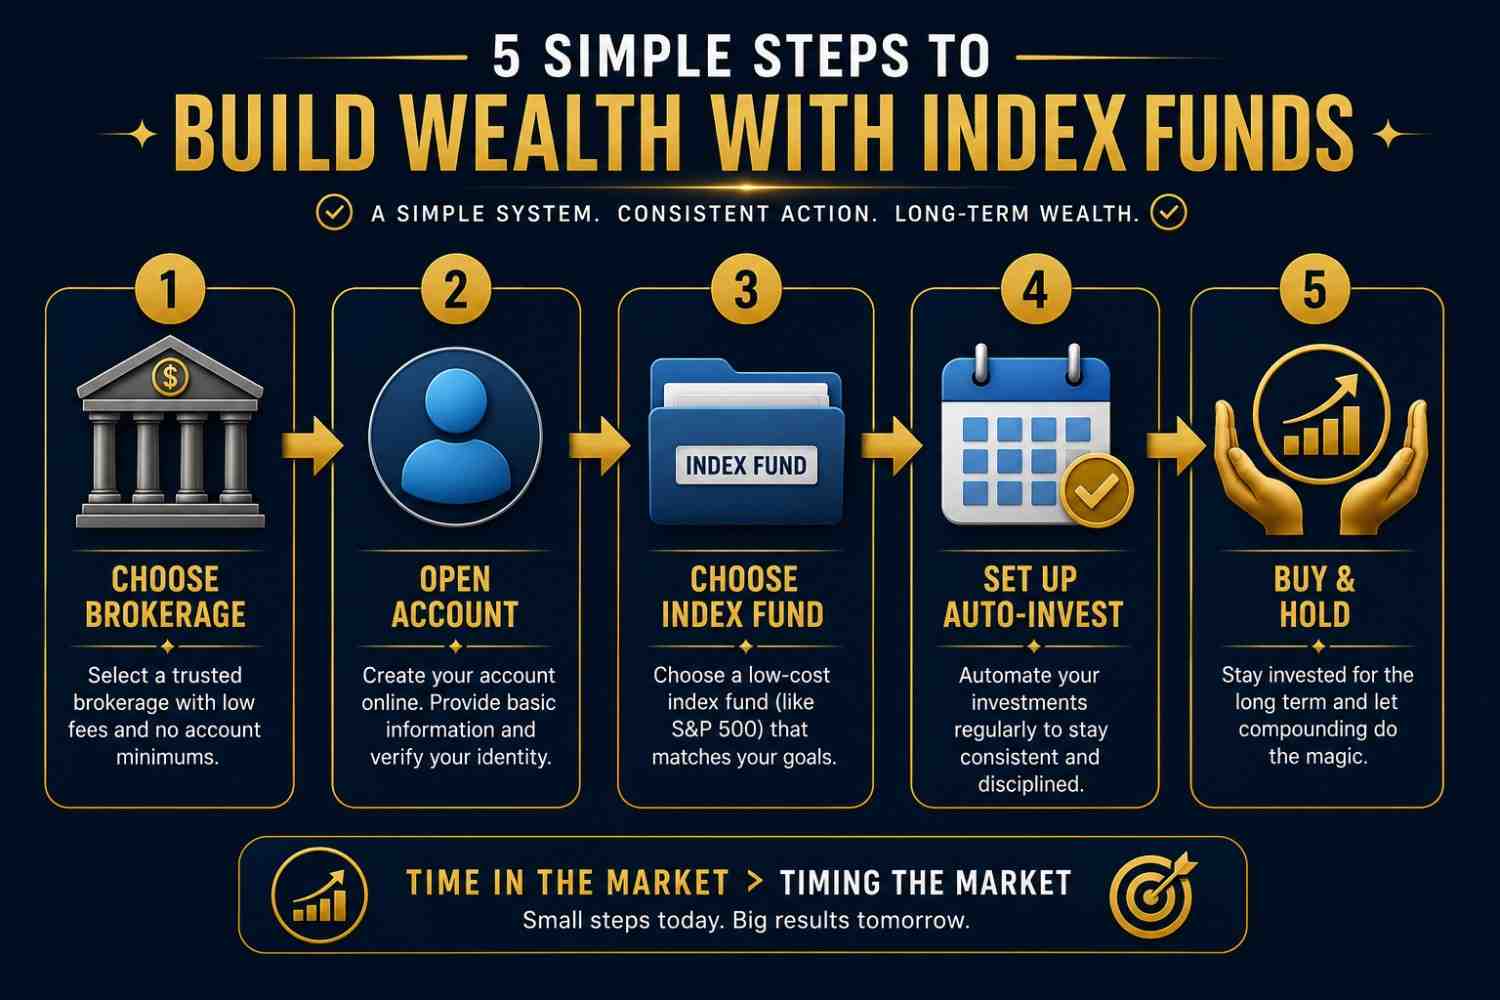
Step 1: Choose a Brokerage Account

A brokerage account is where you buy and sell stocks and ETFs. Look for a brokerage that offers:

  • Low or $0 trading commissions
  • Low expense ratios on index funds
  • User-friendly platform
  • No account minimums

Top Brokerage Options for Beginners:

BrokerageMinimum DepositTrading FeesBest For
Vanguard$0$0Low-cost index funds
Fidelity$0$0Comprehensive platform
Charles Schwab$0$0Excellent customer service
Robinhood$0$0Simple mobile interface
M1 Finance$0$0Automated investing

Step 2: Open Your Account

Opening a brokerage account is similar to opening a bank account. You will need:

  • Personal information (name, address, Social Security number)
  • Employment and income details
  • Investment goals (retirement, general investing)
  • Bank account information for funding

Most accounts can be opened in under 15 minutes.

Step 3: Choose Your Investment

Forย stock investing for beginners in 2026, the best choice is a low-cost S&P 500 index fund. Here are the top options:

Fund NameTickerExpense RatioMinimum Investment
Vanguard S&P 500 ETFVOO0.03%$0 (one share)
SPDR S&P 500 ETFSPY0.09%$0 (one share)
iShares Core S&P 500 ETFIVV0.03%$0 (one share)
Vanguard S&P 500 Mutual FundVFIAX0.04%$3,000
Fidelity 500 Index FundFXAIX0.015%$0

๐Ÿ’ก Pro Tip: For beginners, ETFs (Exchange-Traded Funds) like VOO are excellent because they have no minimum investment and can be bought and sold like stocks.

Step 4: Set Up Automatic Contributions

The key to successfulย stock investing for beginners in 2026ย is consistency. Set up automatic transfers from your checking account to your brokerage account each month.

Example:

  • Monthly contribution: $100-$500
  • Investment: VOO (Vanguard S&P 500 ETF)
  • Frequency: Monthly, automatically

Why It Works: This is called dollar-cost averaging. When the market is down, your money buys more shares. When it is up, it buys fewer. Over time, this averages out your cost.

Step 5: Adopt the Buy-and-Hold Mindset

The hardest part ofย stock investing for beginners in 2026ย is not the mechanicsโ€”it is the psychology. When the market drops 20%, the natural instinct is to sell. But history shows that staying the course is the winning strategy.

๐Ÿ’ก Pro Tip: If you are investing for long-term goals (retirement, down payment, college), ignore the short-term noise. The stock market has always recovered from every downturn in history.


Stock investing for beginners 2026 step by step guide showing brokerage account selection index fund choices and automatic investing setup

How to start stock investing in 2026 โ€” a step-by-step guide for beginners


Investment Options Beyond the S&P 500

While the S&P 500 is the best starting point, there are other index funds worth considering as you grow your portfolio.

Investment OptionTickerExpense RatioWhat It Tracks
Total Stock Market FundVTI0.03%Entire U.S. stock market
Total World Stock FundVT0.07%Global stock market
S&P 500 FundVOO0.03%500 largest U.S. companies
Growth Index FundVOOG0.10%Faster-growing S&P 500 companies
Dividend Appreciation FundVIG0.06%Companies with growing dividends

How to Allocate Your Investments

Forย stock investing for beginners in 2026, a simple approach works best:

Age GroupStocksBondsCash
20s and 30s90-100%0-10%0%
40s and 50s70-80%20-30%0%
Near Retirement (60+)50-60%40-50%0-5%

๐ŸŽฏ Real-World Example:ย A 30-year-old startingย stock investing for beginners in 2026ย with $200/month in VOO could have approximately $500,000 by age 60. If they wait until 40 to start, that same $200/month grows to about $180,000. Starting ten years earlier could result in over $300,000 more. This is the power of compound interest.


Common Mistakes and How to Avoid Them

MistakeWhy It’s a ProblemHow to Fix
Trying to Time the MarketMissing the best days can destroy returnsStay invested consistently
Panic SellingLocks in losses and misses recoveriesIgnore short-term volatility
Not DiversifyingConcentrated risk in one stock or sectorUse index funds
High FeesExpense ratios and trading fees reduce returnsChoose low-cost index funds
Chasing “Hot” StocksBuying high and selling lowStick to index funds
No PlanEmotional decisions lead to mistakesSet up automatic investing

Conclusion: Your Stock Investing Journey Starts Here

Stock investing for beginners 2026 is not about getting rich overnight. It is about building wealth consistently over time through the power of compound interest and the simplicity of index funds.

Key Takeaways:

  1. Start nowโ€”The most important factor is time in the market
  2. Buy a low-cost S&P 500 index fundย โ€” Warren Buffett’s proven strategy
  3. Invest consistentlyย โ€” Set up automatic contributions
  4. Ignore short-term noiseโ€”focus on the long-term
  5. Stay investedโ€”Don’t try to time the market
  6. Keep it simpleโ€”You don’t need complex strategies
  7. Trust the processโ€”The market has always recovered

๐ŸŽฏ Final Thought:ย Like many people, you might feel that investing in stocks is complicated or risky. But the truth is thatย stock investing for beginners in 2026ย is simpler than ever. By following Warren Buffett’s advice and buying a low-cost index fund, you can participate in the growth of America’s most successful companies. The key is to startโ€”and to stay invested.


FAQ

1. How do I start stock investing with little money?

You can start with as little as $10-$100 using fractional shares. Most brokers now offer fractional share investing, allowing you to buy a portion of a share. Opening a brokerage account is free, and there is no minimum balance with most platforms. The most important factor is consistency, not the initial amount.

2. What is the best stock for beginners?

The best “stock” for beginners is actually an S&P 500 index fund like VOO. It gives you exposure to 500 of America’s largest companies with a single purchase, providing instant diversification at a very low cost (expense ratio of just 0.03%). This follows Warren Buffett’s famous advice for beginner investors.

3. How much money do I need to start stock investing?

You can start with $10-$100. Many brokers have no minimum deposit requirements and allow fractional share purchases. The most important factor is consistency, not the initial amount. Investing $100 monthly over 30 years at 10% average return grows to approximately $226,000.

4. What is the difference between stocks and index funds?

A stock represents ownership in a single company. An index fund owns many stocks at once. For example, VOO owns the 500 stocks in the S&P 500. Index funds are safer and simpler for beginners because they provide instant diversification and lower risk compared to individual stocks.

5. What is dollar-cost averaging?

Dollar-cost averaging means investing a fixed amount regularly, regardless of the price. This averages out your costs over time and removes the need to “time” the market. It is the standard strategy for most long-term investors and helps reduce the emotional stress of investing.

6. Is it safe to invest in stocks?

Stock investing carries risk, but over long periods (10+ years), the S&P 500 has never lost money. The key is to stay invested through market cycles and not panic sell during downturns. Since 1926, the S&P 500 has delivered positive returns in approximately 73% of all years.

7. How often should I check my investments?

For long-term investors, checking more than quarterly is unnecessary and can lead to emotional decisions. Checking weekly can cause unnecessary stress. The best approach is to set up automatic contributions and review your account less frequentlyโ€”ideally once per quarter or annually.

8. What is Warren Buffett’s 90/10 rule?

Warren Buffett has advised that 90% of your portfolio should be in a low-cost S&P 500 index fund and 10% in short-term government bonds. This simple allocation has outperformed most actively managed funds over the long term and is considered one of the safest approaches to investing.

9. What is the difference between ETFs and mutual funds?

ETFs (Exchange-Traded Funds) trade like stocks throughout the day and typically have lower expense ratios. Mutual funds trade once per day after market close and may have higher minimum investments. For beginners, ETFs like VOO are often the better choice due to their low costs and flexibility.

10. What is a Roth IRA, and should I use one?

A Roth IRA is a tax-advantaged retirement account where you contribute after-tax money and withdraw tax-free in retirement. For 2026, the contribution limit is $7,000 ($8,000 if age 50+). It is an excellent vehicle for long-term stock investing because all growth is tax-free.

11. How do I choose between VOO, SPY, and IVV?

All three track the S&P 500. VOO has the lowest expense ratio (0.03%) and is excellent for long-term buy-and-hold investors. SPY has a slightly higher expense ratio (0.09%) but is more liquid for active traders. IVV also has a 0.03% expense ratio. For most beginners, VOO is the best choice.

12. What happens if the stock market crashes?

Market crashes are normal and happen every 5-10 years on average. Since 1926, the S&P 500 has experienced 25+ declines of 10% or more. The market has always recovered and gone on to make new highs. The worst thing you can do is panic sell. Instead, continue your automatic investmentsโ€”you will be buying shares at a discount.


Further Reading

To deepen your understanding of financial markets and trading, explore these additional resources from Finwirestack:


External Resources (DoFollow Links)


Disclaimer: Investing in stocks involves risk. Past performance does not guarantee future results. The information provided in this article is for educational purposes only and does not constitute financial advice. Always consult a qualified financial advisor before making investment decisions.