Category Cryptocurrency Education

The Fed Just Raised Rates for the First Time in 3 Years: What It Means for Your Mortgage, Savings, and Crypto in 2026
Fed rate hike in 2026, affecting mortgage savings and financial markets

Updated: September 25, 2026

The Fed rate hike in the 2026 story has once again changed the financial landscape.

On September 16, 2026, the Federal Open Market Committee raised the federal funds target range by 25 basis points, from 3.50%-3.75% to 3.75%-4.00%.

The decision was unanimous, 12-0, and marked the Federal Reserve’s first rate increase since July 2023. The Fed said inflation remains elevated and that the move would support a timelier return toward its 2% inflation goal

For households, however, the important question isn’t what happened inside the Federal Reserve building.

It’s what happens to your mortgage, savings account, credit card, investment portfolio, retirement plan, and crypto holdings.

The answer isn’t as simple as “higher rates are bad.”

You may also be intrested in:
Forex MT5 Viper Strategy

Forex MT5 Viper Strategy For MT 5 Platform
Software

Forex MT5 Viper Strategy

Daytrading Bootcamp – Otsunabhรคngig traden lernen

Forex MT5 Viper Strategy

Intelligent Cryptocurrency VIP
Member area and video courses

A rate increase can make borrowing more expensive while simultaneously improving the returns available on cash and short-term fixed-income investments. It can pressure risk assets while potentially benefiting savers. And for homeowners, the effect depends heavily on whether you already have a fixed-rate mortgage or are shopping for a new loan.

This guide breaks down the Fed’s rate-hike decision in 2026 from a personal-finance perspective and explains what the latest policy signals could mean through the rest of the year.


What the Fed Just Did and Why It Matters

The Federal Reserve raised its benchmark interest-rate target by 25 basis points, placing the federal funds rate range at 3.75%-4.00%.

One basis point equals one-hundredth of a percentage point, so 25 basis points equals 0.25 percentage points.

That might sound small.

For a household carrying hundreds of thousands of dollars of debt, however, even relatively small changes in borrowing costs can become meaningful.

Why did the Fed raise rates?

The Fed’s official statement pointed to elevated inflation.

Economic activity was described as expanding at a solid pace, domestic spending remained resilient, productivity growth was strong, and capital investment was robust. At the same time, inflation remained elevated.

Fed Chair Kevin Warsh was even more direct during his September 16 press conference.

He said:

“The plain fact is that inflation is too high and has been for too long.”

Warsh also said the summer inflation readings did not show enough evidence that underlying trends had meaningfully improved.

That tells you something important about the Fed rate hike in 2026.

This wasn’t simply a mechanical adjustment.

It was a policy signal that the Federal Reserve is willing to keep monetary conditions restrictive when inflation remains above its objective.

Is this another 2022-style rate-hiking cycle?

Not necessarily.

The current environment is different from the aggressive tightening campaign that began in 2022.

The Fed raised rates repeatedly in 2022 and 2023 as it attempted to bring inflation down from historically elevated levels. The September 2026 increase came after the federal funds rate had been held at lower levels and after the Fed had spent a period assessing inflation, economic growth, and labor-market conditions.
Forex MT5 Viper Strategy

Bitcoin Breakthrough System

Forex MT5 Viper Strategy

Daytrading Bootcamp.

Forex MT5 Viper Strategy

Make Money Easy with The Unfair Advantage Playbook

The latest move can therefore be seen as a renewed tightening step, rather than simply continuing the 2022-2023 sequence.

That distinction matters for consumers.

A single 25-basis-point increase doesn’t automatically mean that borrowing costs will surge everywhere.

But it does mean that households should take the possibility of higher-for-longer interest rates seriously.

What should you do with that information?

Start with the part of your financial life that responds most quickly to interest rates.

For many households, that means

  • Credit card balances
  • Variable-rate loans
  • HELOCs
  • New mortgages
  • Savings accounts
  • Money-market products
  • Short-term bonds
  • Cash reserves

If you’re tracking the next Federal Reserve meeting, don’t rely on headlines alone.

CME FedWatch translates 30-Day Fed Funds futures prices into market-implied probabilities for upcoming FOMC decisions. It is useful for understanding what interest-rate traders are pricingโ€”not for predicting what the Fed must do.


Mortgage Rates Just Hit 7%

If you’re shopping for a house, the Fed rate hike in 2026 mattersโ€”but there is an important distinction.

The Federal Reserve does not directly set the 30-year mortgage rate.

Mortgage rates are influenced by Treasury yields, mortgage-backed securities, inflation expectations, economic growth, lender pricing, and other market factors.

Nevertheless, Federal Reserve policy can influence the broader interest-rate environment.

And right now, mortgage borrowers are dealing with rates above 7%.

Freddie Mac reported that the average 30-year fixed mortgage rate reached 7.03% on September 24, 2026, up from 6.95% one week earlier and 6.30% a year earlier. The average 15-year fixed rate was 6.42%.
Higher mortgage rates affecting U.S. homebuyers after the 2026 Fed rate hike

What does a 7% mortgage mean for a new buyer?

Consider a simplified example.

Suppose you borrow $400,000 for 30 years.

At 7.00%, the principal-and-interest payment is approximately $2,661 per month, before taxes, insurance, mortgage insurance, and other costs.

At 6.00%, the equivalent payment would be approximately $2,398 per month.

That’s a difference of roughly $263 every month, or more than $3,100 per year.

The difference becomes much larger over the life of a mortgage.

This is why even seemingly modest changes in mortgage rates can materially affect affordability.

Existing homeowners have a different problem.

If you already have a fixed-rate mortgage, the September Fed decision doesn’t automatically change your mortgage payment.

A fixed-rate mortgage generally remains fixed according to the terms of the loan.

That’s an important distinction.

If you locked in a favorable rate several years ago, your biggest financial decision may not be whether to react to the Fed at all.

It may be whether you should leave your existing mortgage alone.

What about adjustable-rate mortgages and HELOCs?

This is where the Fed rate increase impact can be more immediate.

Variable-rate debt can respond to changes in benchmark rates.

HELOCs, for example, commonly use variable rates. When the underlying benchmark rises, the cost of carrying the balance can rise as well.

If you have a large HELOC balance, review:

  • Current interest rate
  • Margin above the benchmark
  • Remaining draw period
  • Repayment period
  • Whether a fixed-rate conversion is available
  • Early termination or conversion fees

Don’t automatically refinance simply because the Fed raised rates.

Calculate the break-even point.

Should you refinance after the Fed rate hike?

Not necessarily.

A refinance only makes sense when the expected savings justify:

  • Closing costs
  • Origination fees
  • Appraisal costs
  • Title expenses
  • Potential points
  • The amount of time you expect to remain in the home

For some borrowers, refinancing into a lower rate can make sense.

For others, waiting or keeping the existing mortgage may be financially preferable.

Your credit profile also matters.

Experian currently offers consumers access to a free FICO Score based on Experian data, and checking your own score does not lower your credit score. Experian also notes that lenders may use different scoring models.

That last point is important: your Experian score is not necessarily the exact score a mortgage lender will use.

Mortgage checklist for 2026

Before applying for a mortgage or refinance:

  • Check your credit reports for errors.
  • Check your credit score.
  • Calculate your debt-to-income ratio.
  • Compare multiple lenders.
  • Compare APR, not just the headline interest rate.
  • Ask about points and lender credits.
  • Calculate your break-even period.
  • Keep adequate cash reserves after closing.
  • Don’t assume rates will automatically fall soon.

Freddie Mac’s mortgage-rate data should be treated as a national benchmark, not a personal rate quote. Actual offers vary according to borrower characteristics, property, loan type, lender, and market conditions.


Savings Accounts Are Finally Paying Again

There is another side to the Fed rate hike 2026 story.

Savers can benefit.

When short-term interest rates rise, banks and other financial institutions generally have more room to offer attractive yields on deposits and money-market products.

That doesn’t mean every bank immediately passes the increase to customers.

In fact, the difference between a competitive online savings account and a low-yield traditional bank account can be significant.

Why online savings accounts often pay more

Large traditional banks have enormous branch networks and established customer bases.

They don’t always need to compete aggressively for deposits.

Online banks have a different cost structure and frequently compete for customers through deposit rates.

That can create a significant gap.

Bankrate’s September 2026 survey showed leading high-yield savings accounts offering rates as high as 4.20% APY, compared with a national average of around 0.64%.
Investor comparing high-yield savings accounts after the 2026 Fed rate hike

Rates can change, however.

A 4.20% APY today isn’t necessarily a 4.20% APY six months from now.

How much difference does the rate make?

Imagine you keep $25,000 in cash.

At 0.64%, the annual interest would be approximately $160 before taxes.

At 4.20%, it would be approximately $1,050.

That’s a difference of roughly $890 per year.

The calculation is simplified and assumes the rates remain unchanged for a full year, but it illustrates why shopping for deposit rates matters.

Should you move your emergency fund?

Possiblyโ€”but safety and liquidity should come before yield.

An emergency fund is not the place to chase speculative returns.

For U.S. savers, check whether a bank is FDIC-insured or whether a credit union is federally insured by the NCUA, and understand applicable coverage limits.

Don’t assume every financial product marketed as a “cash alternative” has the same protection as a conventional insured deposit.

Compare high-yield savings rates.

Bankrate’s current comparison shows why shopping around can matter. Its September 24 data listed a top savings APY of 4.20%, while the national average was 0.64%.

When comparing accounts, don’t look only at APY.

Check:

  • Minimum opening deposit
  • Minimum balance
  • Monthly fees
  • Withdrawal restrictions
  • Transfer limits
  • FDIC/NCUA insurance
  • Promotional-rate expiration
  • Requirements for earning the advertised APY

What about the 10-year Treasury real yield?

Real yields are another important signal.

The U.S. Treasury publishes daily real-yield data based on Treasury Inflation-Protected Securities, or TIPS. These yields represent market pricing for inflation-protected government debt and can provide useful information about the real return investors demand.

The 2026 real-yield environment has been elevated compared with much of the post-financial-crisis period.

But be careful with headlines claiming that a specific real yield is “the highest since 2006” unless the exact date and Treasury series are specified.

The Treasury publishes multiple maturities and series, and a comparison must use the same maturity and methodology.

For FinWireStack readers, the broader takeaway is more useful:

Real yields are high enough to matter to savers and fixed-income investors again.


How This Rate Hike Affects Crypto and Forex Markets

Crypto investors often focus heavily on the Federal Reserve.

For good reason.

Interest rates influence the relative attractiveness of cash and bonds, financial conditions, liquidity expectations, and risk appetite.

But there is no simple rule saying:

Fed raises rates = Bitcoin falls.

Markets are more complicated than that.

What happened to stocks on Fed day?

That reaction illustrates the immediate market interpretation of the decision.

Investors weren’t simply reacting to the 25-basis-point move.

They were also reacting to what the Fed might do next.

Why crypto can become more volatile

Crypto assets generally trade as risk assets, although their behavior can vary significantly by market regime.

When investors expect higher rates for longer, some capital may become more attracted to relatively safer yield-producing assets.

At the same time:

  • Liquidity expectations can change.
  • The U.S. dollar can strengthen.
  • Treasury yields can rise.
  • Risk premiums can expand.
  • Leverage can unwind.
  • Speculative assets can experience larger price swings.

Bitcoin’s reaction after the September decision demonstrated why the relationship isn’t mechanical. Reuters and other market reports noted significant market volatility, while Bitcoin later showed resilience despite the rate increase.

That is why traders should avoid building a strategy around a single macroeconomic rule.

What does the Fed rate hike in 2026 mean for forex?

Forex traders watch interest-rate differentials closely.

Suppose U.S. rates remain relatively high while another central bank moves toward lower rates.

All else equal, that can influence capital flows and currency demand.

But “all else equal” is doing a lot of work.

Forex prices also respond to:

  • Inflation
  • Employment
  • GDP growth
  • Central-bank communication
  • Government policy
  • Geopolitical developments
  • Commodity prices
  • Risk sentiment
  • Positioning
  • Trade flows

The dollar strengthened on September 16 following the Fed decision, while Treasury yields rose.
Fed rate hike impact on crypto forex, and U.S. dollar markets

That doesn’t mean USD will rise indefinitely.

It means the Fed’s policy path became an important variable for currency markets.

Trading the Fed is not as simple as trading the headline.

Professional traders often distinguish between:

  1. What the market expected.
  2. What the Fed actually did.
  3. What the Fed communicated.
  4. How the decision changes future expectations.

A rate hike that was already fully priced into markets can produce very little movement.

A decision that changes expectations for future policy can produce much more.

That’s why the Fed rate hike in 2026 should be viewed as an information event rather than a simple buy-or-sell signal.

Broker affiliate note

Your original brief specified Exness here, but that needs a jurisdiction warning.

Exness states that it does not provide services to residents of the United States and several other jurisdictions, including the European Union and the United Kingdom. Its regulatory page also lists different regulated entities for different regions.

Therefore, do not publish a generic:

“Open a Trading Account with Exness.”

CTA to a U.S./UK/EU audience.

Instead, use a geo-targeted broker CTA.

For readers in jurisdictions where Exness is available, the CTA can lead to your tracked partner URL. For U.S., UK, and EU readers, direct them to a broker legally available in their jurisdiction.

That approach is more transparent and protects the credibility of the article.


The Retirement Impact No One Is Talking About

The Fed rate hike in 2026 isn’t only a story about mortgages and trading.

It also matters to people approaching retirement.

Why?

Because retirement planning involves a combination of:

  • Income
  • Cash reserves
  • Bonds
  • Equities
  • Inflation
  • Healthcare costs
  • Longevity
  • Taxes
  • Withdrawal rates
  • Interest rates

A change in interest rates can affect several of these variables simultaneously.

The retirement fluency problem

The 2026 TIAA Institute-GFLEC Personal Finance Index found that retirement knowledge remains limited.

That matters because higher interest rates don’t solve retirement planning automatically.

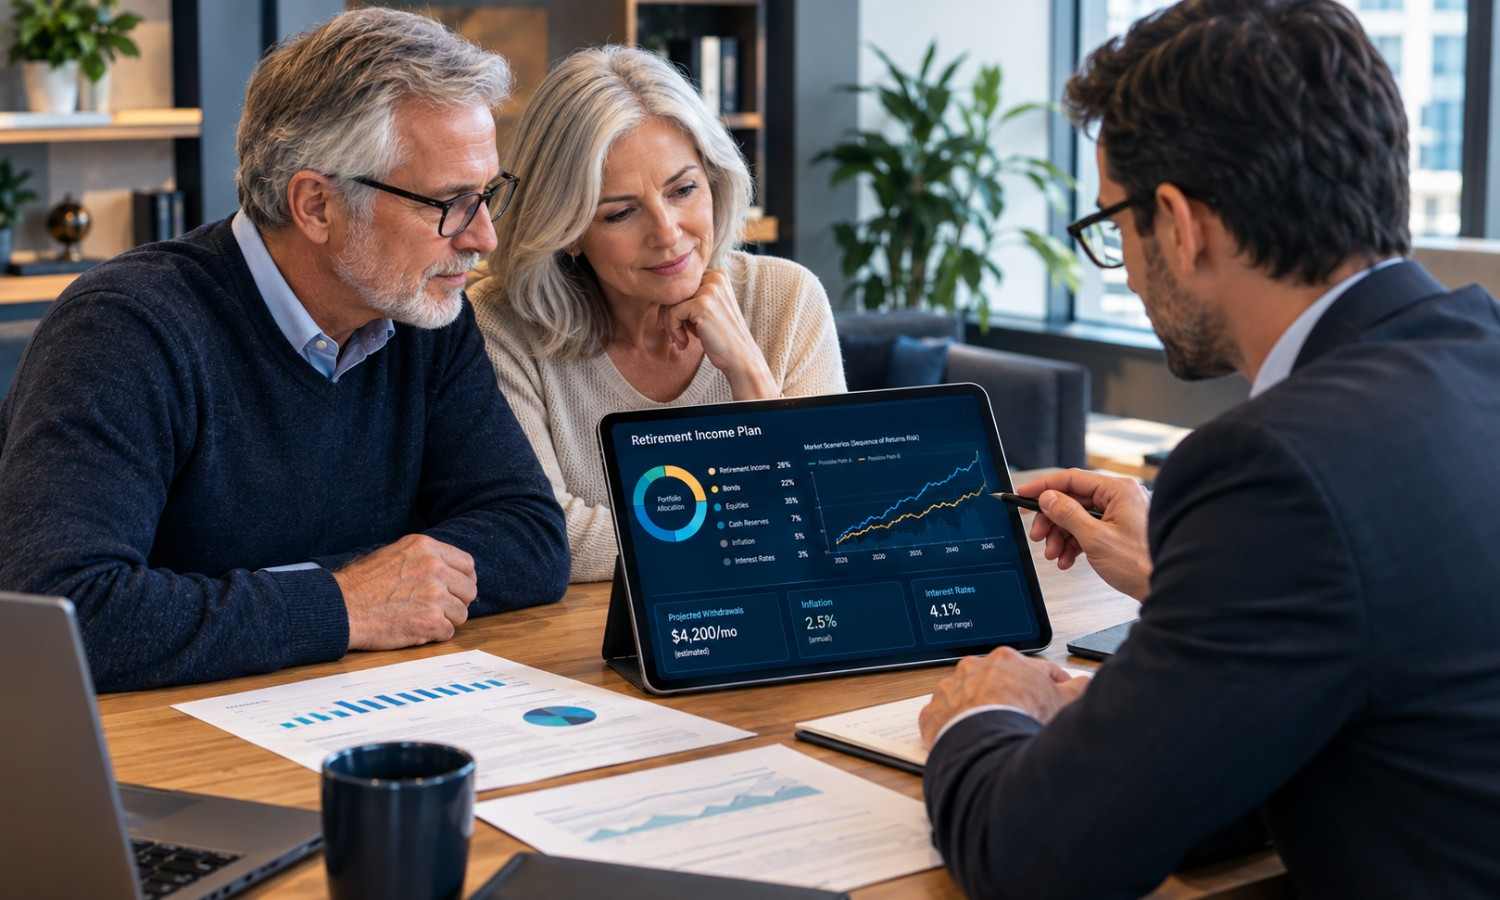
Retirement planning during a higher interest rate environment in 2026

A retiree might earn more on cash and short-duration fixed income while simultaneously facing:

  • Higher borrowing costs
  • Inflation uncertainty
  • Equity-market volatility
  • Bond-price volatility
  • Higher healthcare expenses

Understanding the interaction is more important than reacting to any single Fed announcement.

What is sequence-of-returns risk?

Sequence-of-returns risk describes the danger that poor investment returns occur early in retirement while withdrawals are being made.

Imagine two retirees who experience exactly the same long-term average investment return.

If one experiences large losses during the first few years of retirement and the other experiences those losses later, their financial outcomes can be very different because the first retiree is selling assets while the portfolio is depressed.

Higher interest rates can change the balance between growth assets and income-producing assets.

But that does not automatically mean retirees should move heavily into bonds or cash.

The right mix depends on:

  • Age
  • Portfolio size
  • Spending needs
  • Guaranteed income
  • Social Security
  • Pension income
  • Tax situation
  • Risk tolerance
  • Expected longevity

Retirement within 10 years?

This is a good point to consider professional planning.

A matching service can help consumers identify financial professionals, but “fiduciary” status and compensation arrangements should still be verified directly with the advisor.

Ask:

  • Are you a fiduciary?
  • When does the fiduciary obligation apply?
  • How are you compensated?
  • Do you receive commissions?
  • What services are included?
  • What is the total annual cost?
  • What conflicts of interest exist?
  • Are you registered with the appropriate regulator?

The goal isn’t to outsource every decision.

It’s to understand the decisions that could affect decades of retirement income.


What the Fed Is Signaling for the Rest of 2026

This may be the most important part of the September decision.

The Fed didn’t simply raise rates.

Its projections showed that policymakers expect rates to remain relatively elevated.

The September Summary of Economic Projections put the median federal funds rate projection at 4.1% for the end of 2026 and 4.1% for the end of 2027, compared with June medians of 3.8% and 3.6%, respectively.

That represents a significant change in the rate outlook.

Does the dot plot guarantee another hike?

No.

The dot plot is not a promise.

It represents individual policymakers’ projections of appropriate monetary policy under their economic assumptions.

Those assumptions can change.

Inflation could fall faster than expected.

Economic growth could weaken.

Labor-market conditions could deteriorate.

Energy prices could change.

Geopolitical developments could alter the outlook.

That’s why readers should treat the dot plot as a policy signal rather than a guaranteed roadmap.

What do Fed officials expect?

The September projections indicate that another increase is part of many policymakers’ outlooks.

Reuters reported that policymakers’ median projection pointed to one more rate increase in 2026.

A separate count of the Fed’s projections showed that 16 of 18 participants expected at least one more increase during 2026.

That is important.

But it still doesn’t mean the Fed has committed to another hike.

What is CME FedWatch showing?

CME FedWatch uses federal-funds futures pricing to estimate market-implied probabilities for future FOMC decisions.

Around September 18, market pricing put the probability of another October increase above 50%, according to market reporting. A Wall Street Journal report later cited a 58% probability of an October increase.

Those probabilities can change every trading day.

The key distinction is

Fed projections โ‰  market probabilities โ‰  guaranteed future policy.

All three provide different pieces of information.

Why did the 2027 median jump to 4.1%?

The 2027 median is particularly important because it suggests policymakers now envision a higher rate environment than they did in June.

Reuters reported that the Fed’s projections showed a gradual path after the 2026 increase, with the median remaining at 4.1% through 2027.

For consumers, that could mean:

  • Mortgage rates may remain elevated.
  • Savings yields may remain attractive.
  • Bond yields may remain relatively high.
  • Variable-rate debt may remain expensive.
  • Equity valuations may face a different discount-rate environment.
  • Crypto may continue reacting strongly to liquidity expectations.

But again, these are potential transmission channelsโ€”not guaranteed outcomes.


5 Action Steps for Smart Americans Right Now

The Fed rate hike in 2026 creates different challenges for borrowers, savers, investors, and retirees.

Instead of trying to predict every move, focus on the parts of your finances you can control.

1. Check Your Credit Score

Your credit profile can materially affect the terms available to you when you apply for a mortgage, personal loan, or other credit product.

Check Your Free Credit Score โ†’

Experian says its free service provides a FICO score based on Experian data and that checking your own score does not lower your score.

Also check your actual credit reports for errors.

For U.S. consumers, AnnualCreditReport.com is the official source for free reports from the three major credit bureaus.

Action: Review your reports before applying for major credit.


2. Compare High-Yield Savings Rates

Don’t leave a large emergency fund earning almost nothing simply because you’ve always used the same bank.

Compare High-Yield Savings Rates โ†’

As of September 24, Bankrate listed leading savings APYs as high as 4.20%, while its national average was around 0.64%.

Action: Compare APY, fees, minimum balances, and deposit insurance before moving your money.


3. Review Your Mortgage or HELOC

If you already have a fixed-rate mortgage, don’t assume a Fed hike requires action.

If you have a variable-rate HELOC, however, calculate the effect of higher rates on your monthly payment.

If you’re buying a home, compare several lenders rather than assuming the advertised national mortgage rate is what you will receive.

Freddie Mac’s latest national average was 7.03% for a 30-year fixed mortgage as of September 24.

Action: Get multiple quotes and compare APR and total borrowing costs.


4. Review Your Portfolio for a Higher-for-Longer Environment

This does not mean selling stocks because the Fed raised rates.

It means understanding your exposure.

Ask:

  • How much cash do I need?
  • How much debt do I carry?
  • What is my bond duration?
  • How much volatility can I tolerate?
  • Am I overly concentrated in speculative assets?
  • Does my portfolio match my time horizon?
  • What happens if rates stay elevated for another year?

If you’re investing for decades, short-term market movements shouldn’t automatically change your long-term plan.

But if your portfolio is heavily leveraged or concentrated, a higher-rate environment deserves attention.


5. Revisit Your Retirement Plan

If retirement is less than 10 years away, interest-rate changes can affect both your income strategy and your portfolio risk.

Consider reviewing:

  • Emergency reserves
  • Social Security timing
  • Pension income
  • Bond allocation
  • Equity allocation
  • Healthcare expenses
  • Long-term-care assumptions
  • Withdrawal strategy
  • Tax planning
  • Estate planning

The 2026 retirement-fluency data from TIAA/GFLEC shows why these decisions can be difficult: only 27% of adults answered the Medicare question correctly, and 28% answered the long-term-care question correctly.

Action: If your retirement plan is complex, consider obtaining advice from a qualified professional and verify their credentials and compensation structure.


Frequently Asked Questions

Will the Fed raise rates again in 2026?

The September 2026 projections point toward another increase for many policymakers, and market pricing around September 18 indicated more than a 50% probability of an October increase. However, neither the Fed’s projections nor CME FedWatch guarantees a future decision.

The next scheduled FOMC meeting is October 27-28, 2026.


Should I lock in a mortgage rate now?

There is no universal answer.

If you’re already under contract or need certainty for your housing budget, locking can reduce the risk of rates moving against you before closing.

If you’re simply shopping and have flexibility, compare lenders and understand their rate-lock policies before making a decision.

Remember that the Fed does not directly set the 30-year mortgage rate.

Freddie Mac’s 30-year average was 7.03% on September 24, 2026.


Are high-yield savings accounts safe?

A high-yield savings account can be a suitable place for emergency cash when the underlying institution is properly insured and the account falls within applicable insurance limits.

For U.S. bank deposits, verify FDIC insurance. For federally insured credit unions, verify NCUA coverage.

Don’t assume that every investment product marketed as a cash alternative has the same protections.


How do rate hikes affect crypto?

Higher rates can influence crypto through liquidity conditions, opportunity costs, dollar strength, Treasury yields, and investor risk appetite.

However, the relationship is not mechanical.

Bitcoin and other crypto assets can rise or fall after a Fed hike depending on what investors had already priced in and what the Fed communicates about future policy.

The September 2026 decision demonstrated this complexity: risk assets initially reacted negatively, but crypto subsequently showed resilience.


What should retirees do right now?

Retirees shouldn’t make major portfolio decisions solely because the Federal Reserve raised rates.

Instead, review:

  • Cash flow needs
  • Emergency reserves
  • Fixed-income exposure
  • Equity risk
  • Inflation protection
  • Healthcare costs
  • Withdrawal rates
  • Tax implications

Higher rates can improve income opportunities on cash and some fixed-income investments while creating other risks.

The appropriate response depends on the individual’s complete financial situation.


Will higher Fed rates make savings accounts pay more?

They can, but banks don’t have to pass the full increase through to depositors.

Online banks and competitive savings providers may adjust their APYs more aggressively than large traditional banks.

That is why comparing rates matters.

Bankrate’s September 2026 data showed a substantial gap between top high-yield savings rates and the national average.


Does a Fed rate hike automatically mean stocks and crypto will fall?

No.

Markets respond to expectations as well as actual decisions.

If a rate increase was already fully priced in, the announcement may produce little reaction.

Conversely, changes in the Fed’s outlook can produce larger moves because investors reprice future earnings, liquidity, and discount rates.

The September 16 market reaction showed how quickly equities can move when investors interpret the Fed’s message as more restrictive.


What the Fed Rate Hike 2026 Means for Your Money

The September 2026 decision is more than another headline about the Federal Reserve.

It changes the financial backdrop for households.

For borrowers, higher rates can increase the cost of new mortgages, HELOCs, credit cards, and variable-rate debt.

For savers, the environment creates an opportunity to earn more on cashโ€”provided you shop around and understand account protections.

For investors, higher rates change the relative attractiveness of cash and bonds while potentially affecting equity valuations and risk appetite.

For crypto and forex traders, the most important variable may not be the 25-basis-point increase itself but what the Fed signals about the next several meetings.

And for retirees, the central issue is not simply whether rates rise or fall. It is whether the entire income and risk-management strategy can withstand changing market conditions.

The latest projections show a median federal funds rate of 4.1% at the end of both 2026 and 2027, higher than policymakers projected in June.

That makes one message especially important:

Don’t build your financial plan around a single forecast.

Build it around scenarios.

What happens if mortgage rates remain around 7%?

What happens if savings rates fall?

What happens if inflation remains elevated?

What happens if the Fed raises rates again?

What happens if economic growth weakens and rates eventually decline?

The households that are best positioned for an uncertain rate environment are not necessarily the ones that predict the next Fed decision correctly.

They’re the ones whose finances can withstand several possible outcomes.


Final Takeaway

The Fed rate hike in 2026 has pushed the federal funds target range to 3.75%-4.00%, and the September projections point to a higher rate path than policymakers anticipated in June.

That means Americans should pay attentionโ€”but not panic.

If you’re borrowing, focus on your credit profile and compare financing options.

If you’re saving, compare high-yield accounts rather than accepting a low rate by default.

If you’re investing, understand how higher rates affect your particular portfolio instead of reacting to headlines.

If you’re trading crypto or forex, treat Fed announcements as macroeconomic events rather than automatic trading signals.

And if you’re approaching retirement, focus on cash flow, diversification, sequence risk, and the sustainability of your withdrawal plan.

The Federal Reserve controls a benchmark rate.

You control how prepared your household is for the environment that follows.

Disclosure: This article is for educational and informational purposes only and is not financial, investment, tax, mortgage, or retirement advice. Some links may be affiliate links, meaning FinWireStack may receive compensation if you use them, at no additional cost to you.


Author Bio

Humphrey Nyagaโ€”Finance & Technology Writer, FinWireStack

Humphrey N is a finance and technology writer and the founder of FinWireStack, where he covers investing, trading, personal finance, financial technology, and emerging digital trends. His work focuses on making complex financial and technology topics easier to understand through research-driven, practical explanations.

FinWireStack’s editorial approach emphasizes independent research, transparent disclosures, risk awareness, and actionable financial education.

Editorial note: Financial markets, interest rates, and financial products change frequently. Readers should verify current rates, terms, fees, eligibility, and regulatory status directly with the relevant provider before making financial decisions.
The CFTC’s New Crypto Guidance: What the No-Action Stance on ‘Passive Software’ Really Means

CFTC crypto guidance 2026: CFTC headquarters in Washington D.C.

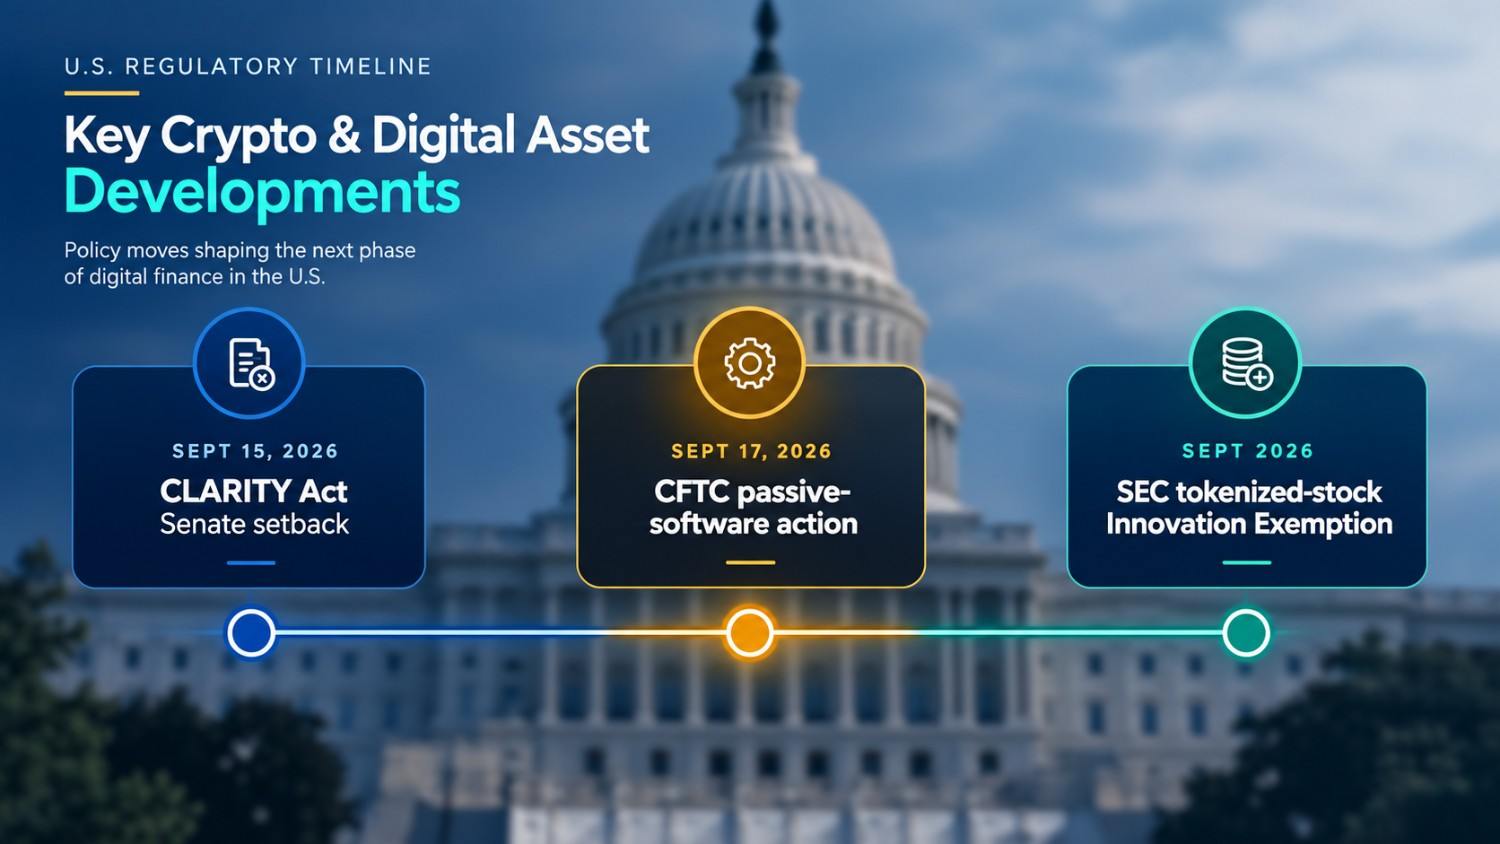
On September 17, 2026, the Commodity Futures Trading Commission issued what may become one of the year’s most important pieces of CFTC crypto guidance for developers building trading interfaces. The new position gives qualifying providers of โ€œpassive softwareโ€ a path to facilitate users’ access to CFTC-regulated derivatives without registering as introducing brokers, provided they satisfy specific conditions.

That is the core of the new CFTC crypto guidance: software can remain software rather than automatically becoming a regulated intermediary merely because it gives users a front end for trading.

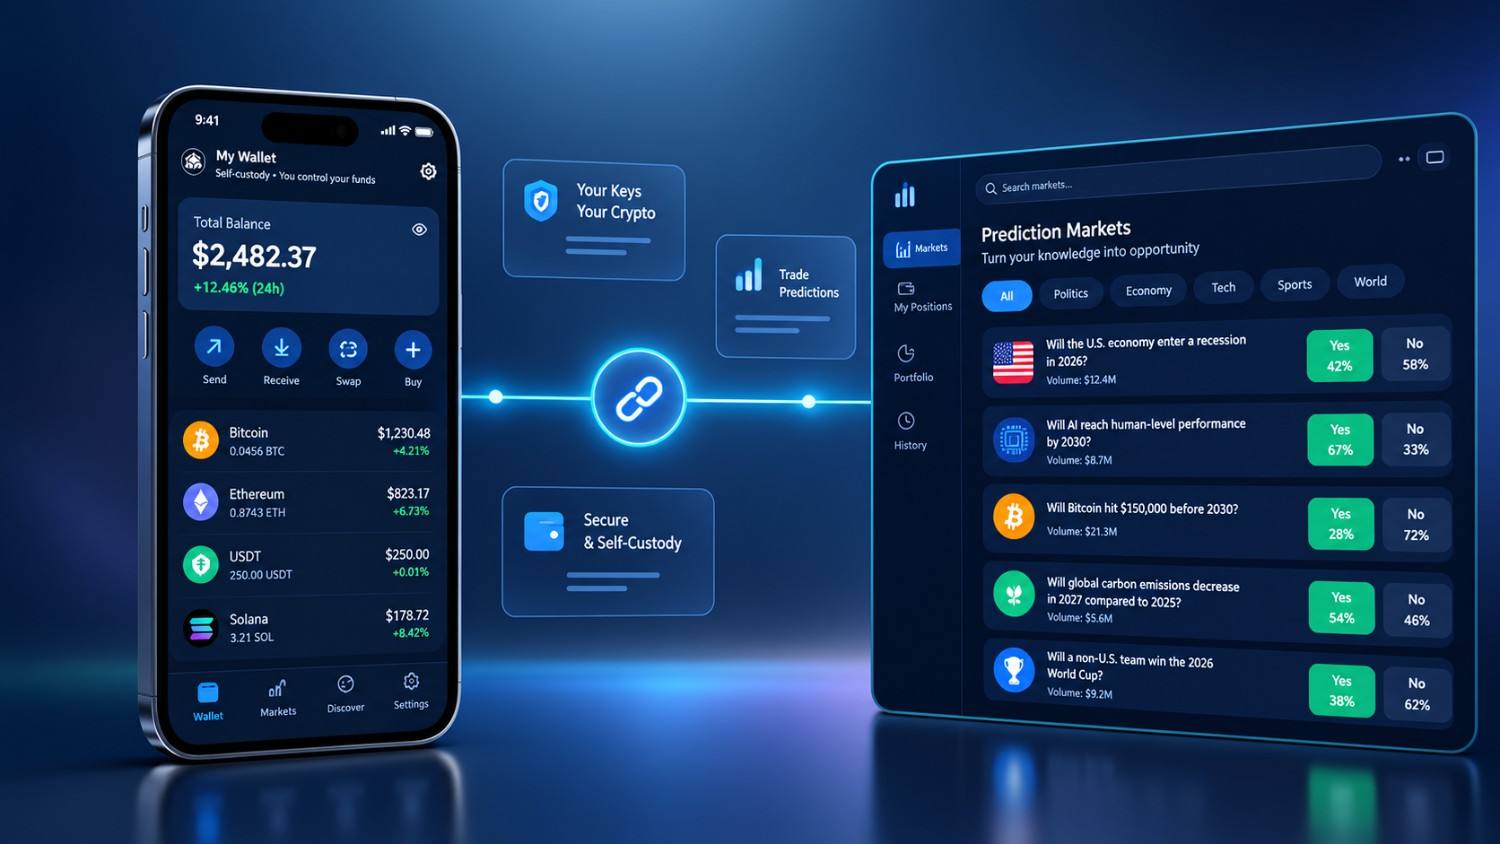
For U.S. traders, the implications are practical. A wallet or application could potentially connect users to regulated futures commission merchants, introducing brokers and designated contract markets without taking custody of customer assets or making trading decisions itself.

But the CFTC crypto guidance is not a blanket exemption for every crypto application. It is conditional staff relief, and the distinction between a passive interface and an active intermediary is critical.

The question for developers is therefore not simply, โ€œCan my wallet offer derivatives?โ€ It is: Can my software meet the CFTC’s definition and conditions for passive operation?

Caption: CFTC crypto guidance 2026 is giving qualifying passive-software providers a clearer route to connect users with regulated derivatives markets.

What the CFTC Actually Announced: The CFTC Crypto Guidance Explained

The September 17 action came from the CFTC’s Market Participants Division through Staff Letter 26-25. The agency said its staff would not recommend enforcement against qualifying passive-software providers or relevant personnel for failure to register as an introducing broker or associated person, subject to specified conditions.

The CFTC crypto guidance applies specifically to the provider’s provision and marketing of software that facilitates users’ trading with registered futures commission merchants, introducing brokers and designated contract markets.

That wording matters.

The CFTC did not announce that all crypto wallets are now outside broker rules. Instead, it created a conditional no-action position that can apply to software providers whose role remains sufficiently passive.

The CFTC’s description is important because the agency is drawing a functional line between technology that provides an interface and an intermediary that actively participates in a transaction.

A passive software provider can, subject to the letter’s conditions, provide functionality allowing users to:

  • View market information.
  • View available products.
  • Review position information.
  • Submit orders to registered counterparties.
  • Access CFTC-regulated derivatives through an interface.
  • Use self-custodial software without handing control of their assets to the software provider.

The provider’s role becomes problematic if it crosses into activities such as custody, trading discretion, order-routing discretion, investment recommendations, or other forms of active participation.

That is why the CFTC crypto guidance should be understood as a boundary-setting exercise rather than a general deregulation of crypto applications.

In simple terms:

The software can provide the road and dashboard; the regulated financial intermediary remains responsible for the regulated market activity.

The CFTC’s September announcement explicitly says the new position is similar to the relief granted in March and is now broadly available to qualifying passive-software providers.

The Conditions You Must Meet to Qualify

The phrase โ€œpassive software exemptionโ€ is useful shorthand, but technically the regulatory mechanism is a no-action position, not a statutory exemption.

The CFTC crypto guidance is conditional.

According to the CFTC’s letter and legal analysis of Staff Letter 26-25, qualifying providers must satisfy a series of requirements designed to keep the software provider from becoming an active intermediary.

The major conditions include:

  1. No custody of customer assets. The software provider must not take possession or control of users’ funds or digital assets.
  2. No trading discretion. The provider cannot decide whether a user should buy or sell.
  3. No discretionary order routing. The software cannot independently determine where or how an order should be executed in a way that makes the provider an active intermediary.
  4. Direct onboarding with regulated entities. Users must be onboarded with the registered intermediary rather than being transformed into customers solely of the software provider.
  5. Independent access. Users must be able to access the registered intermediary independently of the passive software provider.
  6. Risk and conflict disclosures. The provider must satisfy specified disclosure obligations.
  7. Compliant advertising. Marketing must comply with applicable requirements, including conditions concerning National Futures Association standards.
  8. Recordkeeping. The provider must maintain required records.
  9. CFTC jurisdiction. The provider must consent to CFTC jurisdiction under the conditions described in the letter.
  10. Responsibility arrangements with registered entities. The framework includes specified undertakings involving the registered firms the software connects to.

The practical lesson from the CFTC crypto guidance is that โ€œnon-custodialโ€ alone is not enough.

A wallet could avoid holding customer assets and still perform activities that move it beyond the passive-software framework.

The legal question is therefore functional: What does the software actually do?

The CFTC’s original March relief involved Phantom Technologies and Staff Letter 26-09. The agency’s September letter expands the framework beyond that original provider. The CFTC’s staff-letter index identifies 26-09 as the March position covering a self-custodial crypto wallet and 26-25 as the September position covering passive software providers more broadly.

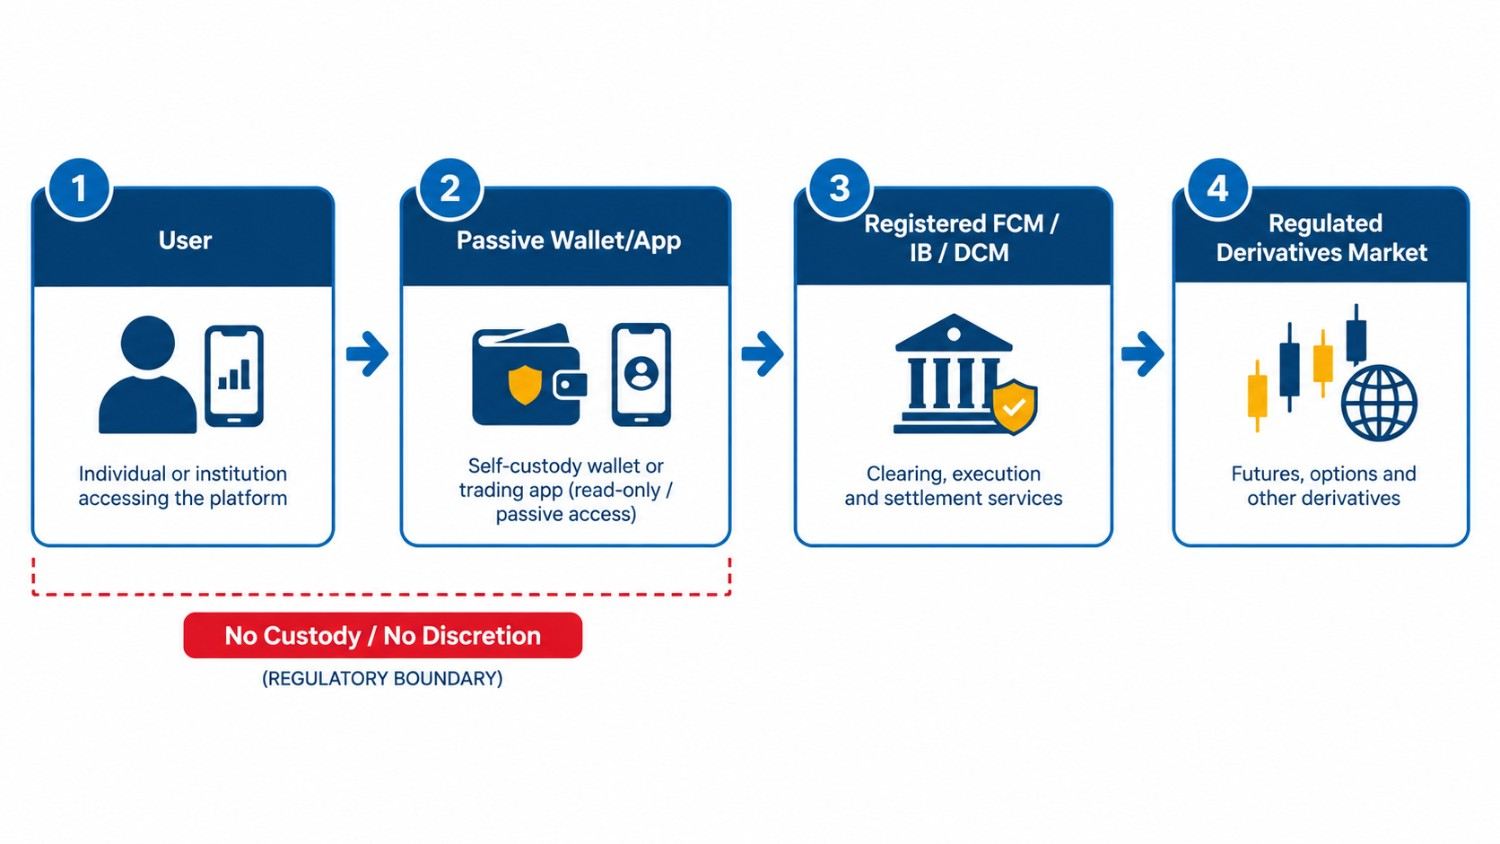
CFTC crypto guidance diagram explaining passive software exemption

The Phantom-Kalshi precedent

The March Phantom action is particularly important because it demonstrated how a self-custodial crypto wallet could potentially connect users to regulated markets without becoming a traditional broker itself.

Phantom subsequently became associated with Kalshi prediction-market access, giving the industry a concrete example of the model.

Reports have described Phantom’s user base as exceeding 20 million, illustrating why the issue matters beyond a niche developer audience.

The September CFTC crypto guidance effectively takes the model from a company-specific precedent and makes similar relief available to other qualifying providers.

CFTC crypto guidance: Phantom wallet and Kalshi prediction market integration

Caption: CFTC crypto guidance creates a conditional passive-software pathway between users, software interfaces and regulated derivatives venues.

Why the CFTC Crypto Guidance Matters for U.S. Traders and Developers

For developers, the biggest change may be the reduction in uncertainty around product design.

Before the September action, a company building a wallet or trading interface could face a difficult question: if the software lets a user submit an order to a regulated derivatives venue, does the interface itself become an introducing broker?

CFTC crypto guidance impact on Bitcoin and crypto trading chart

The CFTC crypto guidance provides staff-level relief when the provider fits the passive-software model and meets the specified conditions.

That can change how developers structure products.

A wallet could potentially become a gateway to:

  • Regulated futures.
  • Event contracts.
  • Prediction-market contracts.
  • Crypto perpetual contracts.
  • Other CFTC-regulated derivatives.

The key is that the wallet does not become the entity actually providing the regulated market infrastructure.

For traders, the potential benefit is convenience. Instead of moving between multiple applications, a user could potentially access regulated products through software they already use.

But convenience does not eliminate trading risk.

A prediction market remains a derivative-style product. A perpetual contract can involve substantial leverage and liquidation risk. A self-custodial wallet also leaves users responsible for security, authentication and transaction decisions.

The CFTC crypto guidance changes the regulatory architecture around access. It does not turn speculative trading into low-risk investing.

Caption: CFTC crypto guidance could change how U.S. traders access regulated crypto derivatives and prediction markets through familiar software interfaces.

The CLARITY Act Setback and Why Agency Guidance Now Leads

The timing of the CFTC crypto guidance is difficult to ignore.

Two days before the CFTC action, the U.S. Senate failed to advance the CLARITY Act in a procedural vote.

CFTC crypto guidance vs CLARITY Act: U.S. crypto regulation timeline

The September 15 vote fell short of the 60 votes needed to advance the legislation. Reuters reported that the measure received 50 votes in favor and 49 against, leaving the broader federal market-structure framework stalled.

The significance is not that the CLARITY Act has necessarily disappeared forever. The significance is that comprehensive legislation has not yet supplied the durable statutory framework that many market participants have been seeking.

That makes agency action more important in the near term.

The CFTC crypto guidance is therefore part of a broader regulatory story: federal agencies are using their existing authorities to address specific market structures while Congress continues to debate legislation.

CoinDesk reported that the failed Senate vote became a significant market event for crypto, while The Wall Street Journal reported that the legislative setback shifts attention back toward agencies such as the SEC and CFTC.

For developers, that creates both opportunity and uncertainty.

Agency relief can arrive much faster than a new federal statute. But staff no-action positions and temporary exemptions do not necessarily have the same durability as legislation enacted by Congress.

That distinction should remain central to any analysis of the CFTC crypto guidance.

The Bigger Picture โ€” CFTC and SEC Move in Tandem

The CFTC did not act in isolation.

On September 17, the same day as the passive-software announcement, the Securities and Exchange Commission issued its own โ€œInnovation Exemptionโ€ for certain tokenized National Market System stocks.

The SEC’s action provides temporary, conditional relief for Tokenized Securities Venues using permissioned automated market makers and liquidity pools to trade qualifying tokenized stocks.

The exemption is subject to conditions including limits on symbols and trading volume, investor-rights requirements, issuer notification and objection procedures, public smart contracts and trading-stoppage coordination.

The SEC said the exemption will expire five years after publication.

Taken together, the SEC and CFTC actions point toward a similar regulatory experiment.

The CFTC crypto guidance addresses the software layer connecting users with regulated derivatives markets.

The SEC’s Innovation Exemption addresses an infrastructure layer for tokenized securities markets.

Neither action creates a permanent comprehensive crypto market structure.

Instead, both demonstrate how agencies can use existing authority to accommodate specific technology models while gathering information for future regulation.

That is a crucial distinction for institutional investors and developers.

The current regulatory environment is becoming more specific, but it is not necessarily becoming final.

Expert Analysis and Market Implications

The immediate market implication of the CFTC crypto guidance is likely to be more important for infrastructure companies than for Bitcoin’s short-term price.

The clearest beneficiaries are potentially developers building wallets, interfaces, trading applications and financial platforms that want to connect users with regulated derivatives.

The September action could also increase competitive pressure among platforms offering prediction markets and derivatives.

Investor’s Business Daily reported that the announcement affected shares of companies exposed to prediction-market competition, with sports-betting companies declining while some financial platforms with prediction-market exposure gained.

That does not mean the CFTC action guarantees higher crypto prices or trading volumes.

A more measured interpretation is that the CFTC crypto guidance removes one layer of regulatory uncertainty for a defined category of software providers.

The longer-term effect will depend on adoption.

Developers still need to determine whether their architecture actually fits the conditions. Regulated counterparties must remain willing to work with them. Users must adopt the products. And regulators can modify the framework.

The Blockchain Association described the action as important clarity for developers while also emphasizing that the relief is an interim step and that durable regulatory clarity remains important.

That is probably the most useful way for sophisticated investors to view the announcement: meaningful regulatory clarification, but not the end of U.S. crypto-regulatory uncertainty.

What to Watch Next

The next phase of the CFTC crypto guidance story will be implementation.

1. More wallet and trading-app integrations

Watch for announcements from self-custodial wallets and trading applications seeking connections with registered futures commission merchants and designated contract markets.

The important question will be whether these integrations preserve the passive characteristics described by the CFTC.

2. More CFTC guidance

The September action may not be the final word on software interfaces.

Future CFTC statements could address other forms of automated trading, decentralized interfaces, data services and derivatives infrastructure.

3. Prediction-market expansion

Prediction markets are likely to remain a major test case.

The CFTC’s framework could make it easier for software providers to connect users with regulated event contracts, but the market will still face questions involving contract design, state-level disputes, compliance and market integrity.

4. Crypto derivatives open interest

Institutional traders should monitor derivatives open interest, funding rates, volume and liquidation activity rather than assuming that regulatory clarity automatically produces stronger prices.

If more applications add regulated derivatives access, the resulting competition could affect liquidity and user acquisition across platforms.

5. The CLARITY Act

Congressional action remains important.

The CFTC crypto guidance can provide administrative relief, but legislation would provide a different type of durability.

The September Senate setback therefore does not eliminate the importance of future congressional action.

6. SEC-CFTC coordination

The simultaneous SEC and CFTC actions are worth watching.

If both agencies continue creating technology-specific pathways under existing authority, U.S. digital-asset infrastructure could increasingly develop through agency action while Congress works toward broader legislation.

Frequently Asked Questions

What is the CFTC passive software exemption?

The term โ€œpassive software exemptionโ€ describes the conditional no-action relief in the CFTC crypto guidance for qualifying software providers that facilitate access to regulated derivatives without becoming active intermediaries.

Technically, it is a staff no-action position rather than a new statutory exemption.

Does the CFTC crypto guidance apply to my wallet?

Potentially, if the wallet qualifies as passive software and satisfies all applicable conditions in Staff Letter 26-25.

The CFTC crypto guidance does not automatically cover every wallet simply because it is self-custodial. The software’s actual functionality and relationship with regulated counterparties matter.

Can a crypto wallet now offer prediction-market trading?

The CFTC crypto guidance creates a pathway for qualifying passive software to facilitate users’ access to CFTC-regulated event contracts and other derivatives through registered entities.

The wallet still needs to satisfy the letter’s conditions.

How does the CFTC regulate prediction markets?

The CFTC crypto guidance is relevant when prediction-market products fall within the CFTC’s regulated derivatives framework. The agency regulates derivatives markets through its statutory authority and registered market infrastructure.

Prediction markets can also raise legal questions outside the CFTC’s direct jurisdiction, so the September action should not be interpreted as resolving every prediction-market dispute.

Does the CFTC no-action letter mean crypto developers no longer need registration?

No.

The CFTC crypto guidance provides conditional relief from specified introducing-broker and associated-person registration requirements for qualifying passive software providers.

A developer whose product performs activities outside the letter’s conditions cannot simply assume the relief applies.

Does the CLARITY Act change the CFTC crypto guidance?

Not directly.

The CFTC crypto guidance is based on the CFTC’s existing authority and Staff Letter 26-25. The failed September 15 Senate vote matters because the CLARITY Act would establish a broader statutory framework if enacted.

The legislative and agency tracks should therefore be viewed separately.

Conclusion: What the CFTC Crypto Guidance Really Changes

The most important takeaway from the CFTC crypto guidance is not that crypto wallets have suddenly become unregulated.

They have not.

The important development is narrower and more useful: qualifying passive software providers now have a clearer regulatory pathway for connecting users with regulated derivatives markets without automatically registering as introducing brokers.

The CFTC crypto guidance also expands the significance of the March Phantom precedent. What began as relief for a specific self-custodial wallet model has now become a broadly available framework for similarly situated software providers.

For developers, that could reduce compliance uncertainty and encourage new products.

For traders, it could mean easier access to prediction markets and regulated crypto derivatives.

For institutional investors, the more important signal is structural: U.S. regulators are increasingly addressing blockchain-based market infrastructure through targeted agency action.

But the CFTC crypto guidance remains conditional, and the failed CLARITY Act vote means the search for durable statutory certainty is not over.

The next stage will be implementation.

Watch which wallets integrate regulated derivatives, which registered firms partner with them, how prediction-market volumes evolve, and whether Congress eventually supplies a permanent framework.

For U.S. crypto markets, the distinction between software, intermediaries, and regulated venues is becoming one of the most important regulatory questions of 2026.

Forex vs. Crypto Trading: 15 Essential Differences Every Beginner Must Know for Ultimate Success in 2027

Forex vs Crypto Trading comparison showing a trader choosing between the foreign exchange market and cryptocurrency investing in 2027.

Forex vs. crypto trading is one of the most common questions asked by new investors entering the financial markets in 2027.

Some people are attracted to the stability and liquidity of the foreign exchange market. Others are fascinated by the rapid growth of Bitcoin, Ethereum, and thousands of digital assets that have transformed global finance over the past decade.

Both markets offer opportunitiesโ€”but they also carry significant risks.

Unfortunately, social media often presents only one side of the story. Influencers showcase luxury lifestyles, extraordinary profits, and overnight success while rarely discussing volatility, emotional discipline, risk management, or the years of education required to become consistently successful.

The reality is that Forex vs. Crypto trading is not about choosing the market that promises the biggest returns. It is about selecting the market that best matches your financial goals, personality, available time, risk tolerance, and investment strategy.

By the end of this comprehensive guide, you’ll understand:

  • The major differences between Forex vs Crypto Trading.
  • Which market is generally more suitable for beginners.
  • How artificial intelligence is changing both industries.
  • Common scams and warning signs.
  • Risk management strategies for each market.
  • Which market may better suit different investor profiles.

Whether your goal is to trade actively, build long-term wealth, or simply understand the modern financial landscape, this guide will help you make more informed decisions.


Forex vs. Crypto Trading: What Is Forex Trading?

Forex trading is the buying and selling of national currencies through the global foreign exchange market.

Forex is the largest financial market in the world, with daily trading volume exceeding $6 trillion. Regulatory oversight is a key feature, with bodies like the U.S. Commodity Futures Trading Commission (CFTC) and the UK Financial Conduct Authority (FCA) providing frameworks for brokers.

Examples include:

  • EUR/USD
  • GBP/USD
  • USD/JPY
  • GBP/JPY

Currencies fluctuate because of:

  • Interest rates
  • Inflation
  • GDP growth
  • Employment reports
  • Central bank policy
  • International trade
  • Political developments

The Forex market processes trillions of dollars in daily trading volume, making it the largest financial market in the world.

Its high liquidity often results in tighter spreads and efficient execution, particularly for major currency pairs.


Forex vs. Crypto Trading: What Is Crypto Trading?

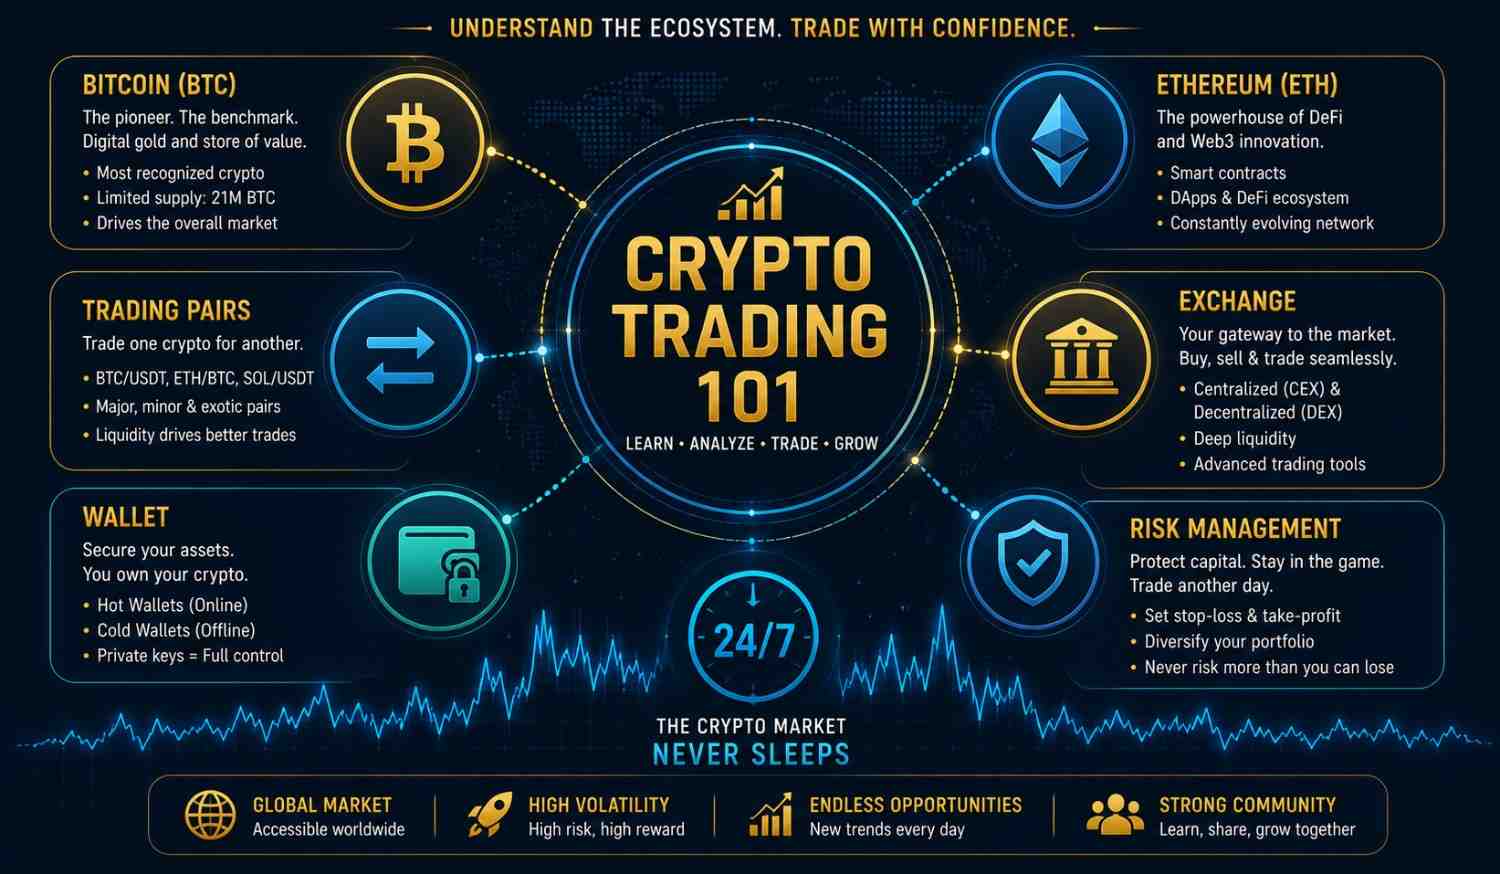
Crypto trading involves buying and selling digital assets that operate on blockchain technology.

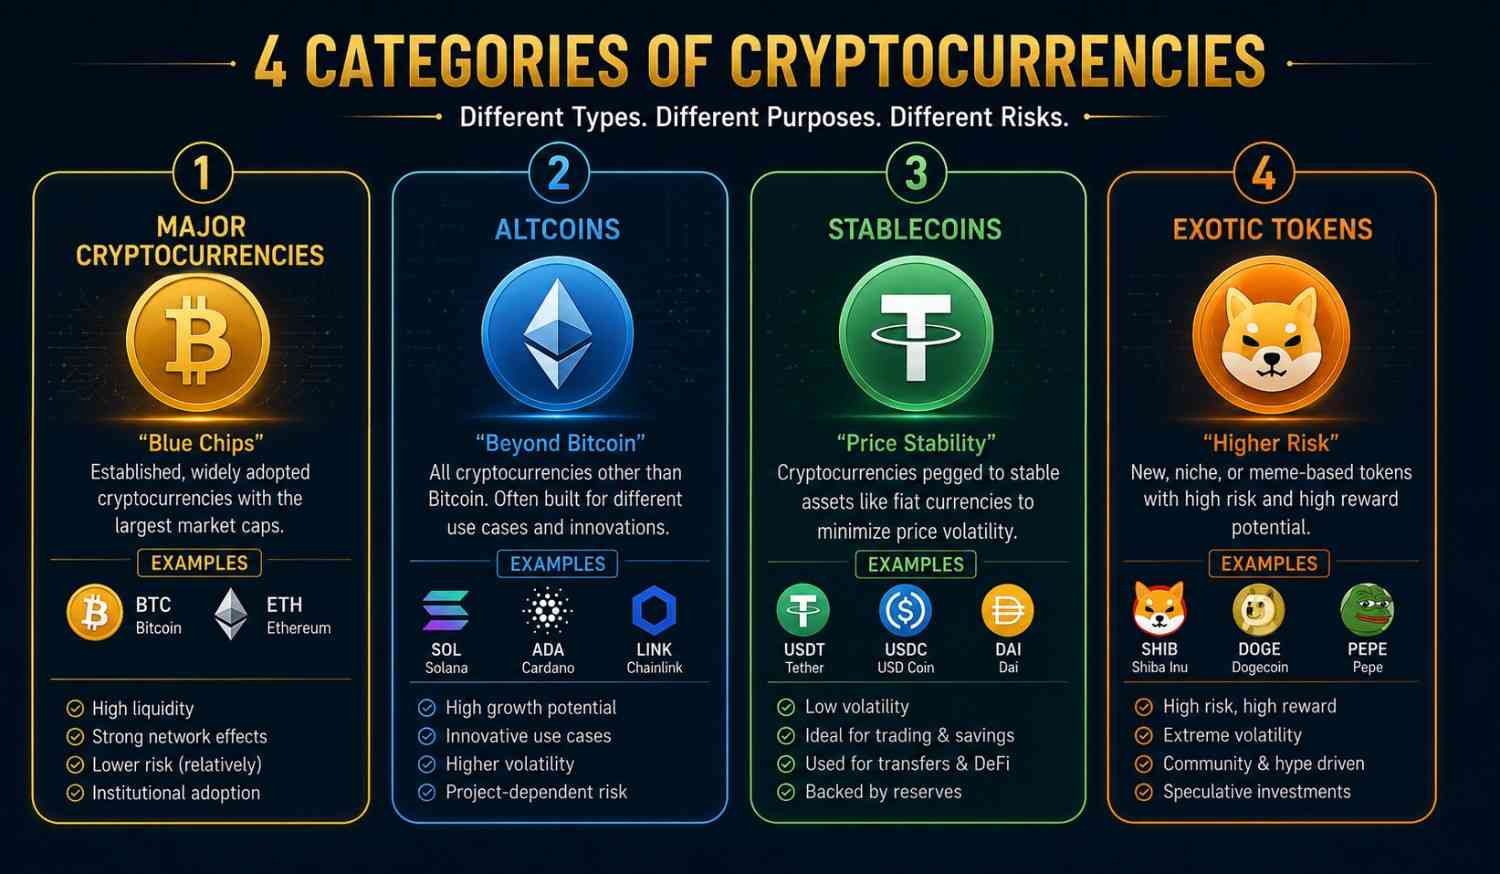
Popular cryptocurrencies include:

  • Bitcoin (BTC)
  • Ethereum (ETH)
  • Solana (SOL)
  • XRP
  • Cardano (ADA)

Unlike national currencies, cryptocurrencies are decentralized and are not typically issued by central banks.

Their prices are influenced by factors such as:

  • Market sentiment
  • Adoption rates
  • Network activity
  • Regulation
  • Technological developments
  • Institutional investment
  • Macroeconomic conditions

Crypto markets operate 24 hours a day, seven days a week, allowing continuous trading throughout the year.


Forex vs Crypto Trading: Why This Comparison Matters

Understanding Forex vs. Crypto Trading is essential because these markets behave differently, even though both involve buying and selling financial assets.

Choosing the wrong market for your personality can lead to unnecessary stress, inconsistent decision-making, and poor risk management.

For example:

  • Someone who prefers structured trading sessions and lower volatility may feel more comfortable in Forex.
  • Someone with a long-term outlook and an interest in blockchain innovation may prefer investing in cryptocurrencies.
  • An active trader might participate in both markets but apply different strategies to each.

In Forex vs Crypto Trading, the best choice depends less on hype and more on aligning your approach with your financial goals and level of experience.


Difference #1 โ€“ Market Size

In Forex vs Crypto Trading, the Forex market is the largest financial market in the world, with daily trading activity measured in the trillions of dollars.

The cryptocurrency market, while significantly smaller, has grown rapidly and continues to evolve as institutional participation increases.

What this means for beginners

Higher liquidity in Forex generally leads to:

  • More consistent pricing.
  • Lower transaction costs on major pairs.
  • Reduced likelihood of extreme price gaps during normal market conditions.

Crypto markets, by contrast, may experience larger price swings in shorter periods, creating both opportunities and additional risks.


Difference #2 โ€“ Liquidity

Liquidity refers to how easily an asset can be bought or sold without significantly affecting its price.

Major Forex pairs such as EUR/USD are among the most liquid instruments available.

Cryptocurrencies vary widely:

  • Bitcoin and Ethereum are highly liquid.
  • Smaller tokens may have much lower liquidity, increasing volatility and execution risk.

For beginners, understanding liquidity is important because it affects spreads, slippage, and the ability to enter or exit trades efficiently.


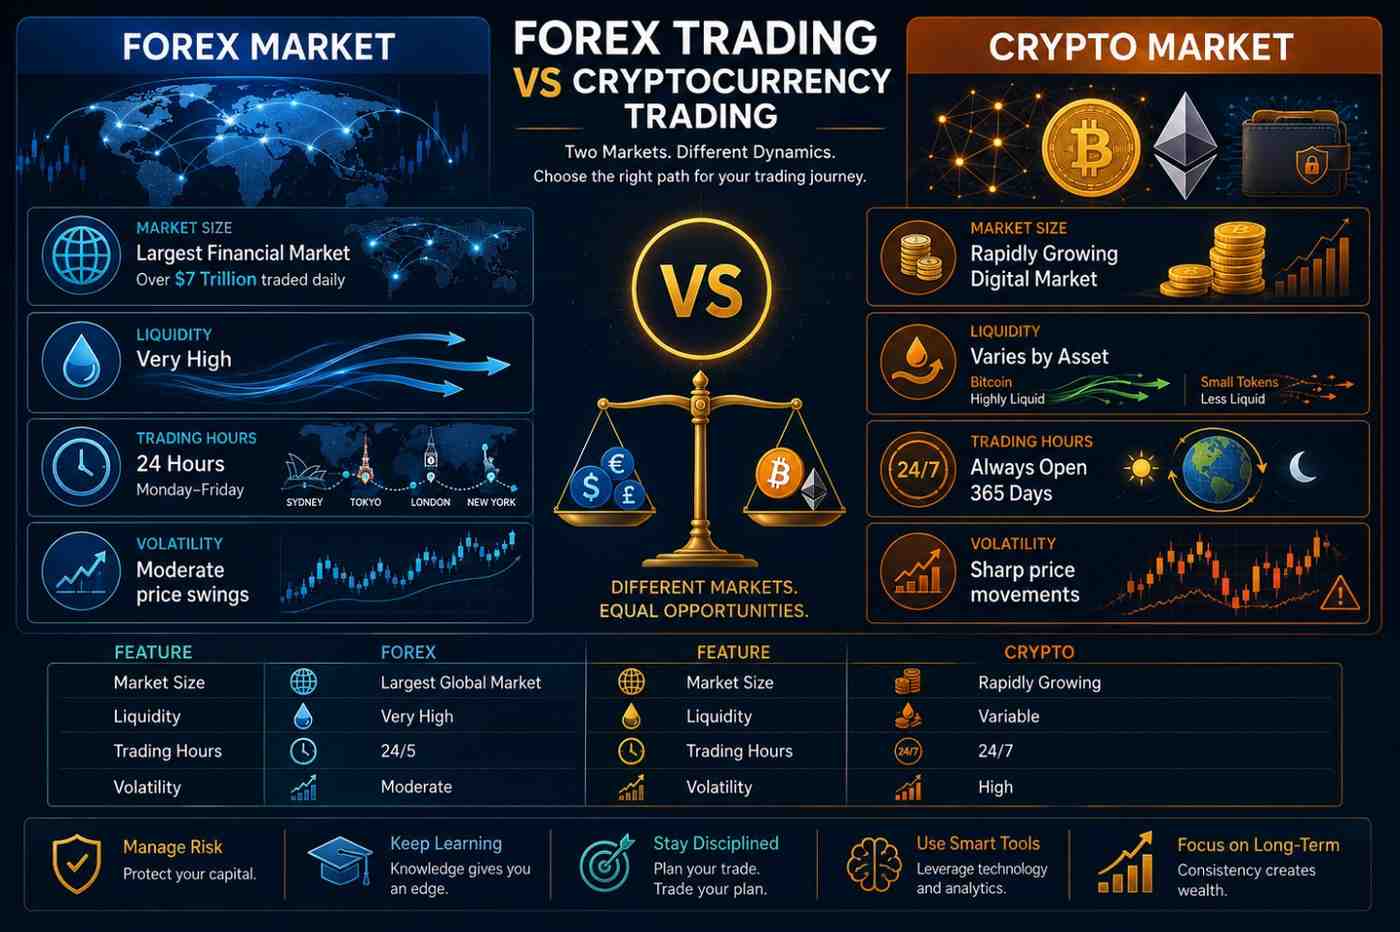
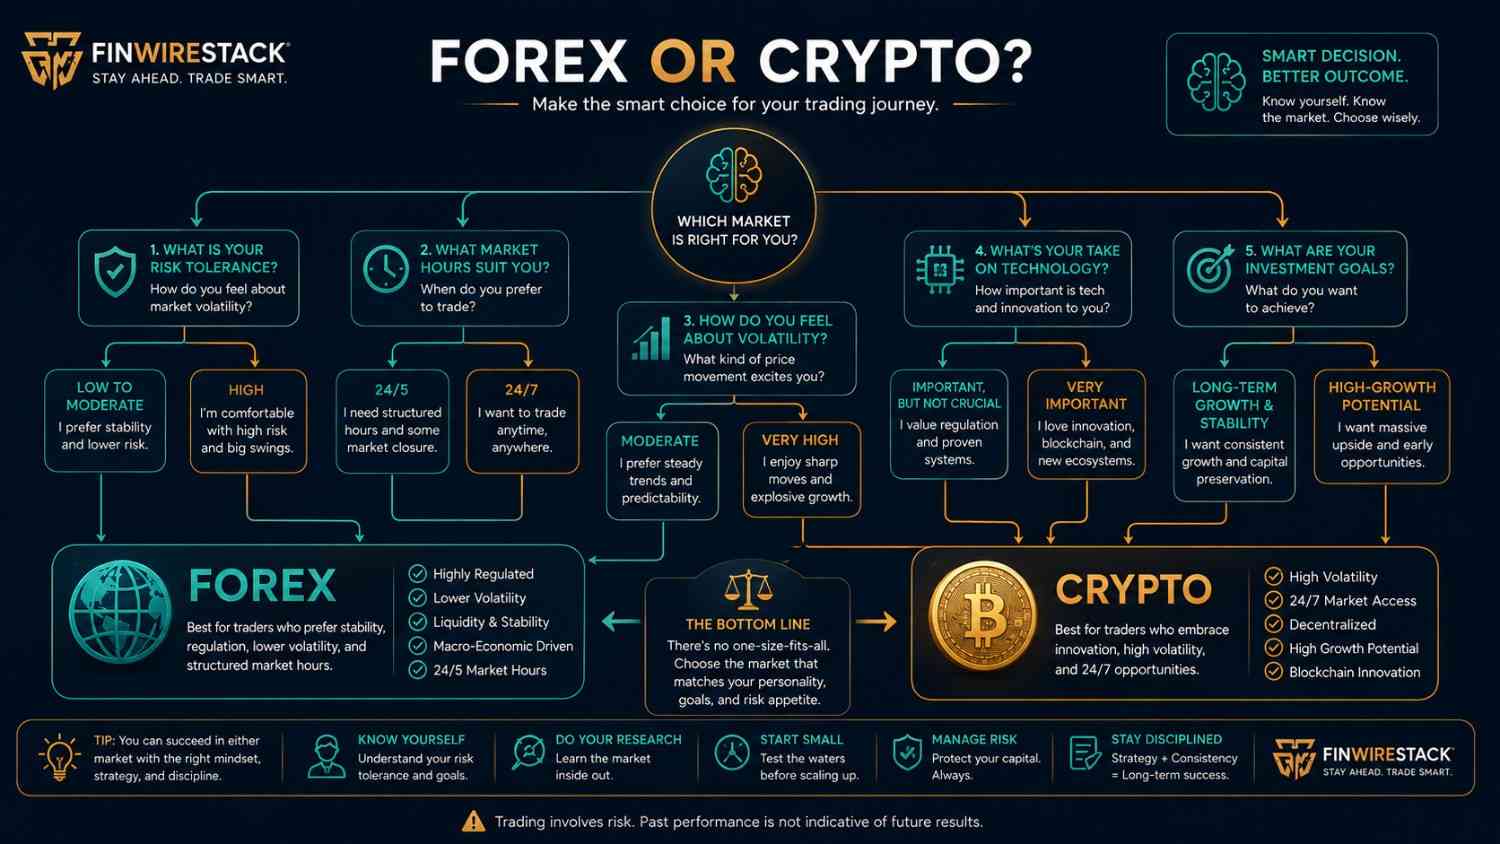
Decision tree helping beginners choose between Forex vs Crypto Trading based on goals, risk tolerance, and investment preferences.

You can also read on:


Difference #3 โ€“ Trading Hours

One of the biggest differences in Forex vs Crypto Trading is when you can trade.

“One of the biggest differences in Forex vs Crypto Trading is the schedule. Forex trading is available for 24 hours a day, five days a week, providing a structured routine. Crypto trading, however, runs 24 hours a day, 365 days a year, offering constant access but a greater need for discipline .”

Forex Trading Hours

The Forex market operates 24 hours a day, five days a week, beginning Monday morning in Sydney and closing Friday evening in New York.

The market moves through four major sessions:

Trading SessionMain Financial CenterCharacteristics
SydneyAustraliaLower volatility
TokyoJapanActive Asian markets
LondonUnited KingdomHighest trading volume
New YorkUnited StatesHigh liquidity and major news releases

The overlap between the London and New York sessions generally experiences the highest liquidity and trading activity.

Crypto Trading Hours

Unlike Forex, cryptocurrency markets never close.

Trading continues:

  • 24 hours per day
  • 7 days per week
  • 365 days a year

While continuous access creates flexibility, it also means markets can experience significant price movements overnight, during weekends, or while you’re away from your screen.

Which Is Better?

Forex offers more structured trading hours that may suit traders who prefer defined routines.

Crypto provides constant access but requires greater discipline to avoid overtrading.


Difference #4 โ€“ Volatility

Volatility measures how much prices move over a given period.

It is one of the most important considerations in Forex vs Crypto Trading.

Forex Volatility

Major currency pairs generally experience smaller daily price movements.

For example:

EUR/USD may move between 50โ€“120 pips during an average trading day.

These relatively stable movements allow traders to apply structured risk management strategies.

Crypto Volatility

Cryptocurrency prices can change dramatically within hours.

A digital asset may gain or lose 10โ€“20% in a single day during periods of heightened market activity.

While higher volatility creates opportunities for larger returns, it also increases the potential for substantial losses.

Which Market Is Safer?

Neither market is “safe.”

However, beginners often find Forex easier to manage because price movements tend to be less extreme than those in many cryptocurrencies.


Difference #5 โ€“ Regulation

Regulation is another major distinction in Forex vs. crypto trading.

Forex

Forex brokers in many jurisdictions operate under financial regulators designed to protect investors and promote fair market practices.

Examples include:

  • U.S. Commodity Futures Trading Commission (CFTC)
  • National Futures Association (NFA)
  • UK Financial Conduct Authority (FCA)
  • Australian Securities and Investments Commission (ASIC)

Regulation often includes requirements related to:

  • Client fund segregation
  • Capital requirements
  • Transparency
  • Complaint procedures

Cryptocurrency

Regulation varies considerably across countries.

Some jurisdictions have established comprehensive frameworks for digital assets, while others continue to develop or revise regulations.

As a result, investors should carefully evaluate exchanges and understand the legal environment in their country before investing.


Difference #6 โ€“ Leverage

Leverage allows traders to control larger positions with a smaller amount of capital.

Forex

Depending on local regulations, leverage may be available, but limits differ across jurisdictions.

While leverage can increase potential returns, it also magnifies potential losses.

Crypto

Some cryptocurrency platforms also offer leveraged products.

However, because cryptocurrencies are often more volatile than major currency pairs, combining high leverage with rapid price movements can significantly increase risk.

Beginner Recommendation

Before considering leverage, develop a solid understanding of risk management and practice with conservative position sizes.

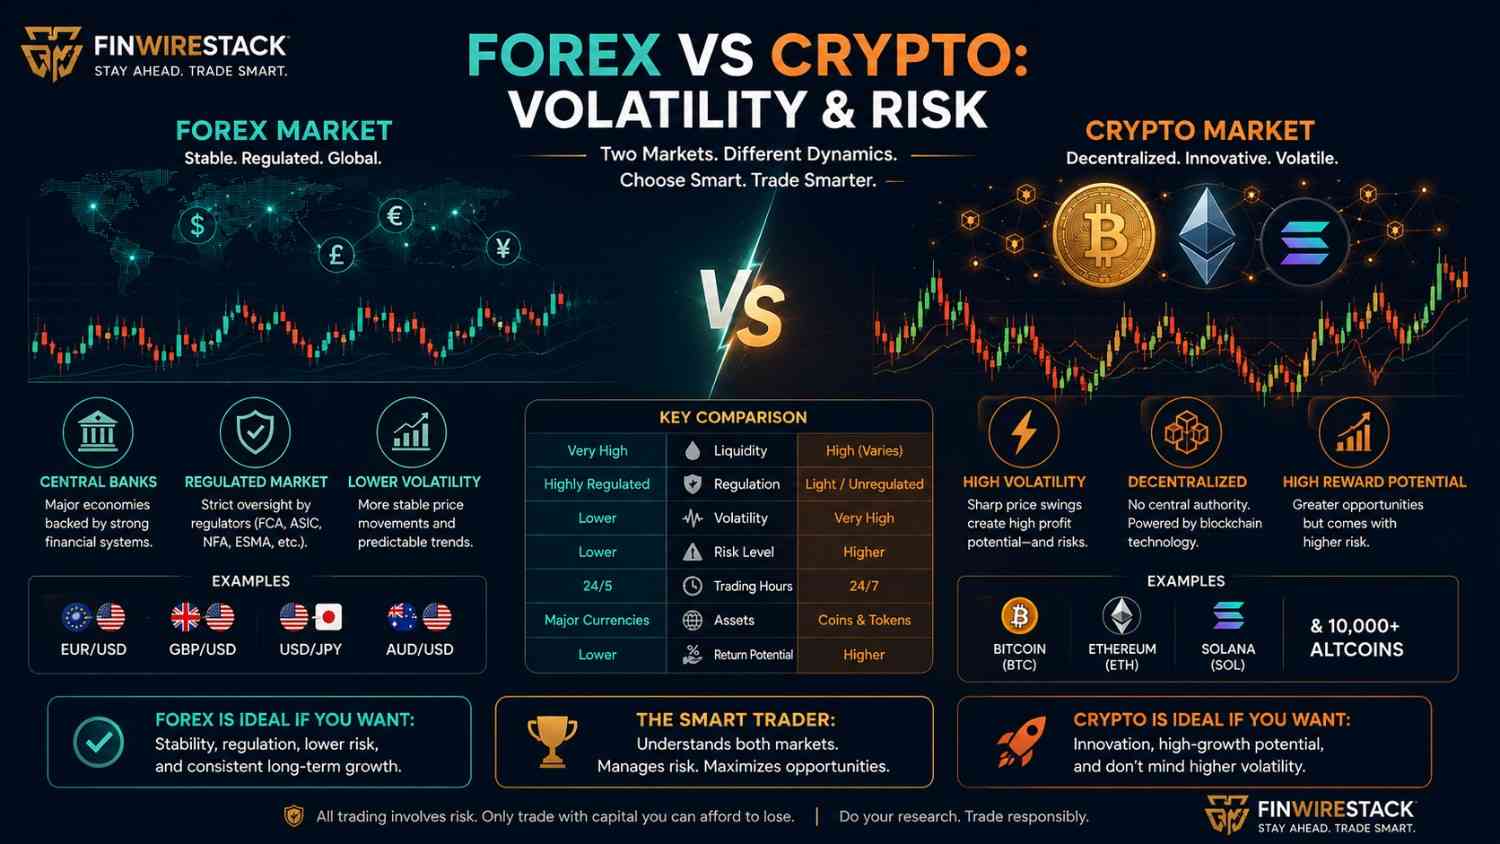
Forex vs Crypto Trading comparison showing differences in volatility, leverage, regulation, and market risk for beginners.


Difference #7 โ€“ Technology

Technology has transformed both markets, but in different ways.

Forex Technology

Modern Forex platforms provide:

  • Advanced charting
  • Economic calendars
  • Market scanners
  • Mobile trading apps
  • Algorithmic trading support
  • AI-assisted analysis

Crypto Technology

Cryptocurrency is built on blockchain technology.

Investors often interact with:

  • Digital wallets
  • Smart contracts
  • Decentralized finance (DeFi)
  • Tokenization
  • Layer-2 scaling solutions
  • Blockchain explorers

Learning blockchain concepts is an additional step for many new crypto investors.


Difference #8 โ€“ Market Drivers

Understanding why prices move is fundamental to Forex vs Crypto Trading.

Forex Prices Respond To
  • Interest rate decisions
  • Inflation
  • GDP growth
  • Employment reports
  • Central bank speeches
  • International trade
  • Geopolitical developments
Crypto Prices Respond To
  • Market sentiment
  • Network adoption
  • Blockchain upgrades
  • Institutional investment
  • Regulatory announcements
  • Security incidents
  • Supply and demand dynamics

Forex is generally driven by macroeconomics, while crypto is influenced by a combination of technology, adoption, and investor sentiment.


Difference #9 โ€“ Learning Curve

The learning process differs between the two markets.

Forex Requires Understanding
  • Currency pairs
  • Economic indicators
  • Central banks
  • Interest rates
  • Technical analysis
  • Risk management
Crypto Requires Understanding
  • Blockchain technology
  • Wallet security
  • Exchanges
  • Private keys
  • Smart contracts
  • Tokenomics
  • Decentralized finance

Neither market is inherently easier, but they emphasize different knowledge areas.


Difference #10 โ€“ Long-Term Investing

Many beginners ask whether they should trade actively or invest for the long term.

Forex

Forex is primarily associated with active trading.

Long-term currency investing is less common for retail participants.

Crypto

Many investors choose long-term strategies by purchasing established cryptocurrencies and holding them over extended periods.

This approach, often called long-term investing, differs significantly from active trading.


Difference #11 โ€“ Profit Potential

Both Forex and Crypto offer profit opportunities.

However, profitability depends far more on:

  • Education
  • Discipline
  • Risk management
  • Consistency
  • Emotional control

No market guarantees success.

Likewise, no market guarantees losses.

The trader’s decisions play a central role in long-term outcomes.


Difference #12 โ€“ Artificial Intelligence Is Transforming Forex vs Crypto Trading

Artificial Intelligence (AI) has become one of the biggest technological trends shaping financial markets. Whether you’re comparing Forex vs Crypto Trading, AI is changing how traders analyze data, manage risk, and make decisions.

However, it’s important to understand what AI canโ€”and cannotโ€”do.

AI is not a guaranteed profit machine. It cannot predict the future with certainty or eliminate the risks of trading. Instead, it acts as a powerful assistant that helps traders process information more efficiently.

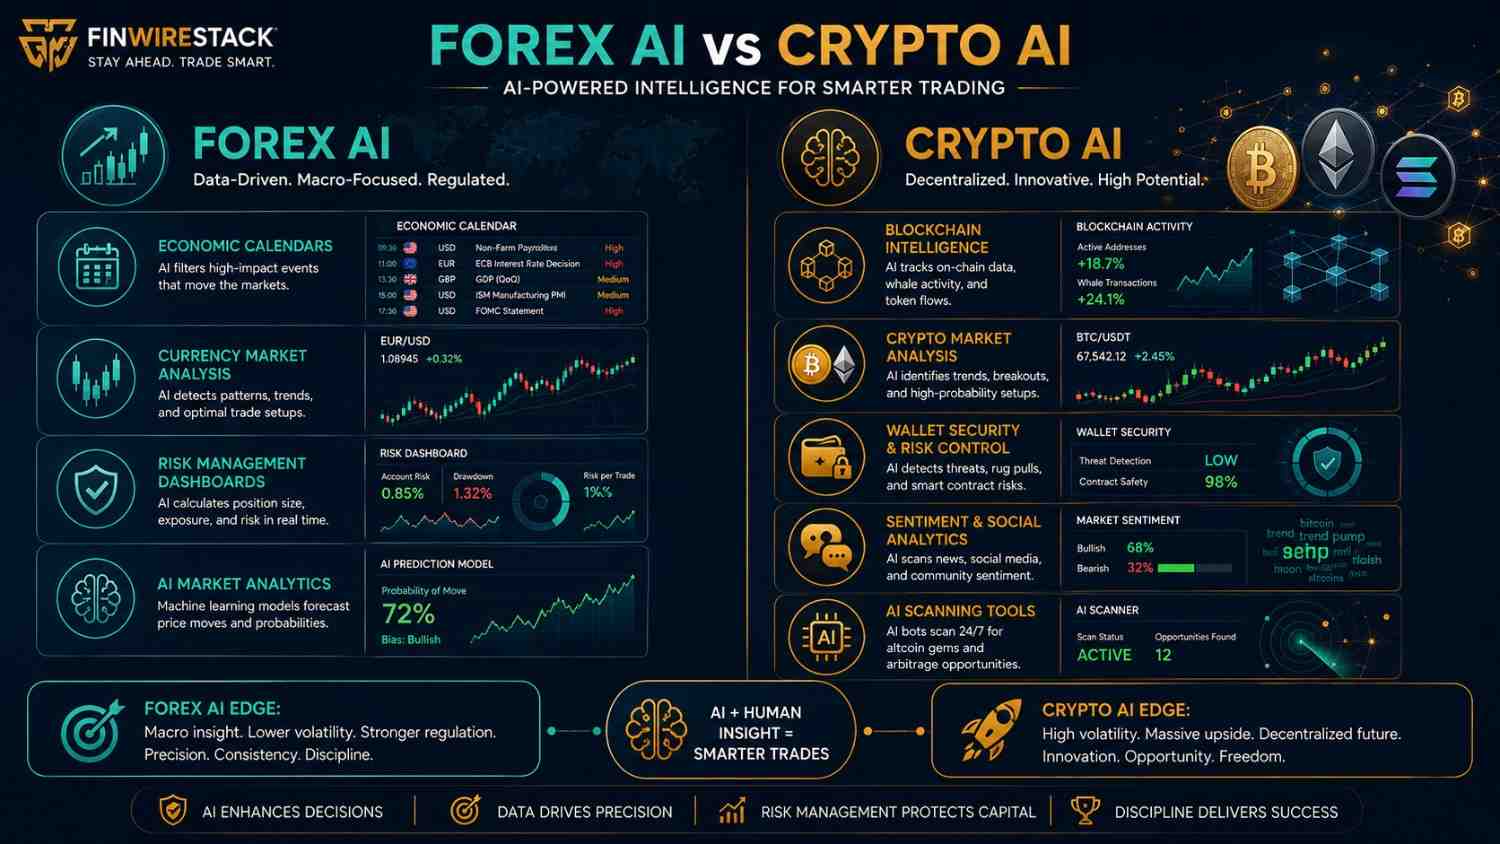
How AI Is Used in Forex Trading

Professional Forex traders increasingly use AI to:

  • Analyze large amounts of market data.
  • Detect technical chart patterns.
  • Summarize economic news.
  • Monitor multiple currency pairs simultaneously.
  • Identify unusual market volatility.
  • Improve trading journals through performance analytics.
  • Support risk management decisions.

AI can save time, but it should complementโ€”not replaceโ€”a well-defined trading plan.

How AI Is Used in Crypto Trading

The cryptocurrency market also benefits from AI, particularly because it operates continuously.

Common applications include:

  • Blockchain analytics.
  • Sentiment analysis from news and social media.
  • Portfolio optimization.
  • Fraud detection.
  • Automated trading alerts.
  • Market screening across thousands of digital assets.

Because crypto markets can move rapidly, AI tools can help investors filter large volumes of information more efficiently.

A Word of Caution

Be skeptical of anyone claiming:

  • “AI guarantees profits.”
  • “This bot never loses.”
  • “Our algorithm is 100% accurate.”

No legitimate investment tool can make such promises. Successful trading still depends on education, discipline, and sound risk management.


Difference #13 โ€“ Common Scams in Forex vs Crypto Trading

Unfortunately, both markets attract fraudsters who prey on beginners. Understanding common scams is one of the most valuable lessons in Forex vs Crypto Trading.

Fake Investment Managers

Scammers promise to trade on your behalf and guarantee extraordinary returns.

Warning signs include:

  • Guaranteed profits.
  • Pressure to invest immediately.
  • Refusal to explain their strategy.
  • Requests to send money directly to personal accounts.

Remember: no legitimate investment professional can guarantee profits.

Fake Brokers

Some websites appear to be professional trading platforms but are designed to steal deposits.

Always verify whether a broker is regulated before opening an account.

Signal Selling Scams

Some individuals sell “VIP signals” claiming exceptionally high win rates.

While educational services can provide value, be cautious of anyone advertising unrealistic success rates or luxury lifestyles as proof of expertise.

Pump-and-Dump Schemes

This scam is more common in cryptocurrencies.

Fraudsters promote a little-known token, encourage people to buy, then sell their own holdings after the price risesโ€”leaving late buyers with heavy losses.

Phishing Attacks

Criminals create fake login pages, emails, or messages designed to steal passwords or wallet credentials.

Protect yourself by:

  • Using strong passwords.
  • Enabling two-factor authentication (2FA).
  • Verifying website addresses before logging in.
  • Never sharing private keys or recovery phrases.

Difference #14 โ€“ Risk Management

Whether you choose Forex or Crypto, risk management remains the foundation of long-term success.

Key Principles

Never Risk Money You Cannot Afford to Lose

Trading capital should be separate from funds needed for essential living expenses or emergencies.

Diversify When Appropriate

Avoid placing all your capital into a single asset or trade.

Use Stop-Loss Orders.

A stop-loss helps limit potential losses if the market moves against your position.

Keep Position Sizes Reasonable

Many experienced traders risk only a small percentage of their account on any single trade.

Continue Learning

Markets evolve continuously. Staying informed helps improve decision-making over time.


Difference #15 โ€“ Which Market Is Better for Beginners?

There is no universal answer to the Forex vs. Crypto Trading debate. The right choice depends on your goals, experience, and comfort with risk.

Forex May Be a Better Fit If You:

  • Prefer structured market hours.
  • Enjoy following global economic news.
  • Want lower day-to-day volatility.
  • Like analyzing macroeconomic trends.
  • Prefer established financial markets.

Crypto May Be a Better Fit If You:

  • Are interested in blockchain technology.
  • Can tolerate higher volatility.
  • Prefer markets that operate 24/7.
  • Have a long-term interest in digital assets.
  • Want to learn about decentralized finance and emerging technologies.

Some Investors Choose Both

Many experienced investors participate in both markets while applying different strategies and maintaining appropriate diversification.

The key is understanding the unique risks and opportunities of each rather than treating them as interchangeable.


Side-by-Side Comparison

FeatureForex TradingCrypto Trading
Market Hours24 hours, 5 days24 hours, 7 days
Main AssetsNational currenciesDigital assets
Typical VolatilityModerateHigher
LiquidityVery high (major pairs)Varies by asset
Primary DriversEconomics, interest rates, central banksAdoption, technology, sentiment, regulation
RegulationGenerally more establishedVaries by jurisdiction
AI ApplicationsMarket analysis, risk managementAnalytics, blockchain data, portfolio tools
Beginner Learning FocusEconomics, technical analysisBlockchain, wallets, digital security

Comparison of AI tools used in Forex vs Crypto Trading, including market analysis, blockchain analytics, and risk management.

Real-World Example

Imagine two beginners, Sarah and David.

Sarah enjoys reading economic news, follows central bank announcements, and prefers a structured routine. She chooses Forex trading and practices on a demo account while learning risk management.

David is fascinated by blockchain technology, understands digital wallets, and is comfortable with higher volatility. He decides to invest gradually in established cryptocurrencies while continuing to educate himself about security and market dynamics.

Neither approach is inherently better. What matters is that each person selected a market aligned with their interests, goals, and risk tolerance.


Frequently Asked Questions About Forex vs. Crypto Trading

Is Forex vs. Crypto Trading better for beginners?

Forex vs. Crypto Trading depends on your experience, goals, and risk tolerance. Many beginners find Forex easier because it offers higher liquidity, more established regulation in many jurisdictions, and lower day-to-day volatility than many cryptocurrencies. However, crypto may appeal to those interested in blockchain technology and long-term digital asset investing.


Can I trade both Forex and Crypto?

Yes. Many experienced investors participate in both markets.

For example:

  • Forex for active trading and short-term opportunities.
  • Crypto as part of a diversified long-term investment strategy.

The key is to avoid overexposure and ensure each investment fits your overall financial plan.


Which market is more profitable?

Neither market guarantees profits.

Success depends on:

  • Education
  • Risk management
  • Emotional discipline
  • Trading strategy
  • Continuous learning

A disciplined trader in either market is generally better positioned than someone chasing unrealistic returns.


Is crypto riskier than Forex?

In many cases, in Forex vs. Crypto Trading, cryptocurrencies experience greater price volatility than major Forex pairs.

Higher volatility can create larger opportunitiesโ€”but also larger losses.

This is why position sizing and risk management are especially important in crypto markets.


Does AI make Forex vs. crypto trading easier?

Artificial Intelligence can improve efficiency by helping traders analyze charts, monitor news, and organize data.

However:

AI does not eliminate investment risk.

Successful traders continue to rely on:

  • Independent research
  • Risk management
  • Experience
  • Sound judgment

How much money should I start with?

Only invest money you can afford to lose.

Beginners should prioritize:

  • Education
  • Demo accounts (where available)
  • Developing a written trading plan
  • Building consistent habits

Starting small while learning is generally more sustainable than committing large sums too early.


Decision Framework: Should You Choose Forex or Crypto?

Ask yourself these questions:

Do you enjoy following global economic news?

If yes, Forex may align with your interests.


Are you fascinated by blockchain technology?

If yes, Crypto may be a better fit.


Do you prefer structured market hours?

Forex offers trading five days a week with well-defined market sessions.


Do you want a market that never closes?

Crypto trades 24 hours a day, seven days a week.


Are you comfortable with significant price swings?

If not, Forex may feel more manageable.

If you accept higher volatility in pursuit of potentially larger price movements, crypto may better match your risk tolerance.


Do you plan to become a professional trader?

Many professionals eventually understand both markets because global finance is increasingly interconnected.

Learning the strengths and weaknesses of each can broaden your perspective and create more opportunities over time.


Decision tree helping beginners choose between Forex vs Crypto Trading based on goals, risk tolerance, and investment preferences.

Key Takeaways on Forex vs Crypto Trading.

When comparing Forex vs Crypto Trading, remember these important lessons:

โœ” Forex is generally more liquid.

โœ” Crypto typically experiences greater volatility.

โœ” Both require education and disciplined risk management.

โœ” AI can improve analysis but cannot guarantee profits.

โœ” Scams exist in both markets.

โœ” Successful investors focus on long-term skill development rather than short-term excitement.

โœ” The best market is the one that aligns with your goals, knowledge, and financial circumstances.


Expert Tips for New Traders

If you’re just beginning your journey, consider these practical steps:

  1. Build a solid foundation by learning the basics before investing real money.
  2. Practice with a demo account if you’re exploring Forex.
  3. Start with established cryptocurrencies if you’re interested in digital assets.
  4. Keep a trading or investment journal.
  5. Stay informed through trusted financial news and educational resources.
  6. Never rely solely on social media influencers for financial decisions.
  7. Review your performance regularly and learn from both successes and mistakes.

Consistency and continuous learning often

matter more than trying to find the “perfect” strategy.


Final Thoughts

The debate surrounding Forex vs. Crypto Trading will continue as financial markets evolve.

Rather than asking which market is universally better, ask which market is better for you.

Forex provides access to the world’s largest financial market, where economic data, central bank decisions, and global events shape currency prices.

Crypto offers exposure to innovative blockchain technology and digital assets that continue to transform finance.

Both markets reward preparation.

Both markets punish poor risk management.

Both markets require patience, discipline, and ongoing education.

As AI, financial technology, and global investing continue to evolve, the individuals who succeed will be those who commit to lifelong learning rather than chasing shortcuts.

At FinWireStack, our goal is to help you become one of those informed investors.


Modern investor confidently managing a diversified portfolio that includes Forex and cryptocurrency with AI-assisted analytics.

๐Ÿ“š Sources and Further Reading

This guide on Forex vs. Crypto Trading was built using insights from a variety of reputable sources to ensure accuracy and depth. For further reading, please explore the links below:

  1. Investopedia. “Forex Market: Who Trades Currencies and Why.” https://www.investopedia.com/terms/forex/f/forex-market.asp
  2. Investopedia. “Cryptocurrency: What It Is and How It Works.” https://www.investopedia.com/terms/c/cryptocurrency.asp
  3. Commodity Futures Trading Commission (CFTC). “Customer Advisory: Beware of Foreign Exchange (Forex) Trading Frauds.” https://www.cftc.gov/LearnAndProtect/AdvisoriesAndArticles/ForexFraud/index.htm. Forex vs Crypto Trading
  4. U.S. Securities and Exchange Commission (SEC). “Investor Alert: Public Companies Making Cryptocurrency-Related Claims.” https://www.sec.gov/oiea/investor-alerts-and-bulletins/ib_publiccompaniescrypto
  5. Financial Conduct Authority (FCA). “Cryptocurrency: What You Need to Know.” https://www.fca.org.uk/consumers/cryptocurrencies. Forex vs Crypto Trading
  6. Bank for International Settlements (BIS). “Annual Economic Report 2024: The Future of Money and Payments.” https://www.bis.org/publ/arpdf/ar2024e.htm
  7. International Monetary Fund (IMF). “The Crypto Ecosystem and Financial Stability Challenges.” https://www.imf.org/en/Publications/fintech-notes/Issues/2024/01/19/The-Crypto-Ecosystem-and-Financial-Stability-Challenges-545421
  8. Forbes. “What Is Artificial Intelligence (AI) In Trading?” https://www.forbes.com/advisor/investing/ai-trading/. Forex vs Crypto Trading

โœ๏ธ About the Author

FinWireStack Team

FinWireStack is a dedicated platform for financial education and smart money decisions. Our mission is to empower individuals with the knowledge and tools they need to navigate complex financial markets with confidence. We focus on providing clear, actionable, and unbiased content to help you achieve your financial goals. Our team of researchers and writers is committed to demystifying finance and investing for a global audience.


๐Ÿ“ข Share This Article

If you found this Forex vs Crypto Trading guide helpful, please consider sharing it with others who might benefit from understanding the critical differences between Forex and crypto trading.

Crypto Trading 101: A Beginner’s Guide to Digital Assets in 2026

Cryptocurrency trading for beginners featured image showing Bitcoin Ethereum and altcoin trading with step-by-step guide for 2026

Cryptocurrency trading has evolved far beyond its early experimental phase. In 2026, learning how to trade crypto means navigating a mature financial ecosystem shaped by institutional participation, clearer regulations, advanced trading infrastructure, and growing tax responsibilities. Since Bitcoin launched in 2009, the industry has evolved rapidly to offer a wide range of trading products, attracting millions of new participants each year.

The cryptocurrency market is one of the fastest-growing areas of finance. The total market cap of all cryptocurrencies combined passed $4 trillion for the first time in July 2025, according to data from CoinGecko, signaling increasing interest from both retail and professional investors. With the introduction of the CLARITY Act and the GENIUS Act in late 2025, the United States moved from regulatory uncertainty toward a more structured framework for digital assets.

This comprehensive guide will teach youย crypto trading for beginnersย from the ground up. You will learn:

  • What cryptocurrency trading is and how it differs from investing
  • How crypto trading pairs work (base vs. quote currency)
  • How to choose the right exchange and set up your account
  • Where to start and how to place your first trade
  • Which strategies work best for beginners
  • How to manage risk and protect your assets
  • Common mistakes to avoid

By the end, you will understandย crypto trading for beginnersย well enough to start your journey with confidence.


Cryptocurrency trading for beginners types of cryptocurrencies showing Bitcoin Ethereum altcoins stablecoins and exotic tokens with market cap examples

Cryptocurrency trading for beginners โ€” understanding the basics of digital asset trading in 2026


What is Crypto Trading?

Cryptocurrency trading for beginnersย starts with understanding what it actually means. Crypto trading is the active buying and selling of digital assets like Bitcoin, Ethereum, or other coins and tokens to profit from price movements.

Unlike traditional financial markets that operate on fixed schedules, the cryptocurrency market runs 24 hours a day, seven days a week, across every time zone. This results in more opportunities to respond to price changes but also requires constant vigilance.

Crypto Trading vs. Investing

AspectTradingInvesting
Time HorizonMinutes, hours, days, or weeksMonths or years
GoalProfit from short-term price movementsCapture long-term gains and exposure
Activity LevelFrequent buying and sellingBuy and hold strategy
Risk ProfileHigher due to frequent decisionsLower due to long-term holding
Skills RequiredTechnical analysis, quick decision-makingFundamental analysis, patience

๐ŸŽฏ Real-World Analogy:ย Crypto trading is like being a day trader in the stock market, constantly watching charts and making quick decisions. Investing in crypto trading is like buying a house and holding it for years, hoping it appreciates over time.


How Cryptocurrency Trading Works

Crypto Trading Pairs

A crypto trading pair represents two different digital assets that can be exchanged for one another on a trading platform. For example, when BTC/USDT appears on an exchange, it means you can trade Bitcoin for Tether (and vice versa) directly on that platform.

Every trading pair consists of two parts:

  • Base currency:ย The first listed cryptocurrency in the pair (what you are buying or selling)
  • Quote currency:ย The second listed cryptocurrency (what you are using to conduct the transaction)

For instance, in the ETH/BTC pair, Ethereum (ETH) is the base currency, while Bitcoin (BTC) is the quoted currency. The price shows how many BTC are needed to purchase one ETH.

Common Trading Pair Examples:

TypeExampleDescription
Stablecoin PairsBTC/USDT, ETH/USDCPairs involving stablecoins pegged to fiat currencies
Bitcoin PairsBTC/ETH, BTC/ADATrading pairs with Bitcoin as base or quote
Ethereum PairsETH/ADA, ETH/LINKPairs featuring Ethereum as base or quote

How Orders Work

When you trade crypto, you place orders through a cryptocurrency exchange interface.

The two most common order types are the following:

  1. Market Order:ย Executes immediately at the current price. This is fast but can result in price slippage.
  2. Limit Order:ย Only executes if the price reaches a level you specify. This offers more control but may not go through if the price never reaches your target.

๐ŸŽฏ Real-World Example: If BTC/USDT shows a buy price of $90,000 and a sell price of $89,950, the spread is $50. If you buy at $90,000 and later sell at $91,000, your profit of $1,000 will be slightly reduced by the exchange fees.


Cryptocurrency trading for beginners trading pairs explained showing base currency quote currency and common pair types like BTC/USDT and ETH/BTC.

Caption: Figure 2: Understanding crypto trading pairs โ€” the foundation of cryptocurrency trading for beginners


Types of Cryptocurrencies to Trade

Major Cryptocurrencies (“Blue Chips”)

These are the most established and actively traded cryptocurrencies, usually having high trading volumes and strong market presence. Examples include:

  • Bitcoin (BTC):ย The largest and world’s first digital currency, often considered a store of value or “digital gold.”
  • Ethereum (ETH):ย Supports smart contracts and decentralized finance (DeFi) applications
  • Binance Coin (BNB),ย Solana (SOL),ย Ripple (XRP)

Altcoins

An “altcoin” is any cryptocurrency that is not Bitcoin. Some altcoins have large communities and practical uses, while others are more speculative. Examples include Cardano (ADA), Avalanche (AVAX), Polkadot (DOT), Chainlink (LINK), and Polygon (MATIC).

Stablecoins

Stablecoins are cryptocurrencies linked to stable assets, such as the U.S. dollar, to minimize price volatility. They are often used as trading pairs and for quickly moving funds between exchanges. Examples include Tether (USDT), USD Coin (USDC), and Dai (DAI).

Exotic or Niche Tokens

These are tokens from smaller projects, meme coins, or assets linked to specific ecosystems. They usually have lower trading volumes and can be more volatile, making them riskier for beginners. Examples include Shiba Inu (SHIB) and Pepe (PEPE).

๐ŸŸฆ Blue Highlight: As a beginner, start trading with major cryptocurrencies paired with stablecoins or USD (like BTC/USDT or ETH/USD). These pairs are easier to work with and typically incur lower costs.


Cryptocurrency trading for beginners types of cryptocurrencies showing Bitcoin Ethereum altcoins stablecoins and exotic tokens with market cap examples

Figure 3: Cryptocurrency types โ€” understanding the different categories of digital assets


How to Start Trading Crypto

Getting started withย crypto trading for beginnersย doesn’t have to be complicated. Here is a simple step-by-step guide.

Step 1: Choose a Reliable Exchange

Pick a trustworthy cryptocurrency exchange with a good reputation. Look for platforms that are regulated in your area or have strong security measures. The top cryptocurrency exchanges offer deep liquidity, advanced trading features, and access to a broad range of digital assets.

Platform TypeBest ForProsCons
Centralized Exchange (CEX)Beginners and active tradersUser-friendly, deep liquidity, advanced featuresHold custody of your funds
Decentralized Exchange (DEX)Advanced users wanting privacyControl of funds, stronger privacyLess beginner-friendly, lower liquidity
Broker/CFD PlatformTraditional tradersLeverage, short selling, familiar environmentIndirect exposure, no ownership
Payment AppsSimple starter positionsExtremely easy to use, quick setupHigher spreads, limited features

What to look for in a platform:

  • Two-factor authentication and cold storage protection
  • Transparent fee structure
  • Strong liquidity and valid regulatory licenses
  • User-friendly interface and real-time price displays

Step 2: Create and Verify Your Account

Once you have chosen a platform, you will need to create an account. Most exchanges require you to complete KYC (Know Your Customer) checks, which involve providing proof of your identity and address. This legally required process is designed to prevent money laundering and fraud.

Typical verification steps:

  1. Enter your personal information and choose a secure password
  2. Enable two-factor authentication for security
  3. Upload a valid form of ID and confirm your identity via video identification or a selfie
  4. Provide proof of address (sometimes required)

Step 3: Fund Your Account

After verification, you can deposit funds in fiat currencies such as euros or US dollars. Platforms often offer several deposit methods, such as bank transfer, credit card, or other payment services.

Be aware of:

  • Possible fees and processing times
  • Minimum deposit requirements (often $10-100)
  • Currency conversion costs if depositing in a different currency

Step 4: Secure a Wallet

Understanding crypto wallets remains essential, especially if you plan to move assets off-platform.

Wallet TypeDefinitionBest For
Hot WalletConnected to the internet (browser extensions or mobile apps)Active traders who need instant access
Cold WalletStores private keys completely offline (hardware devices)Long-term storage of larger holdings
Exchange WalletBuilt-in wallet provided by the exchangeConvenience for active crypto trading

๐ŸŸฆ Blue Highlight: If you are actively trading, keeping assets on an exchange can be practical. But if you are holding long-term, security becomes an important consideration. A more practical approach is to keep a smaller “trading balance” on-platform and move longer-term holdings off-platform.

Step 5: Pick Your First Crypto Pair

Start trading with major cryptocurrency pairs like BTC/USDT or ETH/USD. These pairs are easier to trade and more beginner-friendly.

Characteristics of good beginner pairs:

  • High liquidity for stable trading conditions
  • High trading volumes for better price execution
  • More predictable and easier to analyze

Step 6: Place Your First Trade

Once you have funded your account, placing a trade is usually straightforward.

Before executing your first trade:

  1. Choose your trading approach (active or automated trading)
  2. Start with a small amount you can afford to lose
  3. Monitor your trading position closely
  4. Keep detailed records of all trades, including entry price, exit price, and reasoning behind each decision

Step 7: Manage Your Risk

Risk management is the cornerstone of successful crypto trading, separating profitable traders from those who struggle to maintain their capital.

Key risk management practices:

  • Use stop-loss orders to limit potential losses
  • Implement proper position sizing (1-2% of total capital)
  • Maintain favorable risk-reward ratios
  • Diversify across multiple cryptocurrencies

Cryptocurrency trading for beginners step by step guide showing exchange selection account setup wallet security and first trade execution

How to start trading crypto โ€” a step-by-step guide for beginners


Trading Strategies for Beginners

There is no single right way to do crypto trading, but some approaches are more common among those starting.

1. Dollar-Cost Averaging (DCA)

Dollar-cost averaging is a concept that will resonate with investors who have been in the stock market for a while, even if they are new to crypto trading. Instead of trying to predict the market, you invest a fixed amount regularly, regardless of price.

Why It Works: Over time, this averages out your costs and reduces the impact of volatility, turning crypto’s wild swings into opportunities for steady growth. It is like planting seeds consistently in a garden. Some days the soil is pricey. Other days it is a bargain. But you will harvest more in the long run.

2. Swing Trading

Swing trading focuses on capturing medium-term price movements over several days or weeks. Traders use technical analysis tools such as candlestick patterns, moving averages, support and resistance zones, and momentum indicators to identify potential entry and exit points.

Key Indicators for Swing Trading:

  • Relative Strength Index (RSI)ย โ€” Measures momentum and identifies overbought/oversold conditions
  • Moving Average Convergence Divergence (MACD)โ€”Identifies trend momentum and possible reversals
  • Support and Resistance Levelsย โ€” Key price areas where trends may pause or reverse

3. Position Crypto Trading (Long-Term)

Position trading, often called buy-and-hold investing, focuses on the belief that selected cryptocurrencies will increase substantially in value over time. Traders using this strategy typically rely on fundamental analysis, evaluating factors such as technology, adoption rates, market capitalization, and regulatory positioning.

This method requires:

  • Patience and emotional discipline
  • Ability to withstand short-term market volatility
  • Focus on long-term fundamentals rather than daily price swings

4. Day Trading

Day trading involves opening and closing positions within the same trading day, aiming to capture intraday price movements. Crypto day traders rely heavily on technical analysis, market sentiment, and rapid reactions to news-driven volatility.

Important Considerations:

  • It requires time, focus, and a solid grasp of chart reading
  • Many beginners find it difficult to execute consistently
  • Best suited for highly liquid cryptocurrencies with strong trading volume

5. Copy Trading

Copy trading lets you automatically mirror the positions of an experienced trader. Rather than being a distinct trading product, it is a feature that allows you to gain market exposure while building your own skills.

Why It Can Work: It provides beginners with exposure to professional trading strategies without requiring extensive knowledge or experience. However, it is important to research the trader you are copying and understand their risk profile.

๐Ÿ’ก Pro Tip:ย The Arnold brothers from Altcoin Daily recommend, “To build wealth, set a clear strategyโ€”or rulesโ€”upfront, like predefined entry and exit points based on research, and stick to them no matter how the market feels. Invest with discipline, not with emotion.”


Cryptocurrency trading for beginners strategies comparison showing DCA swing trading position trading day trading and copy trading with risk levels

Five trading strategies for cryptocurrency beginnersโ€”find the approach that fits your lifestyle


Risk Management and Security

Long-term success in cryptocurrency trading depends heavily on effective risk management. The crypto market remains highly volatile, and while this volatility creates profit opportunities, it can also generate rapid and severe losses.

Position Sizing and Stop-Loss Discipline

A common rule among professional traders is to risk no more than 1-2% of total trading capital on a single position. This helps protect the account from significant damage after a losing trade. Stop-loss orders are equally important. By automatically closing positions at predefined levels, stop losses help limit losses during sudden market swings.

Diversification and Avoiding Emotional Mistakes

Diversifying across multiple cryptocurrencies with different risk characteristics can reduce exposure to a single asset collapse. However, excessive trading can increase fees and amplify unnecessary risk.

Psychological mistakes remain one of the most underestimated dangers in trading:

  • Refusing to close losing positions in the hope of a rebound can transform manageable losses into major setbacks
  • Buying into social-media hype without proper research has repeatedly led traders to poor decisions
  • Clearly defining your goals before entering any trade helps maintain discipline and reduce emotionally driven actions

Account Security

Security should never be treated as optional in crypto trading.

Essential Security Measures:

  • Two-factor authentication
  • Cold storage for significant holdings
  • Awareness of phishing scams imitating legitimate exchange websites, emails, and customer support channels
  • Never share seed phrases or login credentials in response to unsolicited messages

๐Ÿ”ด Red Highlight:ย Unlike traditional bank deposits, many crypto trading platforms offer no legal protection. If your exchange or wallet gets hacked or if you lose your private keys, you may lose your funds permanently.

Tax Considerations

In the U.S., the IRS generally treats crypto as property. That means selling crypto, trading one coin for another, or using crypto to buy something can all create taxable events.

Important Updates for 2026:

  • For transactions on or after Jan. 1, 2025, many brokers and centralized exchanges must now report digital asset sales to you and the IRS on Form 1099-DA
  • However, for tax year 2025 (forms sent in early 2026), most 1099-DAs will show proceeds but not cost basis
  • You still need your own records to track your actual gain or loss

๐Ÿ’ก Pro Tip: Maintain solid records across exchanges and wallets because “I will figure it out later” can turn into a nightmare when the April tax filing deadline is looming. Many traders use crypto tax software like CoinTracker or Koinly to consolidate transactions.


Common Mistakes When Trading Crypto

MistakeWhy It’s a ProblemHow to Fix
Over-LeveragingAmplifies losses, can lead to liquidationUse low or no leverage as a beginner
Trading Without a PlanEmotional decisions lead to lossesDefine entry, exit, and risk before every trade
FOMO (Fear of Missing Out)Buying at highs, selling at lowsStick to your strategy; avoid hype
Ignoring FeesTransaction costs eat into profitsCompare fee structures across platforms
Poor SecurityVulnerable to hacks and phishingUse 2FA, cold storage, and strong passwords
No Stop-LossSmall losses become large lossesAlways set stop-loss orders

Conclusion: Your Crypto Trading Journey Starts Here

Crypto trading for beginnersย is not about getting rich overnight. It is about building a solid foundation of knowledge, developing good habits, and managing risk consistently.

Key Takeaways:

  1. Understand the basicsโ€”Learn what crypto trading is and how it differs from investing
  2. Choose a regulated exchangeโ€”Protect your funds with a trustworthy platform
  3. Start smallโ€”Use small amounts you can afford to lose
  4. Use a simple strategyโ€”DCA or swing trading works well for beginners
  5. Manage your riskโ€”Use stop-loss orders and the 1-2% rule
  6. Secure your assetsโ€”Use two-factor authentication and cold storage for significant holdings
  7. Keep learningโ€”The crypto market changes quickly, and continuous education is essential

๐ŸŽฏ Final Thought:ย Like many people who follow personal finance topics, you are probably aware of cryptocurrency. But investing in crypto might seem like a game for younger, tech-savvy investors. Surprisingly, getting started in crypto trading is not as difficult as it might seem. By applying some of the same principles that make traditional investors successful, you can build real wealth in cryptoโ€”one smart step at a time.


FAQ

1. How do I start trading cryptocurrency as a beginner?

Choose a regulated exchange like Coinbase or Binance, create and verify your account, deposit funds, secure a wallet, pick a major trading pair like BTC/USDT, and start with small amounts. Always use stop-loss orders and risk management practices.

2. How much money do I need to start trading crypto?

You can start with as little as $10โ€“$100 on many platforms. The real question is not how much you need to startโ€”it is how much you are willing to risk. Starting small is a smart idea if you are new to crypto because it limits your possible losses while you learn the ropes.

3. What are crypto trading pairs?

A crypto trading pair represents two different digital assets that can be exchanged for one another. For example, BTC/USDT means you can trade Bitcoin for Tether. Each pair has a base currency (first) and a quote currency (second).

4. What is the best cryptocurrency for beginners?

Bitcoin and Ethereum are the best choices for beginners. They have the largest market capitalizations, strongest networks, and highest liquidity. They are also more predictable and easier to analyze than smaller altcoins.

5. Is crypto trading safe for beginners?

Crypto trading carries significant risks due to high volatility, security vulnerabilities, and a lack of deposit protection. However, with proper risk management (stop-loss orders, position sizing, secure wallets), beginners can trade safely while learning.

6. What is the 1% rule in crypto trading?

The 1% rule means you never risk more than 1-2% of your total trading capital on a single position. This helps protect your account from significant damage after a losing trade.

7. Are crypto trading profits taxable?

Yes, in many countries, including the U.S., the IRS generally treats crypto as property. Selling crypto, trading one coin for another, or using crypto to buy something can all create taxable events. Starting with tax year 2025, many exchanges must report digital asset sales to the IRS on Form 1099-DA.

8. What is dollar-cost averaging in crypto?

Dollar-cost averaging is investing a fixed amount regularly, regardless of price. This averages out your costs over time and reduces the impact of volatility, making it a tried-and-true strategy for beginners.


Further Reading

To deepen your understanding of financial markets and trading, explore these additional resources from Finwirestack:


External Resources (DoFollow Links)


Disclaimer: Trading cryptocurrencies carries significant risks, such as price volatility and market risks. Before deciding to trade cryptocurrencies, consider your risk appetite. Seek professional financial advice if you are unsure. The information provided in this article is for educational purposes only and does not constitute financial advice.